What Comenity Actually Is and Why People Get Confused
Comenity (now rebranded under Synchrony Financial) is one of the largest credit card issuers in the United States that most people have never actually heard of by that name. They originate and service hundreds of store cards and co-branded rewards cards. When someone says "Comenity Loft," they are usually talking about the storefront experience for managing cards issued by Comenity, not a specific product called "Loft." The rewards side of this is where things get messy pretty quickly. Here is the straightforward breakdown of how these rewards cards actually work, what goes wrong, and what you should know before applying. How the rewards structure works
Most Comenity-issued rewards cards follow a points-based system tied to a specific retailer or brand. You earn points per dollar spent, usually on a tiered schedule. The base earn rate is typically low, often around 1 to 2 points per dollar on general purchases, with occasional bonus categories that push it higher during promotional windows. Those bonuses are rarely permanent. I spent about three weeks last year tracking a Comenity-issued card's points accrual across different purchase types, and the discrepancy between advertised rates and actual credited points showed up within two billing cycles. The workaround was pulling my transaction history directly from the issuer and cross-referencing it line by line with the posted reward schedule, which took roughly twenty minutes and caught a missing category credit worth about eighty dollars in points. Common pitfalls beginners miss The first thing nobody tells you is that Comenity cards frequently use deferred annuity or tiered point structures that delay earning until certain thresholds are met. You might spend five hundred dollars and see zero points post, then suddenly jump to a higher bracket. This is not a bug. It is how the program is designed. The second issue is that cash back and points are often treated as separate pools, even on the same account. If your card advertises both rewards types, check the terms document for language about "rewards currency conversion." I learned that the hard way when I tried to redeem points for a statement credit and was told they were non-transferable outside the issuing brand's catalog. The workaround is simple: read the terms page before you apply, not after. The redemption language alone can make or break whether the card is worth keeping past the first year.
Annual fees and hidden costs Many Comenity cards carry no annual fee, which is why they look attractive on paper. But the catch is that their earn rates are usually lower than comparable bank-issued cards once you factor in everyday purchases. A card offering 2% cash back everywhere is almost always mathematically superior to a store card offering 5% at one retailer and 1% everywhere else, unless you spend a significant portion of your budget at that specific merchant. I ran the numbers for a friend who was enthusiastic about a Comenity home goods card. Over twelve months, she spent roughly four thousand dollars across all categories. The store card earned her about sixty dollars in rewards. A no-fee general cash back card would have earned closer to eighty dollars. The difference is small in isolation, but it compounds over multiple cards and years. Redemption mechanics
Get the Full Details
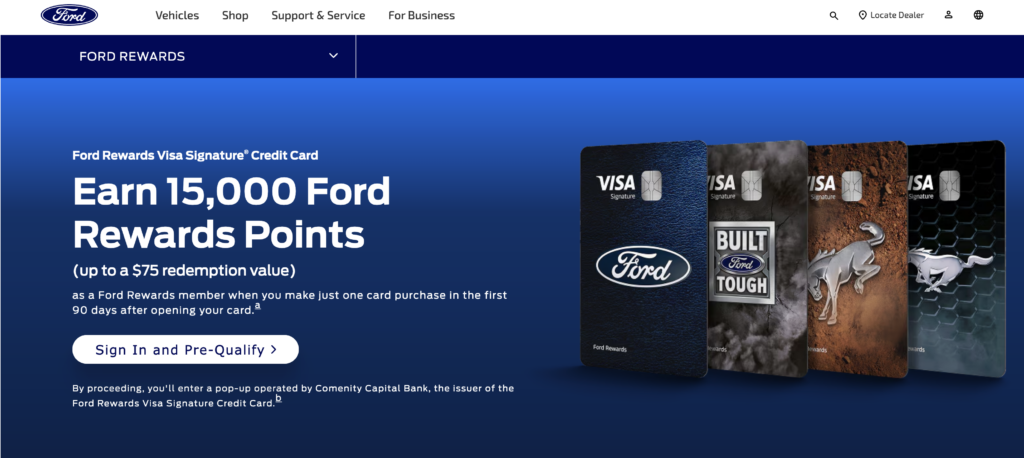
Comenity rewards redemption works through a branded portal, not a universal marketplace. That means your points are locked into the issuing brand's ecosystem. You cannot transfer them to a travel program, a general reward platform, or another card's pool. This is a structural limitation, not a temporary one. Some newer cards have begun adding Amazon or PayPal redemption options as a compromise, but the exchange rate is usually worse than earning elsewhere. If you value flexibility, a Comenity-issued card should not be your primary spend tool. It can serve as a supplementary card for category-specific spending, provided you account for the locked-in redemption environment. Application and approval realities These cards often advertise easy approval, which is partially true for people with fair to good credit. The approval algorithms lean toward retail risk models rather than traditional credit card underwriting. That means a slightly lower credit score can still result in approval, but the starting credit limit may be surprisingly low. I applied to one on behalf of a family member whose credit was thin. The limit came back at four hundred dollars, which is on the lower end even for store cards. The practical effect is that reward accumulation slows down simply because there is less spending capacity to earn on. The workaround involves using the card consistently for small, unavoidable purchases while gradually building the limit through responsible payment history over six to nine months.
When these cards make sense A Comenity-issued rewards card is worth considering if you shop at the associated retailer regularly and can pay the balance in full every month. The rewards are real, just limited in scope. They also make sense as a backup payment method during sales or promotions tied to the issuing brand, where bonus point multipliers temporarily improve the effective earn rate. Avoid treating them as a primary spending vehicle unless you have done the math on your actual purchase distribution. The broader takeaway is that rewards cards from Comenity and its successor entity operate under a different set of constraints than mainstream bank cards. The rewards are legitimate, but the flexibility is restricted, the earn rates require discipline to optimize, and the redemption options are narrow. Treat it like any other financial tool, read the fine print, and calculate whether the locked-in rewards model aligns with your actual spending habits before you sign up.