Understanding the Comenity Bank Loft Credit Card
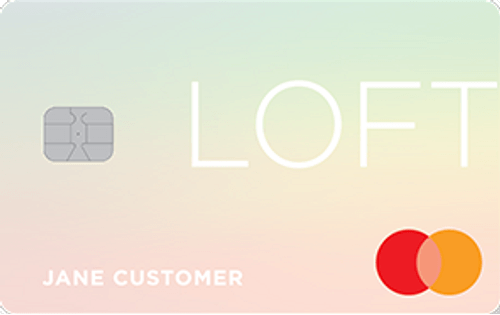
The Comenity Bank Loft Card is a store-branded credit card designed specifically for shoppers at LOFT, the women's clothing and accessories retailer. It's one of those cards you'll see offered at checkout counters and during promotional events, usually tied to a sign-up bonus like 20% off your first purchase or waived shipping on online orders. Comenity Bank manages a huge portfolio of retail cards, and the Loft card follows the same general structure as most of them. It's a closed-loop card in practice, meaning it only works at LOFT and its affiliated channels. That limitation is both its main feature and its biggest drawback.
The Ultimate Guide To Comenity Bank Loft Card Unlocking Exclusive Benefits And Rewards For Fashion Enthusiasts
Here is what the card actually offers beyond the initial promotional discount. Cardholders typically earn a set number of points per dollar spent at LOFT, and those points can be redeemed against future purchases, usually at a fixed conversion rate. The exact numbers shift over time as Comenity restructures its rewards programs, so I would not treat any specific point value as permanent. The current framework generally lets you accumulate enough points for a meaningful discount after a few months of regular shopping. Beyond points, the card occasionally provides access to exclusive sales events, early notification of seasonal collections, and occasional percentage-off coupons sent through email or the cardholder portal. These are not consistent every month, and they tend to appear more heavily during peak retail periods like back-to-school and holiday shopping seasons. I have dealt with this card through multiple renewals and reward cycles, so here is the practical side of things. When you apply, expect a soft pull initially if you are shopping in-store and opt for instant approval. The hard inquiry happens once the account is fully opened. Approval thresholds are moderate. You do not need excellent credit, but you also will not qualify with a thin file or recent delinquencies. Comenity tends to target consumers in the 640 to 700 range, though that is a rough band and not a rule.
One thing that catches people off guard is the annual fee structure. The Loft card carries no annual fee, which sounds straightforward, but there are other costs worth tracking. Late payments trigger standard penalty APRs, and Comenity, like most issuer banks, reports payment history to all three major credit bureaus. A single missed payment can drop your score by 50 to 100 points depending on your overall profile. That matters because many people apply for store cards casually without realizing how heavily it influences their broader credit strategy. Another nuance is the rewards redemption process. Points do not automatically apply at checkout. You have to log into your account and manually redeem them or select the redemption option during the purchase flow. I once tried checking out with what I thought was an active reward applied, only to realize I had never clicked the redeem button. The system does not remind you in a way that is impossible to miss, but it is easy enough to overlook if you are used to cards that auto-apply discounts. Always double-check the rewards section before finalizing a transaction, especially if you are chasing a specific discount tier. The customer service experience is average for a retail card issuer. Phone wait times vary, and the chat support can be useful for straightforward questions about points balance or statement credits. But if you run into a billing dispute or an error with a promotional offer not applying correctly, be prepared to escalate. I spent about twenty minutes on hold once trying to get a promotional discount that was supposed to attach to my account after signup. The representative could not locate the promo code in the system, so I had to follow up with a chat transcript reference number and a screenshot of the original offer page. It resolved after a second call, but the initial experience was frustrating and unnecessary.
Get the Full Details

If you are considering this card primarily for the rewards, evaluate your actual shopping frequency at LOFT. The card makes sense if you shop there regularly and can absorb the balance each month without carrying debt. If you are already a frequent shopper, the points and occasional exclusive sales add up over time. If you rarely visit LOFT or its affiliated stores, the card is a liability waiting to happen because you will either forget about it, accumulate a balance, or let the account sit unused and potentially attract fees through inactivity penalties depending on your terms. The interest rate is another factor that deserves attention. Variable APRs on retail cards like this one are typically higher than average credit cards. You should expect a range that puts you well above prime, sometimes approaching 25 percent or more depending on your credit profile and market conditions. Carrying a balance on this card is expensive, and the rewards earned do not come close to offsetting the interest cost. Pay it off every cycle. There is also a practical consideration regarding credit utilization. Because this is a store card with a relatively low limit compared to general-purpose credit cards, it can skew your utilization ratio if you are not careful. A $500 limit card with a $400 balance will inflate your overall utilization significantly. That is worth factoring in if you are actively managing your credit score for a major purchase soon.
Activation and setup are straightforward. You receive your card, register it online, and set up online banking. The mobile app works adequately for basic functions: checking your balance, making payments, viewing rewards, and managing notifications. It is not the most polished interface, but it covers the essentials. I prefer using the web portal for larger transactions or when I need to download statements, since the app occasionally lags when pulling recent activity. For people who shop at LOFT regularly and want a straightforward rewards tool without worrying about annual fees or complex tier structures, this card does the job. It is not a premium travel card, and it is not designed to be one. It is a focused retail card that works best when you understand its limitations and use it intentionally. If you plan to apply, have your Social Security number, employment information, and annual income ready. The application is quick, and the approval decision is usually instant or within a few minutes. Just be honest on the application. Misrepresenting income or details can delay approval or result in a denial that shows up on your credit report. The rewards program itself is simple enough that you do not need a spreadsheet to track it. Points accumulate per dollar spent, and redemption thresholds are predictable. The main challenge is staying consistent with payments and remembering to redeem before any expiration policy kicks in. Check the terms annually because Comenity has been known to adjust reward structures and expiration windows without dramatic announcements. A quick review of your cardholder agreement once a year can save you from losing points you thought were still valid.
If you are looking for something more versatile, a general-purpose cash back card or a travel rewards card might serve you better. The Loft card is niche, and its value is directly proportional to how much you shop at LOFT. Use it for that purpose, pay it off in full, and collect the points without treating it as a primary financial tool. That is the most reliable way to get something out of it.