Chesapeake is a sprawl problem that most people don't understand until they move there
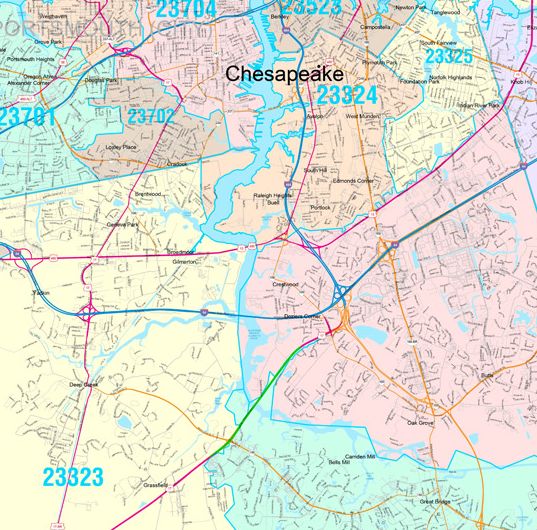
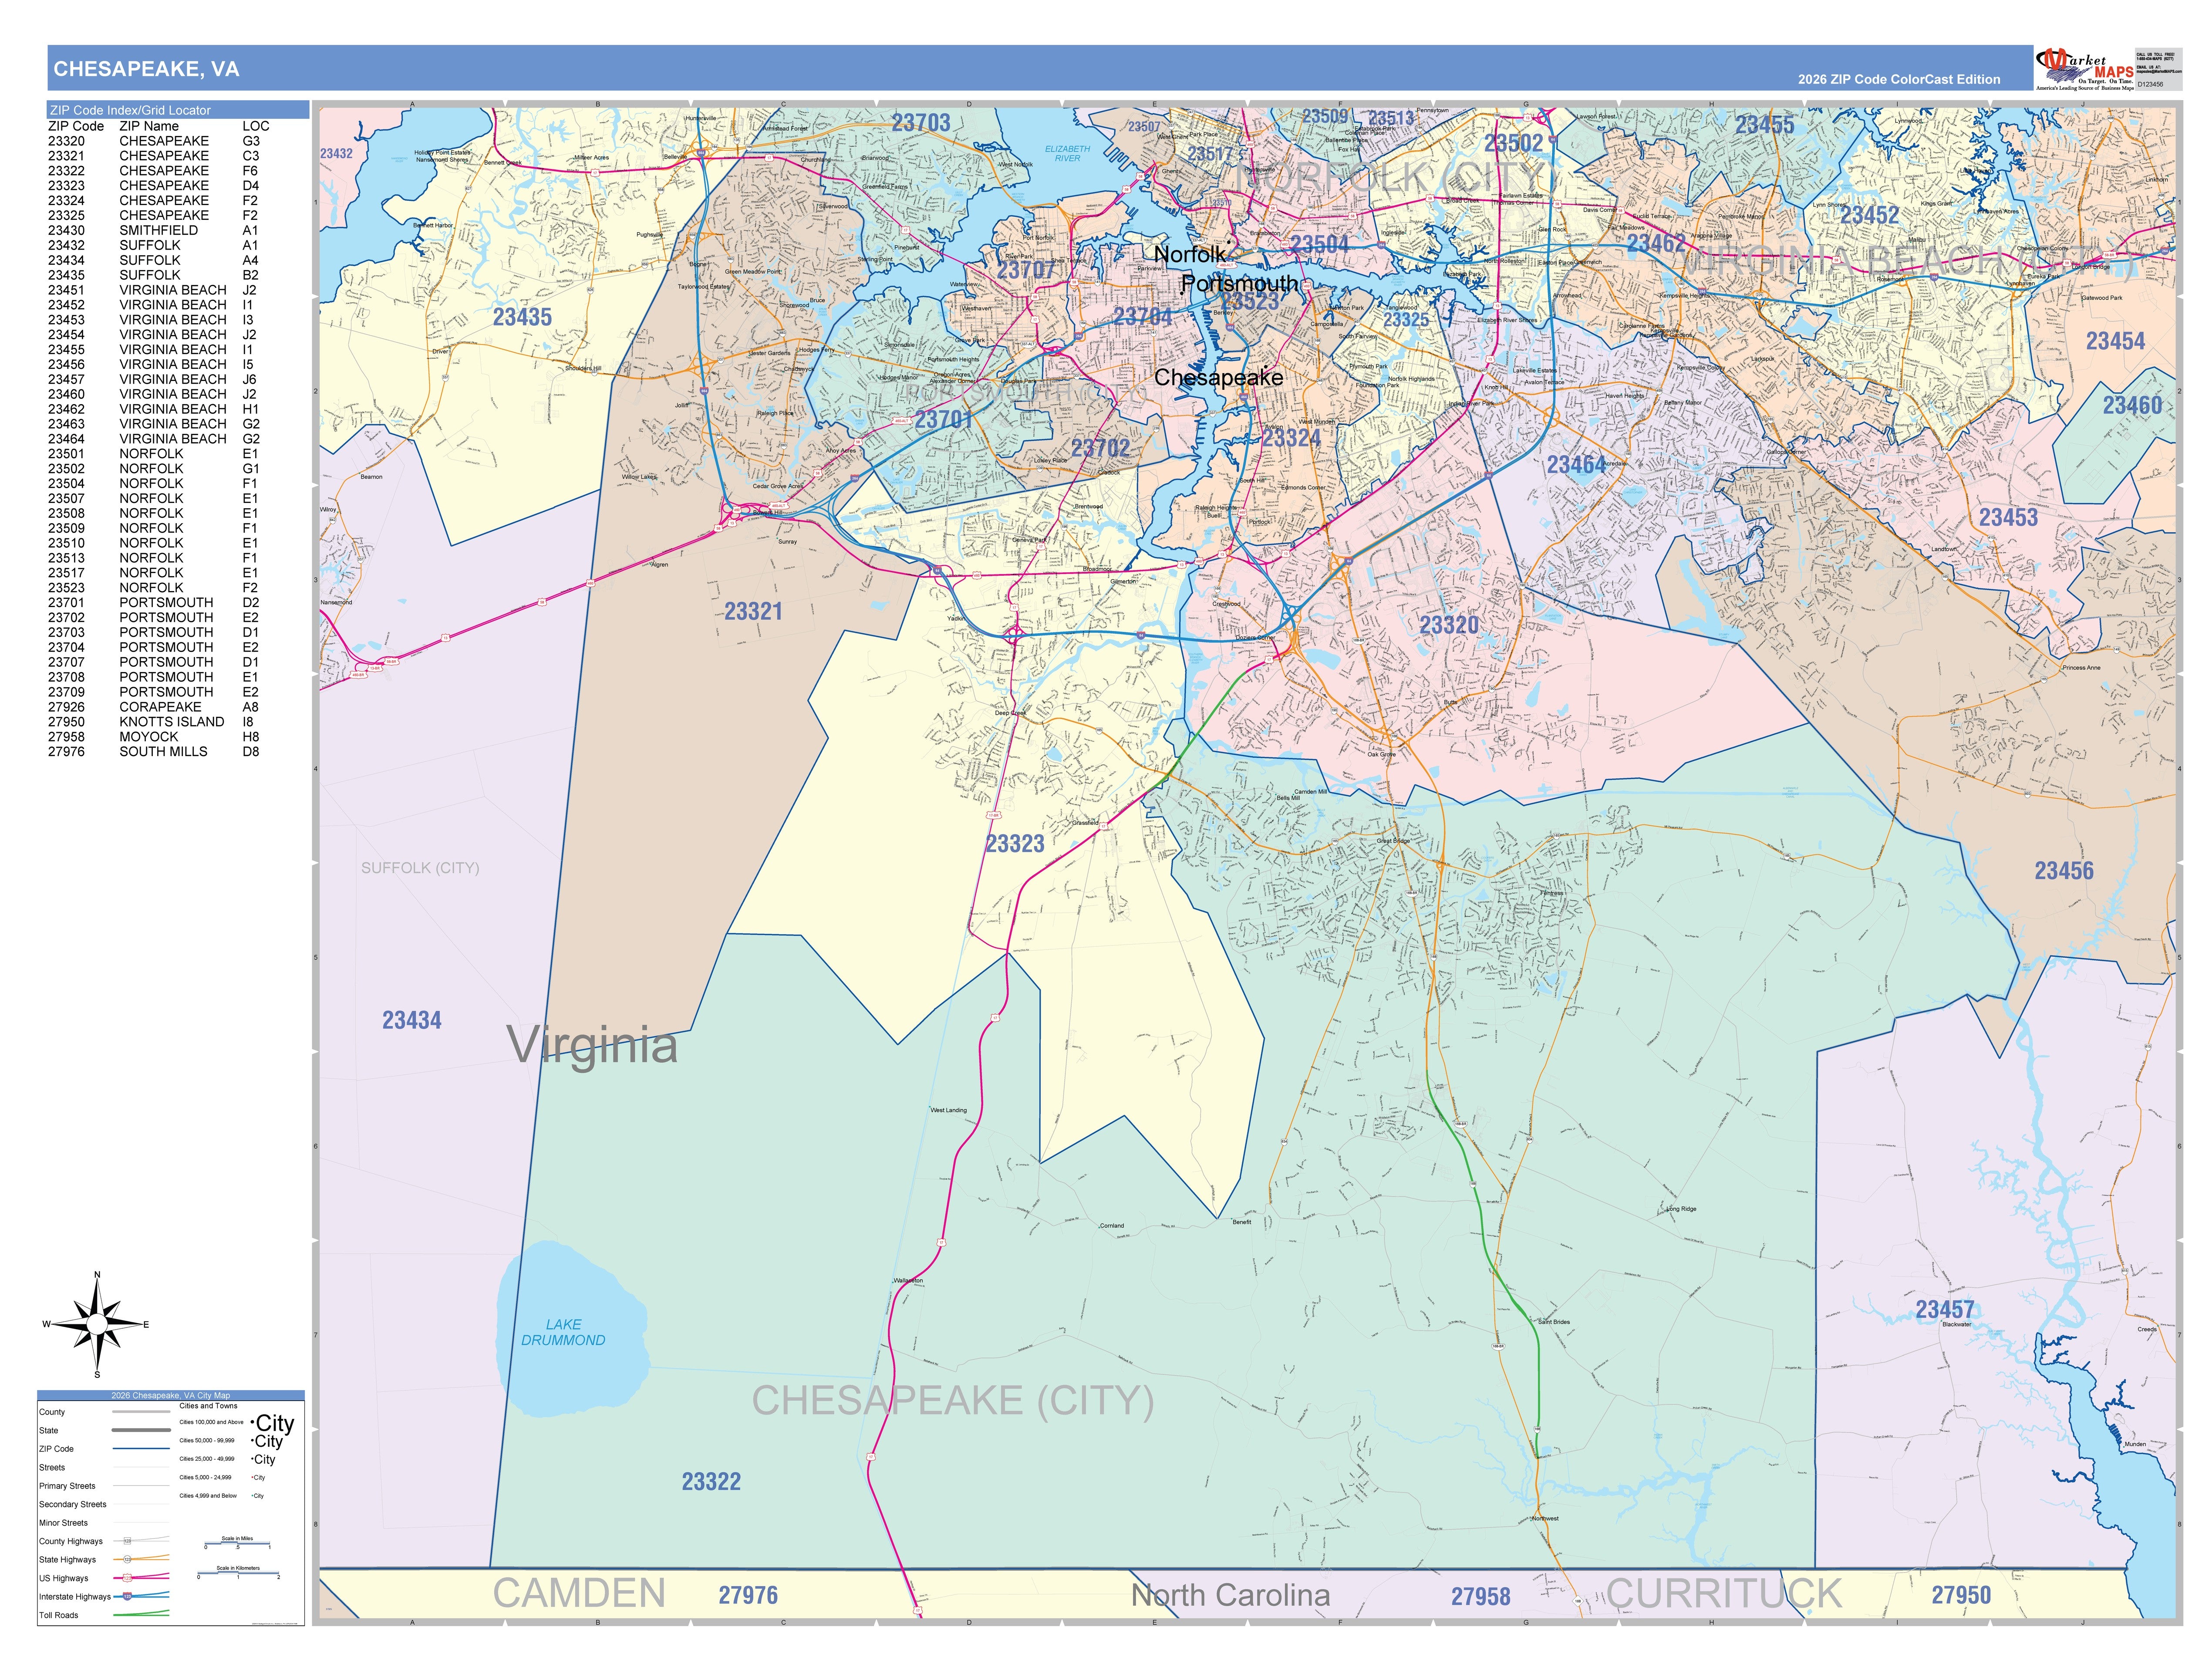
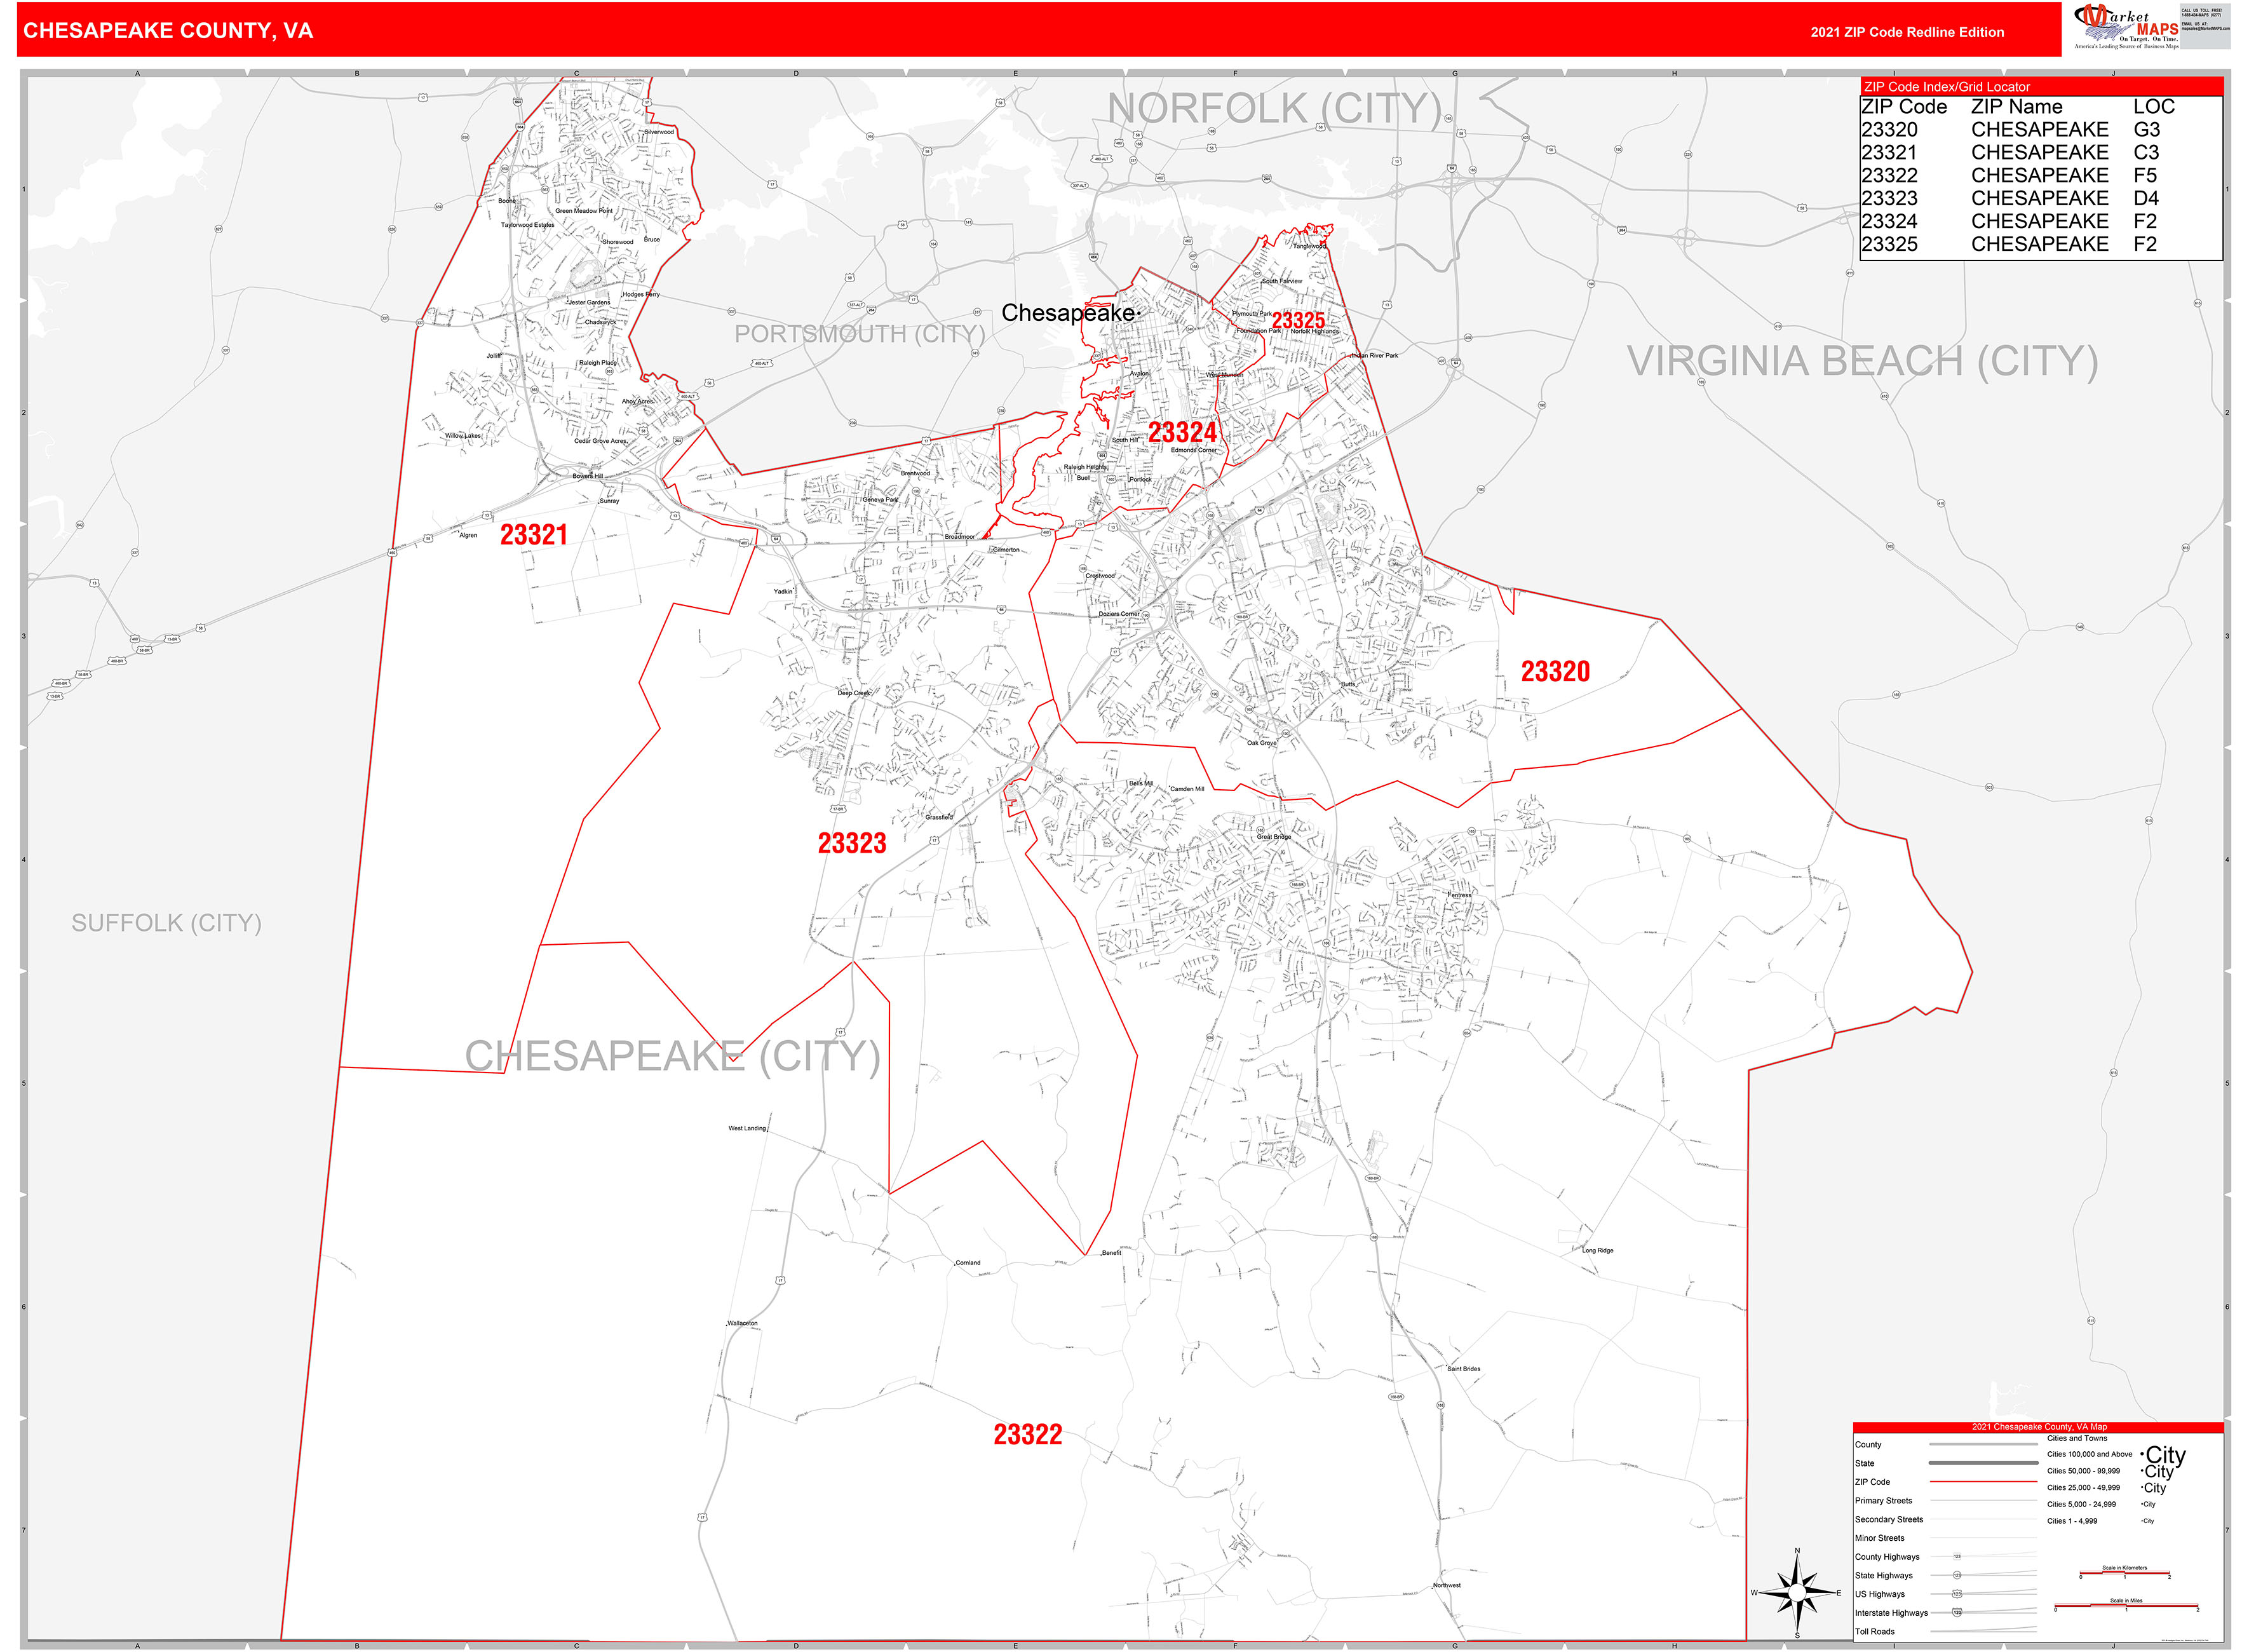
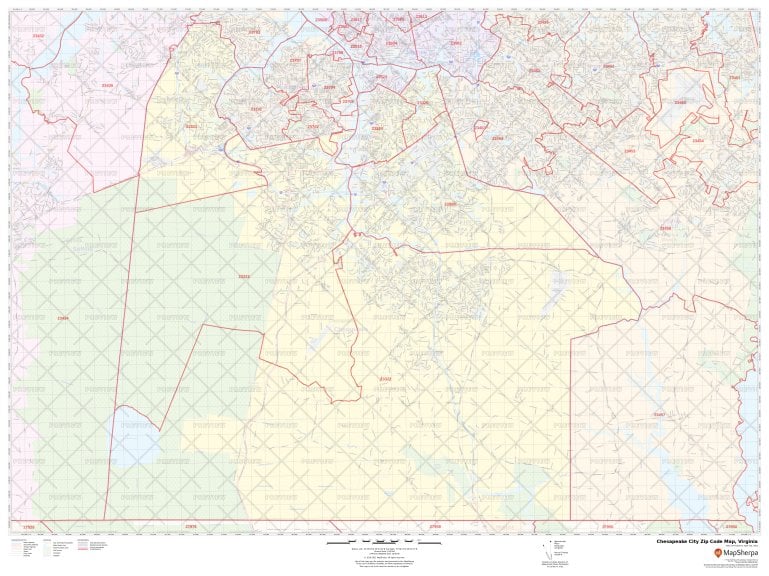
Chesapeake, Virginia is the largest city in the United States by land area. It covers about 347 square miles and sits southeast of Norfolk and south of Hampton. The zip code system here doesn't map cleanly onto neighborhoods the way it does in older Eastern Seaboard cities. You'll see 23320, 23321, 23322, 23323, 23324, 23325, 23326, 23327, 23328, 23336, 23337, 23338, 23346 and a few others overlapping in ways that confuse anyone trying to get a read on the market quickly. I spent three years tracking resale data across these codes before I stopped treating them as meaningful boundaries. They barely are. A house in 23322 can be a five-minute drive from an almost identical house in 23323, and yet they get priced differently because one falls under a different school zone. That's the first thing you need to understand about buying or selling in Chesapeake. The zip code matters less than the school boundary and the subdivision.
The Ultimate Guide To Chesapeake Va Zip Code Neighborhoods Schools And Real Estate Insights
The Chesapeake Public Schools district has been improving over the last decade, but the variation is extreme. Great Creek High School in the 23322 area consistently ranks in the top tier of Virginia schools.Creek State Elementary and nearby middle schools feed into that pipeline. The math works out: families willing to pay a premium cluster around those boundaries and push prices up accordingly. I watched a Colonial-era home in the Greenbrier area go from $425,000 to $610,000 between 2019 and 2022 just because the school ratings shifted and the buyer pool expanded from local to Richmond commuters. But the flip side is just as important. Areas around 23321, 23323, and 23324 have schools that rank significantly lower on state report cards. That doesn't mean they're bad. It means they serve a different demographic and price point. You'll find solid two-story colonials built in the 1980s with ranch-style additions, older mobile home parks adjacent to commercial corridors, and a lot of investor-owned rentals. If you're looking for appreciation, these areas move slower. If you're looking for affordability, they're still the best option in the city. Going north toward 23320 and 23325, you enter the Bayside and Western Branch areas. These are older neighborhoods with tighter street grids and smaller lots. Homes here tend to be 1,200 to 1,800 square feet, built between 1960 and 1985. The school zones feed into Western Branch High and Bayside Elementary. Neither school is considered a magnet draw, which keeps prices reasonable. I've seen 3-bedroom, 2-bath brick ranchers in 23320 hold steady at $240,000 to $290,000 for years while the rest of the city surged. Good for a first-time buyer who wants to live somewhere with character and not watch their equity get gamed by school district speculation.
The 23328 area around Pinehurst and the southern part of the city is its own universe. It's mostly rural, some of it agricultural, some of it just land that hasn't been paved yet. Properties here range from restored farmhouses on 5-acre parcels to custom-built luxury homes near the James River. The schools are isolated and the commute to Norfolk or Virginia Beach is 30 to 45 minutes depending on traffic. You're not buying into a neighborhood here. You're buying into privacy. The price range starts around $350,000 and goes up without any real ceiling. I know one seller who listed a 4,000-square-foot lakefront property in 23328 and took six months to close because the buyer was waiting on a jumbo loan approval during a rate spike. Now let me tell you about the problem that actually catches people off guard. Chesapeake's flood zones. The city sits on a peninsula between the Elizabeth River and the Chesapeake Bay, and a lot of the newer developments in 23322, 23324, and 23327 are being built in areas that FEMA classifies as AE or VE flood zones. This matters for insurance, for financing, and for resale. I had a client who fell in love with a new-construction home in a 23322 subdivision. The model home looked perfect. The lot sat maybe 200 feet from a retention pond. We ran the flood zone lookup and found the property was in an AE zone with a base flood elevation that required the lowest floor to be raised 18 inches above grade. The builder had done exactly that, but it meant the finished garage was partially below grade and would need sump pumps and backflow valves. Insurance quoted was $4,200 a year. The homeowner's policy alone was $2,800. That changed the monthly payment enough that the deal fell apart. The workaround is straightforward but nobody checks it upfront. Pull the FEMA flood map for the exact parcel before you make an offer. Not the neighborhood average. The parcel. Use the FIS (Flood Insurance Statement) and check the FIRM (Flood Insurance Rate Map) panel number. If the property is in an AE or VE zone, get a survey done. If it's in an X zone but near a body of water, assume you'll still need flood insurance anyway. Most lenders require it within the designated floodplain. The cost difference between a home in and out of the floodplain can be $150 to $300 a month in total housing costs when you factor in insurance and any elevation requirements.
Get the Full Details
Here's another thing most people miss about Chesapeake real estate. The military influence. NAS Oceana, Naval Air Station Hampton Roads, and several Coast Guard stations are all within 20 minutes of most of the city. A significant portion of buyers are military families on PCS orders. This creates a predictable market rhythm. When the Navy is expanding its aviation programs, demand in 23322 and 23327 spikes. When base realignment happens or budget cuts hit, those same areas cool faster than civilian-driven markets. I tracked this pattern across two deployment cycles and saw a consistent 8 to 12 percent price swing tied directly to Navy personnel changes. It's not dramatic, but it's real and it affects your timeline. If you're selling, the best time to list is usually late summer before the school year starts. Military families want to close during the summer so they can relocate before fall. If you list in October or November, you'll compete with fewer buyers but also attract fewer. The inventory drops but the demand drops harder. I've seen sellers sit on the market for 90 days in winter when the same house would have gone in 14 days in August. Buying in Chesapeake also means dealing with a market where the old Norfolk suburban model no longer applies. The City of Norfolk proper has been declining in terms of single-family home values while Chesapeake has absorbed the overflow. People who would have bought in Norfolk 15 years ago now buy in Chesapeake because the schools are better and the tax situation is more favorable. This has pushed Chesapeake home prices up roughly 40 percent since 2018, which means the affordability advantage is shrinking. A $350,000 home in 23322 today is not the same deal as a $350,000 home in 23322 in 2020. The square footage is smaller, the lot is smaller, and the competition is fiercer.
One more thing that's worth knowing about the school situation. Chesapeake Public Schools uses a magnet school program. If you're willing to apply to a magnet program, you can access higher-performing schools outside your assigned zone. The application window is typically January through February for the following school year. I know several families who used this strategy to get their kids into Great Creek High without moving to the 23322 area. It's a legitimate pathway that most out-of-town buyers don't know about. Check the CPS website directly. Don't trust what the real estate agent tells you about school zones without verifying against the district's official boundary maps. The real estate market in Chesapeake is not going away. It's growing. The population has increased by roughly 15 percent over the last decade and infrastructure projects like the bridge toll changes and I-664 improvements keep making it more accessible. But the easy money from the 2020 to 2022 boom is gone. Prices have stabilized. Inventory has improved slightly. The market is now a normal balance between buyer and seller power, which means due diligence actually matters again instead of being glossed over in a bidding war. If you're starting your search, pick three zip codes, not one. Drive through them at different times of day. Check the school boundaries yourself. Run the flood zone check on every property you consider. Factor in the military market rhythm if you're on a timeline. And remember that zip code is a convenience for the postal service, not a reliable proxy for neighborhood quality. The differences you're looking for are in the school zones, the flood maps, and the subdivision histories. Everything else is just noise.