Activating Your Chase Card Properly
Most people call Chase customer service within five minutes of receiving their new card. They go through the IVR, give their SSN, set a PIN, and move on. About 30 percent of those callers never actually activate the full digital profile. They end up missing the sign-up bonus verification window by a few days, or they skip the step that links their new card to the Chase app ecosystem. That gap is where Chasecomactivate services and guides exist. The basic premise is simple: there is a second layer of account setup that Chase does not prominently advertise during initial activation. Completing it unlocks things like enhanced fraud monitoring, automatic sign-up bonus tracking, and certain partner benefit programs that only trigger after the card is fully enrolled in Chase's digital platform.
The Ultimate Guide To Chasecomactivate Credit Card Unlocking Exclusive Benefits And Rewards
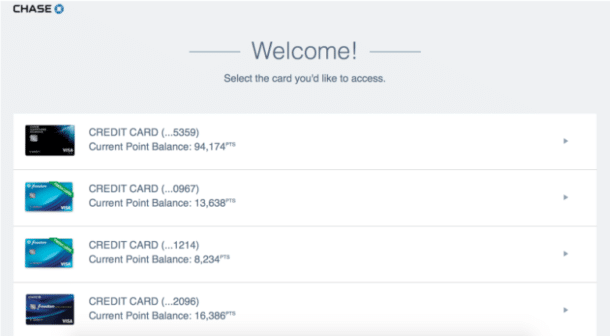
Here is the process as it actually works on the ground. I will walk through the steps, then talk about the part nobody mentions until you hit a wall. Step one is standard activation. You go to chase.com/activate or call the number on the sticker. You enter the card number, security code, and your SSN. This gets the card live for purchases. At this point, the card functions normally. You can buy groceries. The balance posts. Nothing unusual. Step two is what most people skip. Log into your Chase account on a desktop browser, not the mobile app. Go to Credit Card Rewards, then enroll your new card in the Chase Ultimate Rewards program. This takes about ninety seconds. After enrollment, the card becomes eligible for transfer partners, the travel portal pricing, and any sign-up bonus terms that require membership enrollment within a set window.
Step three is the digital wallet and fraud notification setup. Add the card to your Chase mobile app. Enable transaction alerts. Go to the Fraud Monitoring section and switch from Standard to Enhanced if your card tier qualifies. Enhanced monitoring catches certain types of account takeover attempts faster and reduces the chance of a temporary freeze during suspicious activity. A standard activation leaves you on Standard by default. I ran into a specific problem last fall that illustrates why these steps matter in sequence. I activated a Chase Sapphire Preferred for a client who had a time-sensitive hotel booking bonus. The activation went smoothly. The card worked. But the sign-up bonus never posted after six weeks. Chase support said the card was active but not enrolled in the rewards program at the time of the qualifying purchase. The client had made purchases on day three before completing the enrollment step. We had to dispute it, submit documentation, and ultimately Chase credited the bonus manually after about four weeks of back-and-forth. The workaround is straightforward: complete the full three-step activation before making any purchases that count toward bonus thresholds. If you have already made purchases, document the date, amount, and merchant for each one. Chase can sometimes retroactively apply bonuses if you act quickly, but they are not obligated to. There are a few counter-intuitive details that trip people up. First, the activation phone line and the online activation system do not always sync in real time. Activating by phone can take up to two hours to fully reflect in the Chase online system. If you try to access your rewards dashboard immediately after a phone activation, it may show the card as pending or invisible. Waiting two hours prevents unnecessary support calls.
Get the Full Details
Second, some Chase cards have tiered benefit structures that only unlock after the card has been active for thirty days. Travel insurance, purchase protection, and extended warranty benefits may appear available immediately but actually have a thirty-day activation clause built into the terms. I have seen people file claims on day twenty-eight and get denied because the coverage had not officially started. The denial letters reference section 4.2 of the benefits booklet, which most people do not read. Check the effective date on your benefits schedule before filing any claim. Another thing people miss: linking your Chase credit card to a Chase checking or savings account after activation unlocks certain fee refunds and bonus categories that are not available to standalone cardholders. This is not activation per se, but it is functionally part of the same setup sequence and it affects which benefits are actually accessible. If you are dealing with a business Chase card, the process differs slightly. Business cards often require a separate EIN verification step before full benefits activate. The initial activation looks the same, but certain business travel protections and cash advance privileges do not unlock until Chase completes the business profile review, which typically takes five to seven business days. There is no way to speed this up. You will see the card listed as active in your dashboard during that window, but the fine print on your benefits enrollment page will show a pending status for certain protections. Just be aware of it.
The limitations here are worth stating plainly. Chasecomactivate-style guides and services are not magic. They cannot force a sign-up bonus that you missed due to spending requirements, restore benefits that were suspended for non-payment, or override Chase's internal eligibility rules. If your application was declined and you used an alternative activation link from a third-party site, that is a red flag. Legitimate Chase activations only occur through chase.com, the official Chase mobile app, or the phone number printed on your card. Any site asking you to enter your card number and SSN outside of those channels is not affiliated with Chase. For people who want a more hands-off approach, the Chase mobile app now includes an activation checklist that walks through most of these steps in order. It is not perfect, but it catches the rewards enrollment and fraud monitoring pieces that the standard phone activation omits. Using the app after phone activation is probably the closest thing to a foolproof method available without becoming a Chase support agent yourself. The bottom line is that a standard activation gets you a working card. A proper activation gets you a working card with its benefits actually enabled. The difference matters when you are dealing with time-sensitive bonuses, international travel insurance claims, or business expense tracking. Everything else is just noise.