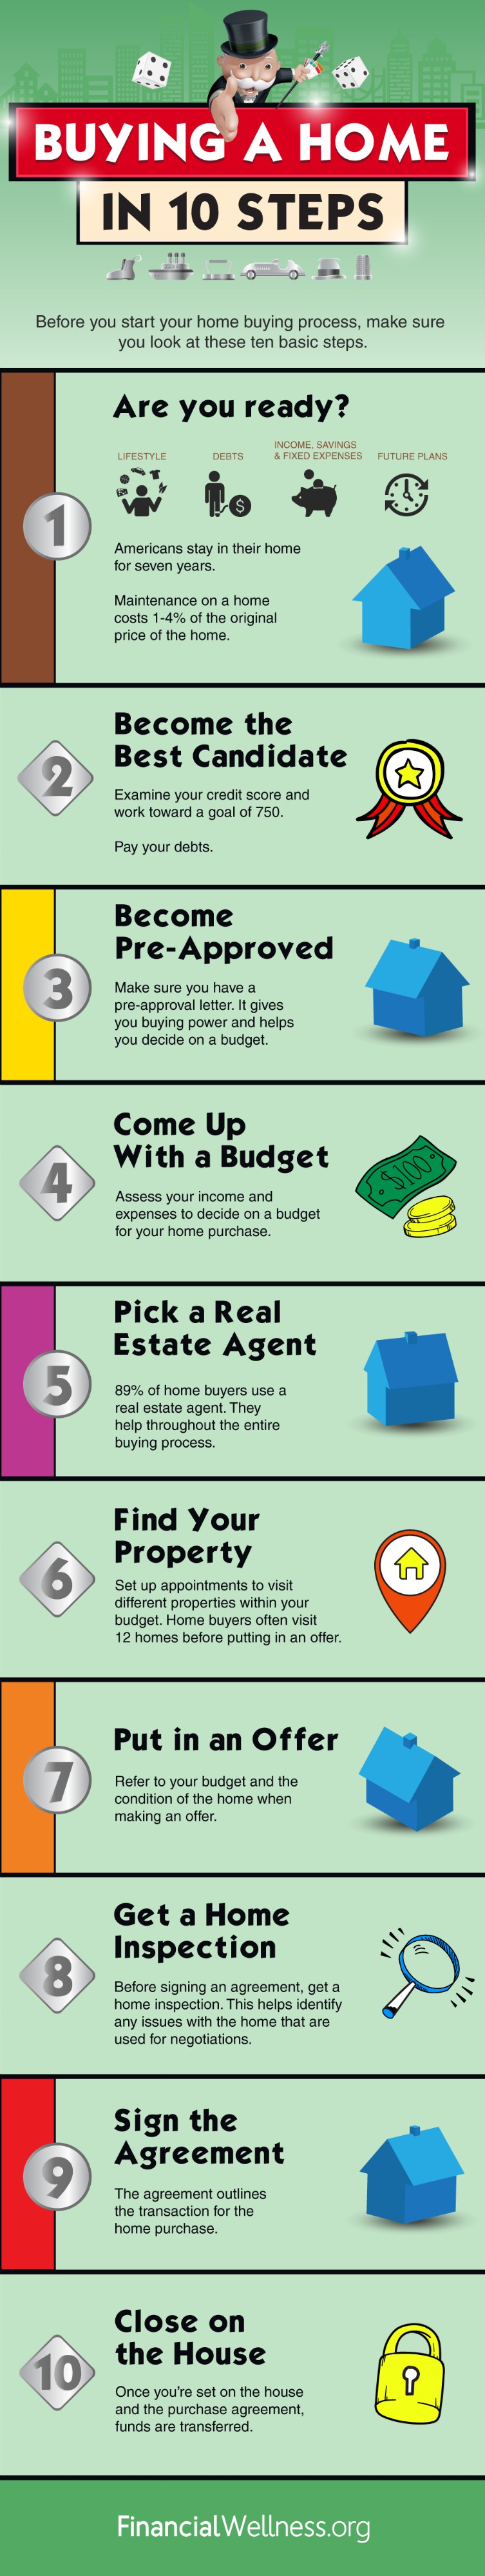
Buying property in the UK is not simple, but it is tractable if you stop treating it like a series of emotional decisions and start treating it like a transaction management problem.
I have watched people burn six months and tens of thousands on purchases that fell apart over paperwork they never understood. The process itself is standardized, but the bottlenecks are where most buyers get stuck. Here is how you actually move from decision to completion without losing your deposit or your mind. The first thing nobody tells you is that your budget is not what you think it is. People look at a mortgage calculator online and assume the monthly payment is the only cost. It is not. Stamp Duty Land Tax, solicitor fees, survey costs, arrangement fees, and the inevitable moving expenses add roughly 4 to 6 percent on top of the purchase price before you have even opened a box. If you are looking at a £350,000 property in London, you are realistically looking at around £385,000 in outgoings. Plan for that or you will be cash-strapped the week you move in. Getting an Agreement in Principle before you make any offers is the single most practical thing you can do. Lenders will check your credit file and give you a conditional figure within minutes on most digital platforms. It costs nothing. Agents and sellers take you seriously when you have it because it signals you are not wasting time. Without it, your offer gets filed under "maybe" and everyone moves on to buyers who can prove otherwise.
Searching and evaluating properties
Rightmove and Zillow UK are the main portals, but the actual market moves on two channels you rarely see listed publicly. Estate agents often have off-market inquiries circulating in WhatsApp groups before anything hits the website. And properties sometimes sell before they are listed at all through word of mouth between agents. If you are serious, get a local agent to put you on their buyer list. It takes thirty seconds and it can save you from watching three houses go to bid before you even see the front door. When you view a property, look past the staging. Check the damp evidence in cupboards and behind furniture. Look at the outside walls near roof level, not just the paint job. The condition of the boiler and roof will dominate your post-purchase reality more than anything else. A new kitchen does not offset a replacement boiler or a roof needing work, and those are bills you cannot defer. Here is the counter-intuitive part that most beginners miss: a Surveyor's HomeBuyer Report is not always the right choice. For older properties, converted buildings, or anything that looks like it has been modified, a full Building Survey makes more financial sense. The HomeBuyer report is a middle-ground option that assumes standard construction. If the property has timber floors, solid walls, or extensions that were never signed off, the HomeBuyer report will gloss over structural concerns that a Building Survey would flag. The extra cost is usually around two hundred pounds and it can surface issues worth thousands in remediation.
The offer and negotiation
Offers in England and Wales are not legally binding until contracts are exchanged. That means you can withdraw at any point, but the seller is not locked in either. This is why the chain is the most destructive variable in the entire process. If the seller is also buying a home and their purchase is contingent on theirs completing, every link in that chain can drag on or collapse. I once had a buyer pull out three days before exchange because the survey came back with subsidence concerns on a listed property. Their solicitor had not checked that the property's listing status would complicate the mortgage offer. The whole transaction unraveled because someone skipped one check. When negotiating price, remember that asking prices are often set deliberately high. In a balanced market, properties tend to settle somewhere between 3 and 8 percent below the asking price. In a slow market, that gap widens. The estate agent wants a quick sale, not necessarily the highest price for you, so use their urgency as leverage. Ask directly about previous offers and days on market. If a property has been listed for forty-five days with no offers, the seller is likely motivated. Use that, but do not be aggressive about it.
Get the Full Details

Surveys and legal work
Order your survey after your offer is accepted, not before. This is a common mistake that wastes money when offers fall through. Once the offer is in, commission either a HomeBuyer Report or a Building Survey depending on the property type and age. Simultaneously instruct a solicitor or licensed conveyancer. The legal work is where delays most commonly creep in. Standard conveyancing in England and Wales takes between eight and twelve weeks from offer acceptance to completion. Some completions happen in six weeks. Others stretch to fourteen. The variance comes down to three things: how responsive the seller's solicitor is, whether the title is complicated, and how quickly your mortgage lender issues the formal offer. There is an edge case that catches people out. If you are buying a leasehold property, the lease length and ground rent terms matter enormously. A lease with fewer than eighty years remaining will be difficult to mortgage and expensive to extend. I worked with a client who fell in love with a flat in Manchester because of the location and price. The lease had seventy-two years left and a doubling ground rent clause every ten years. The mortgage valuation came in below the purchase price because the lender saw the lease as a risk. We had to renegotiate the price downward by roughly fifteen thousand pounds to account for the lease extension cost. Without catching that early, the deal would have collapsed at exchange.
Mortgage formal offers and completion
Your mortgage Agreement in Principle is not the same as a formal offer. The formal offer comes after the lender completes their valuation and underwriting. This process typically takes one to three weeks. Do not assume your mortgage is secured just because you have an API letter. If the valuation reveals issues that affect the lender's security position, they may adjust the amount they are willing to lend or ask for additional conditions. Once your solicitor raises enquiries and the seller's solicitor responds, you will reach a point called "ready for exchange." This is the moment when both parties confirm they are prepared to proceed. After exchange, the deal is legally binding. You will pay a deposit, usually 10 percent of the purchase price, and your solicitor will arrange the transfer of funds. Completion happens on the date agreed in the contract. Your solicitor transfers the purchase money to the seller's solicitor, and the keys are released. This is usually a morning process on a weekday. You will typically get the keys between noon and three in the afternoon, depending on when the funds clear and the chain allows.
Post-completion considerations
Your solicitor will register the transfer with HM Land Registry. This can take anywhere from two weeks to several months depending on current processing times and whether any anomalies appear in the registration. You will receive a confirmation letter once it is done. In the meantime, you are the legal owner even if the registration has not completed yet. Set up utility accounts, council tax registration, and change of address with relevant agencies before you move in. The first month after completion is when everything gets expensive if you are not organized. Council tax bands are based on 1991 valuations, so the amount you pay may surprise you. Check the band and budget accordingly. Also, if you are buying with a help-to-buy equity loan or any shared ownership arrangement, there are additional stamp duty and valuation considerations that standard purchases do not have. The process outlined here is the standard route for a freehold purchase with a mortgage in England and Wales. Scotland operates differently with its own system of surveys and offers. Northern Ireland has its own land registry processes. If you are buying in those jurisdictions, the general principles apply but the legal mechanics diverge enough that you need specialist advice tailored to that region. The biggest mistake people make is assuming the process is identical across the UK. It is not.