How to Actually Buy a Business in Houston Without Getting Burned
I started helping people evaluate Houston businesses around 2012, right after the oil price collapse pushed a bunch of distressed sellers onto the market. I watched the same mistakes repeat every single year. People read the listings, fall in love with the revenue number, and skip the parts of the process that actually matter. The first thing you need to understand is that most businesses listed as "owner motivated" are not. They're either stuck with an owner who can't operate them anymore due to health issues, they have serious customer concentration problems, or the seller genuinely knows something the listing doesn't mention. None of this is malicious usually. But it is very common.
Where to Find The Ultimate Guide To Buying A Business For Sale In Houston
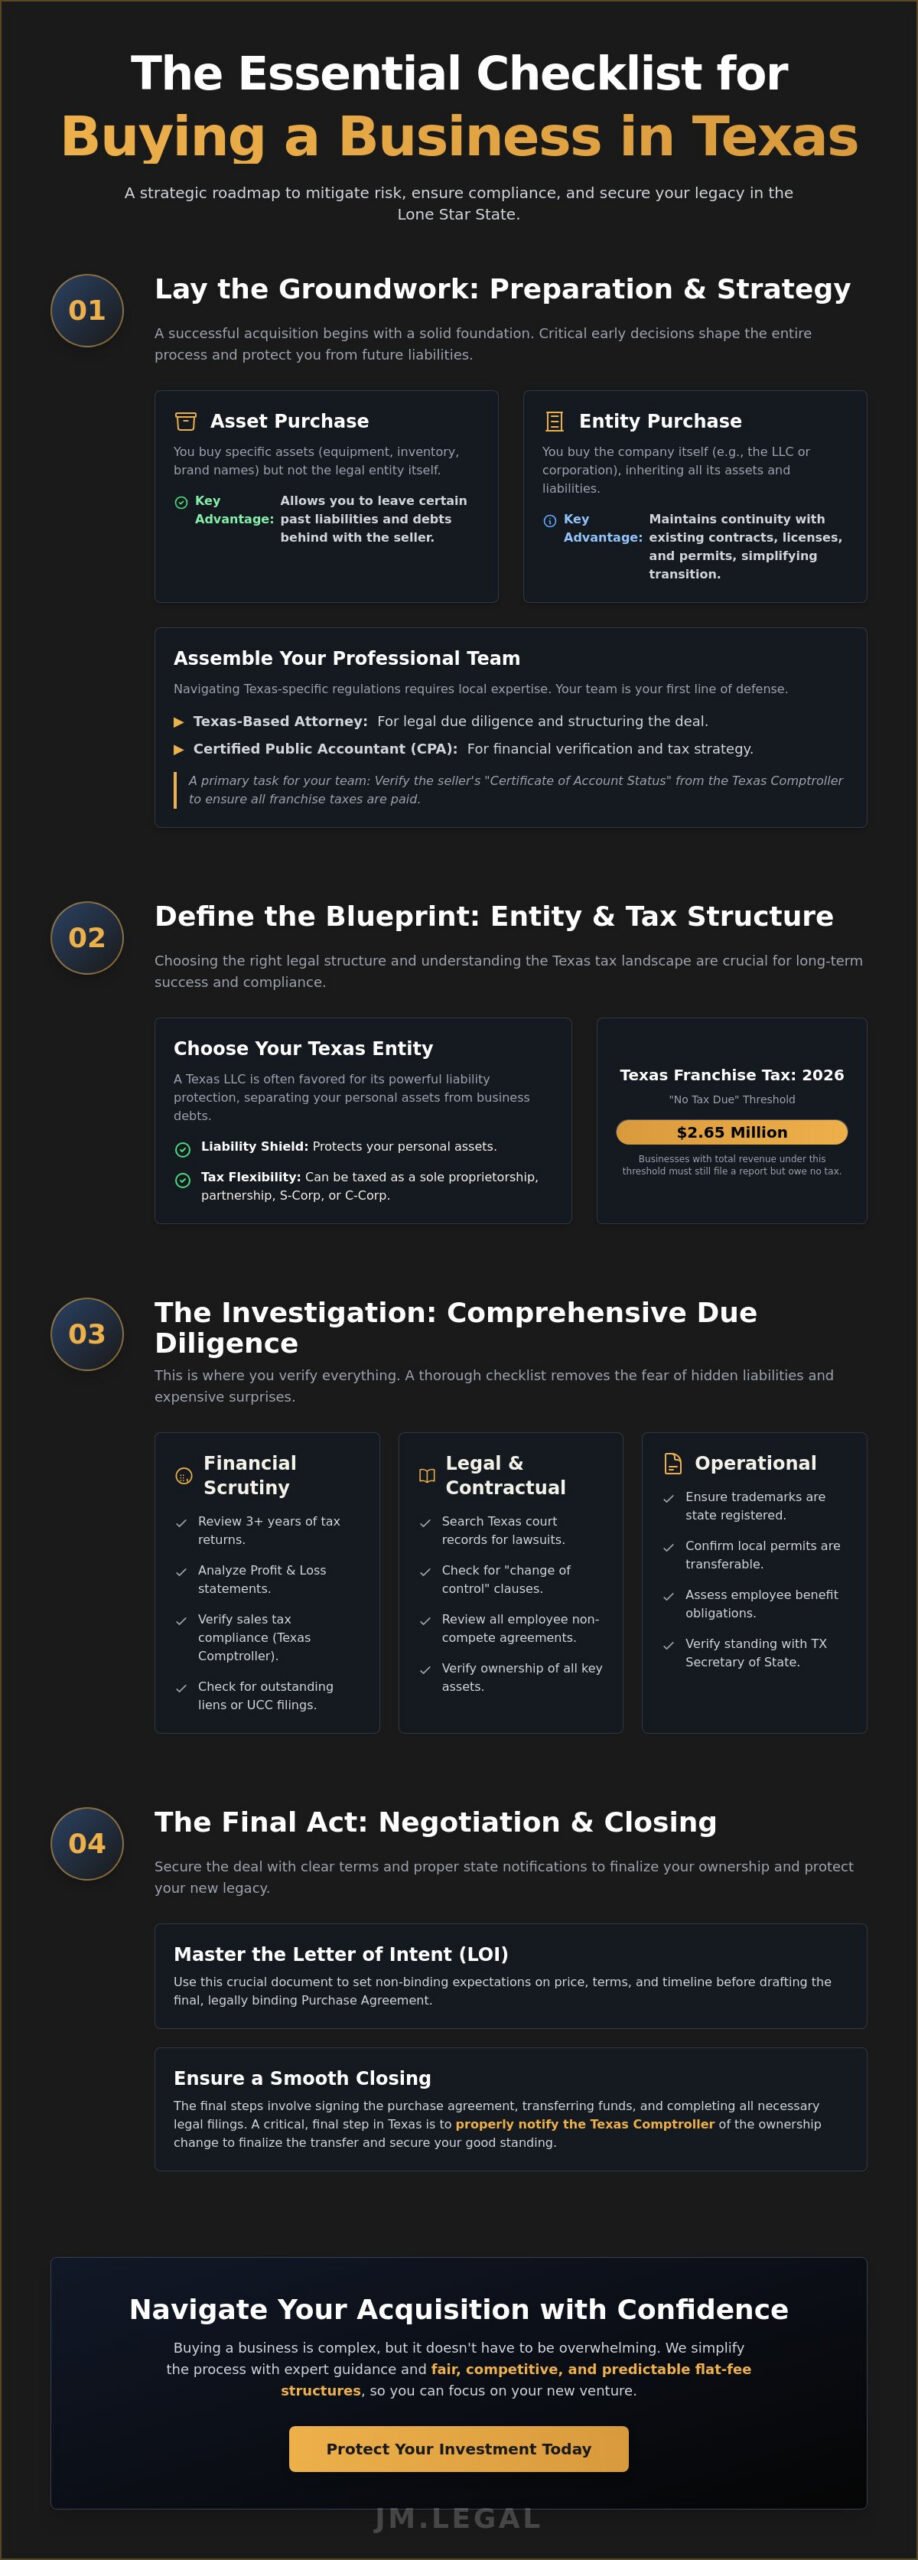
There isn't really one definitive document that covers everything. What exists is scattered across SBDC resources at Rice University, Harris County small business development materials, and broker platforms like BizBuySell and BusinessBrokers.net. The practical approach is to pull from all three simultaneously rather than relying on any single source. The SBA's own guide for Houston-area lenders is decent but outdated in places. I recommend cross-referencing with recent local court records to see what actual deal structures are working now versus what the official documents say should work. When I'm guiding someone through a purchase, I usually have them pull the business's Texas Franchise Tax History report first. This single document, which costs about $26 and takes ten minutes to get from the Comptroller's website, tells you whether the company has been actively filing, when it was originally registered, and if there are any administrative dissolutions on record. It sounds minor but I've seen at least four deals this decade fall apart because the business's legal existence was already compromised and the seller didn't know or didn't disclose it.
The Due Diligence Process That Actually Works
Most people treat due diligence like a checklist. It isn't. It's a series of layered investigations where each answer generates three new questions. Start with the financials, but not the P&L statement they handed you. Ask for the actual tax returns filed for the past three years, the year-to-date profit and loss from their accounting software, and a detailed schedule of owner compensation that separates salary from distributions from any personal expenses run through the business. The gap between those two documents is where problems hide. A plumbing business in Katy might show $180,000 in S&P and $220,000 in tax returns. The $40,000 difference is usually something mundane like a truck payment the owner forgot to categorize, or it could be unreported cash receipts that won't survive an audit. Either way you need to know which it is before you write a check. Customer concentration is another area where people routinely get blindsided. In Houston specifically, with so many industries tied to energy and healthcare, a single corporate account can represent 40 or 50 percent of revenue. When that account leaves, the business isn't "down slightly." It's often insolvent within six months. Request a customer-by-customer revenue breakdown for the last 24 months and flag anything above 15 percent immediately.
Get the Full Details
Financing in the Houston Market
SBA 7(a) loans are the standard path and they work reasonably well for acquisitions under $1 million. The problem is that Houston has a limited number of approved SBA lenders who actually understand main street businesses versus tech startups. I've lost count of how many brokers will send you to "any SBA lender" and then watch you get bounced around for six weeks between different branch offices that don't talk to each other. The workaround I use is to identify two or three SBA-approved lenders in the Houston area who specialize in small business acquisitions and go directly to them before you even find a business. Get pre-qualified with paperwork in hand. A solid pre-qualification letter from a known local lender carries more weight with sellers than a generic pre-approval from a national bank. It also means when you make an offer, you're not losing time waiting for financing to clear. For deals over $500,000, expect to put down at least 10 to 15 percent of your own money. The SBA won't finance everything and no legitimate seller is going to accept 100 percent seller financing unless something is deeply wrong. I've seen sellers offer generous terms to buyers who weren't asking the right questions about inventory valuation or lease assumptions. Those buyers ended up inheriting leased equipment that was three months behind on payments and a commercial lease with two years remaining at above-market rates.
Structuring the Deal So It Doesn't Fall Apart
Asset sales versus stock sales is the first structural decision and it matters more than people realize. An asset sale means you pick what you buy and leave the liabilities behind. A stock sale means you inherit everything including unknown lawsuits, pending violations, and employee claims. In Texas, the difference also affects sales tax. Asset purchases trigger sales tax on the transferred inventory and equipment unless you structure it carefully with proper Form 05-205 filing with the Texas Comptroller. Here's a specific problem I ran into last year. A buyer in Sugar Land was purchasing a restaurant and everything looked clean on paper. The seller had perfect books, strong revenue, and a great location. During the asset purchase agreement review, we discovered the walk-in refrigerator was leased, not owned, with a remaining lease term of 18 months at $1,200 per month. The purchase price didn't account for it. The monthly P&L the seller provided included the refrigerator payment but buried it inside "miscellaneous expenses" so it never appeared as a line item. That's $21,600 in assumed liability the buyer walked into not knowing about. We renegotiated the price downward by $18,000 to offset it and the seller agreed because he knew we'd found it. Employee transition is another structural minefield. If you're buying a services business with recurring contracts, those contracts often have change-of-control clauses. A property management company in Midtown, for example, had 300 units under management and every single lease contained language requiring 90 days notice if ownership changed. The seller assumed the tenants would just stay. They didn't. Half of them moved within four months because the new owner couldn't immediately assure them of continuity. Revenue dropped by roughly 45 percent in the first quarter.
Common Pitfalls That Have Nothing to Do with the Numbers
Commercial lease assumptions deserve their own section because people consistently underestimate how much work this involves. Houston has a mix of triple net leases, gross leases, and percentage leases and the type matters enormously. A NN (triple net) lease means you pay base rent plus your share of property taxes, insurance, and CAM charges. When you take over, those expenses can jump significantly, especially in older Houston buildings where property tax assessments tend to spike after ownership changes. The landlord won't tell you this proactively. I once worked with a buyer who assumed the lease on a retail space in The Woodlands came with 10 years remaining. It actually had 7 years and a escalation clause that increased rent by 5 percent every two years. By year four of ownership, the monthly payment had grown by nearly 15 percent and the seller's financials never reflected this trajectory. Always get a complete, executed copy of the lease and read the amendment history. There are almost always amendments buried in there. Zoning is another area where Houston's lack of traditional zoning makes things more complicated rather than less. Houston doesn't have conventional zoning districts. Instead it relies on use ordinances and overlay districts. A business that operates legally today in an industrial area might be subject to a new use ordinance restriction that gets proposed at any city council meeting. I've seen buyers close on a auto repair shop in northeast Houston only to discover that a rezoning application was already in the pipeline that would have prohibited their operation within 18 months. The city's planning department website has a docket you can search for pending proposals near any address.

What to Do After You Close
Most guides stop at closing. That's a mistake. The first 90 days determine whether the acquisition was actually successful. Update your banking relationships, get a new EIN if you structured as a new entity, and immediately review every vendor contract for change-of-control provisions. Insurance policies need to be replaced not just renewed. Your old policy covered the seller's operations. A new policy covering your operations starts fresh with different terms and limits. Employee retention is the silent deal-killer. In Houston's tight labor market, key employees can leave within 30 days of an ownership change if they sense uncertainty. I've seen sellers agree to stay on for 90 days post-close and then disappear the moment the wire hits. Don't let that happen. Structure a transition period into the purchase agreement with a bonus or continuation payment tied to their actual presence. Make it financially painful for them to abandon you during the handoff. The competitive landscape in Houston shifts fast. A business that dominates a neighborhood today can lose its position tomorrow when a competitor opens two miles away. Don't assume current market position is permanent. Build a 12-month operational plan before you close that accounts for exactly that possibility.