Understanding the gap between what comes in and what goes out
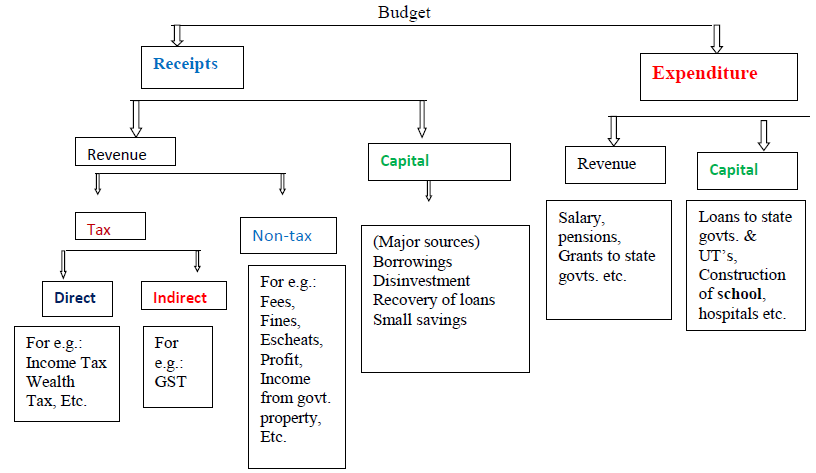
Most people think budgeting is just adding up numbers and hoping they match. In practice it is a constant negotiation between competing claims on a fixed set of resources. I have spent over a decade working on public finance projects across three continents, and the single most useful thing I learned early on is that the textbook definition of budget economics barely covers the real work. When governments and households try to balance revenue and expenditure the friction is never in the arithmetic. It is in the timing, the uncertainty, and the political economy of deciding who gets paid and who does not. At its core budget economics studies how agents with limited income allocate spending across competing priorities over time. The standard textbook answer involves three steps. You estimate revenue. You enumerate expenditures. You ensure the two sides meet. That description is accurate in the same way a map of a city is accurate. It shows the streets but it does not tell you which ones are closed for construction or which intersections flood every rainy season. The real mechanism involves rolling forecasts, contingency reserves, debt management, and a set of institutional rules that determine whether a shortfall gets covered by borrowing, by cutting services, or by raising taxes next cycle. I want to share something that does not appear in introductory courses. A budget is not a plan. It is a legal document that authorizes spending and creates obligations. When a municipality approves a capital budget for a new water treatment plant it is not forecasting. It is committing future revenue streams to a specific liability. Households do the same thing when they sign a mortgage. The economics of that commitment involve discount rates, default risk, and the option value of waiting. Most people ignore the option value entirely. They treat a budget as if it were a static snapshot rather than a sequence of decisions under uncertainty.
Revenue estimation is where everything usually breaks down
Governments rely on tax receipts, fees, transfers from higher levels of government, and sometimes resource rents. Households rely on wages, investment income, and occasional windfalls like inheritances or insurance payouts. The difference is not in the categories. It is in the volatility. A municipal budget in a resource-dependent town can swing twenty percent year to year based on commodity prices. A household budget can swing twenty percent if one earner loses a job. Both face the same fundamental problem. Revenue is uncertain while expenditure commitments are sticky. You cannot easily cut a pension obligation or a school staffing requirement overnight. I encountered a specific edge case last year that illustrates this perfectly. A mid-sized city in the American Midwest was projecting a ten percent drop in property tax revenue after a major employer relocated. The finance director wanted to freeze all capital spending immediately. The problem was that thirty percent of the budget was already committed to contractual obligations. Debt service, union contracts, and state-mandated services could not be cut. The only lever available was the reserve fund, which was already tapped for emergency storm repairs. We spent three weeks building a rolling twelve-month forecast updated monthly rather than relying on the annual budget. That process reduced the probability of a cash shortfall from near certainty to about fifteen percent over the next fiscal year. The workaround was not elegant. It was just less bad than letting payroll bounce.
Expenditure classification reveals more than you might expect
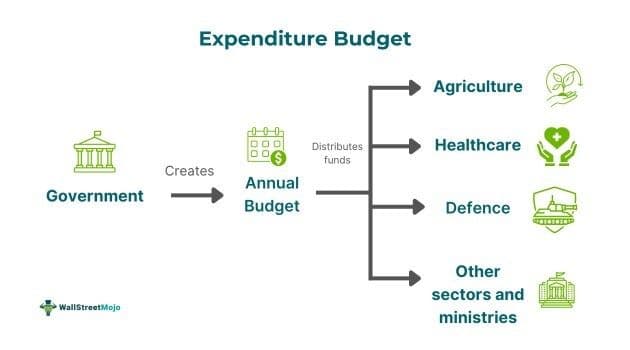
Operational spending covers salaries, utilities, maintenance, and purchased services. Capital spending covers infrastructure, equipment, and long-lived assets. Transfer payments cover pensions, subsidies, and intergovernmental grants. The distinction matters because each category behaves differently under stress. Operational spending is rigid. You can lay off some contractors but you cannot fire teachers without a negotiated process. Capital spending is discretionary in theory but not in practice because approved projects create momentum. Transfer payments are often legally mandated. A state pension obligation in Illinois is not something a mayor can rewrite unilaterally. Here is a counter-intuitive point that beginners miss. Discretionary spending is usually the smallest slice of a government budget. In the United States federal budget discretionary spending is less than forty percent. The rest is mandatory spending and debt service. Households face the same pattern. Mortgage payments, car loans, insurance premiums, and child support are not discretionary. The truly optional spending is groceries, entertainment, and dining out. Yet that is the only category people usually cut during a financial squeeze. They preserve the rigid obligations and then complain that the budget does not balance. The solution is not to cut discretionary spending more. It is to recognize that discretionary spending is already minimal and that the real adjustment has to come from revenue increases or from renegotiating the rigid obligations themselves.
Get the Full Details

Accounting methods shape outcomes more than you might think
Cash accounting records transactions when money changes hands. Accrual accounting records them when obligations are incurred. Modified accrual accounting, used by most U.S. municipalities, blends the two. It records revenue when it becomes measurable and available. It records expenditures when the liability is incurred. The choice of method affects when a shortfall appears. Under cash accounting a city might show a surplus because it delayed paying a vendor. Under accrual accounting the same city shows a deficit because the liability exists. Most analysts focus on the cash number because it determines whether payroll clears. The accrual number matters for long-term solvency because it reveals unfunded liabilities. I recommend looking at both numbers side by side. If a government shows a cash surplus but an accrual deficit it is borrowing from the future. The pension system is underfunded. The infrastructure is deferred. The cash surplus is an accounting illusion that disappears when the bills come due. Households do this too. You can show a positive bank balance this month while maxing out credit cards to cover last month's shortfall. The budget looks balanced. The reality is not.
Surplus and deficit dynamics are not symmetric
A budget surplus occurs when revenue exceeds expenditure in a given period. A deficit occurs when expenditure exceeds revenue. The standard textbook answer treats them as mirror images. In practice they are not. A surplus allows you to pay down debt, build reserves, or invest in capital projects. A deficit forces you to borrow, draw down reserves, or cut services. The asymmetry matters because it creates path dependency. A series of small deficits compounds into a structural deficit. A series of small surpluses compounds into fiscal space. The direction of travel depends on initial conditions more than annual performance. I have seen cities with ten years of surpluses still face a liquidity crisis because the surpluses were invested in illiquid assets. I have also seen cities with a single large deficit survive because they had strong reserves and clear revenue growth. The rule of thumb is that reserves should cover at least three months of operational spending. Anything less leaves you exposed to a revenue shock. Anything more means you are either overtaxing or underspending on public goods. The optimal level depends on revenue volatility, which varies by jurisdiction.
Debt management is where budgets usually get tested
Governments issue general obligation bonds, revenue bonds, and short-term notes. Households take out mortgages, auto loans, and credit card debt. The economics are identical. You borrow today to smooth consumption over time. The constraint is the debt service ratio. For governments the benchmark is often forty percent of revenue. For households the benchmark is forty-three percent of gross income. Exceeding the ratio triggers borrowing constraints. Lenders refuse to extend credit. Interest rates jump. The budget adjustment becomes forced rather than discretionary. I worked on a project where a county exceeded its debt service ratio by five percent after a revenue shortfall. The bond rating dropped from A to BBB. The interest rate on new issuance jumped from four percent to seven percent. The additional debt service cost amounted to twelve million dollars annually. That is enough to close a library system or cut police staffing by forty positions. The workaround was to refinance existing debt at lower rates and extend maturities. The process took eight months and required a state intergovernmental loan to bridge the gap. The lesson is that debt management is not a back-office function. It is a strategic discipline that determines whether a budget can absorb shocks or whether a shock becomes a crisis.
Reserve funds are insurance against your own optimism
Budget analysts call them fund balances, reserve funds, or stabilisation funds. Households call them emergency savings. The purpose is identical. They provide a buffer when revenue falls short or expenditure rises unexpectedly. The standard recommendation is three to six months of operational spending. The reality is that most governments hold less than two months. Most households hold less than one month. The gap between recommendation and practice exists because building reserves requires political will during good times. It is easier to spend surpluses on popular programs than to save them for storms that may never come. I encountered a case where a city with zero reserves faced a pandemic-related revenue collapse. The federal stimulus covered sixty percent of the shortfall. The rest came from cutting services and laying off staff. The city could have avoided the layoffs if it had held even two months of reserves. The cost of building those reserves would have been lower than the cost of the layoffs. The lesson is that reserves are not optional. They are the difference between a managed adjustment and a crisis response.
The political economy of budgeting cannot be ignored
Technically a budget is an allocation mechanism. Practically it is a political document that reflects power relationships. Elected officials prioritize visible programs over invisible ones. Infrastructure projects get funded. Maintenance backlog grows. Salaries get raises. Deferred costs accumulate. Households face the same dynamic. They buy the new car. They ignore the leaky roof. They prioritize consumption over resilience. The economics are the same. The incentives are political. I have seen budget processes where the technical analysis was clear. The data showed that preventive maintenance would save thirty percent in lifecycle costs. The political decision was to defer maintenance and fund a new downtown project instead. The new project was visible. The maintenance was not. The budget balanced on paper. The asset base deteriorated. The future costs were shifted to the next administration. This pattern is not unique to government. It is the default behaviour of any agent facing electoral or social pressure to show results today.
Performance budgeting promises efficiency but delivers complexity
The idea is straightforward. Link funding to outcomes. Measure results. Adjust allocations. In practice it adds layers of reporting requirements without changing behaviour. A municipality might spend two hundred thousand dollars annually on performance metrics while the underlying service quality remains unchanged. The budget analyst spends more time filling out forms than improving services. The elected official gets a report that looks good. The citizen gets the same service. The connection between spending and outcomes is too weak to detect at the program level. I recommend focusing on a few key indicators rather than dozens of vanity metrics. For a public health department the relevant metric is infection rate. For a transportation department the relevant metric is average commute time. For a household the relevant metric is net worth growth. Anything more granular adds noise without signal. The budget should reward progress on those metrics. It should not punish deviation from a plan that was already obsolete when it was written.

Forecasting accuracy improves with frequency, not with sophistication
Models can be elegant or crude. The difference in predictive accuracy is usually small. The difference between annual and monthly forecasting is large. An annual budget based on a single projection is vulnerable to revision. A monthly rolling forecast adapts to new information. The cost of monthly forecasting is modest. The benefit is early detection of revenue shortfalls or expenditure overruns. I recommend moving from annual to quarterly forecasting as a minimum. Moving to monthly is ideal but requires capacity that many small jurisdictions lack. I worked with a county that switched from annual to quarterly forecasting after a property tax reassessment caused a fifteen percent revenue decline. The annual budget had assumed stable values. The quarterly forecast caught the decline in the first quarter. The county adjusted spending before the shortfall became a crisis. The adjustment was painful. It involved cutting a capital project and deferring hires. But it was better than discovering the shortfall in December when options were exhausted. The takeaway is that forecasting frequency matters more than model sophistication. A simple moving average updated monthly beats a complex structural model updated annually.
Interpersonal comparisons of budget methods are usually misleading
Governments and households face different constraints. Governments can print money, impose taxes, and issue debt. Households cannot. Governments have sovereign immunity. Households do not. The comparison is useful for teaching basic concepts. It breaks down when you try to apply household budgeting advice to public finance or vice versa. A household should not borrow at seven percent to fund consumption. A government can borrow at four percent to fund infrastructure that yields ten percent in social returns. The discount rate is different. The constraint is different. The analogy is limited. I recommend using the comparison sparingly. It is useful for explaining the concept of a budget deficit to students. It is not useful for designing actual policy. The institutional context determines the feasible set of options. Ignore the context and you get advice that sounds reasonable but fails in practice. A household facing foreclosure cannot refinance at a lower rate. A municipality in default cannot access the bond market. The analogy masks the difference between illiquidity and insolvency. One is a cash flow problem. The other is a balance sheet problem. The remedies are different.
The limitation of any budget framework is its inability to predict black swan events
No model predicted the pandemic. No model predicted the 2008 financial crisis. No model predicted the Ukraine war and its impact on energy prices. The budget framework is designed for normal conditions. It breaks down under stress. The question is not whether a black swan will occur. The question is whether you have the reserves, the flexibility, and the political capital to respond when it does. The answer determines whether a shock becomes a catastrophe or a managed disruption. I have learned to design budgets with the assumption that something unpredictable will happen. That does not mean preparing for every scenario. It means holding enough reserves, maintaining enough debt capacity, and preserving enough political credibility to act decisively when the unexpected occurs. The cost of preparedness is visible in good times. The benefit is invisible until it is needed. Most budgets fail to account for this asymmetry. They optimise for the expected path rather than the range of possible paths. The result is a budget that looks efficient until it is not.
Practical steps to improve budget balancing in any context
Start by separating revenue into reliable and unreliable categories. Property tax is reliable. Sales tax is less reliable. Resource royalties are volatile. Build your baseline budget on reliable revenue only. Treat unreliable revenue as a bonus. If it arrives you can fund reserves or capital projects. If it does not you are not shortfall-plagued. Apply the same logic to households. Base your budget on salary income. Treat bonuses and overtime as optional. If you skip this step you will overestimate your capacity and undersave for the downturn. Second, calculate your debt service ratio monthly, not annually. Track it against the forty percent benchmark. If you approach the threshold early in the year you have time to adjust. If you discover it in December you are forced into abrupt cuts. Third, build a reserve equal to three months of operational spending before funding any discretionary project. Fourth, update your forecast quarterly at a minimum. Fifth, publish your key metrics transparently. Transparency creates accountability. Accountability reduces the incentive to manipulate numbers.
When the standard approach fails and what to do instead
The standard budget framework assumes stable institutions, predictable revenue, and rational actors. None of those assumptions holds in practice. If your jurisdiction faces revenue volatility above twenty percent, your budget should be designed for stress, not for normalcy. If your household faces income volatility above thirty percent, your budget should prioritise liquidity over optimisation. The remedy is not a better model. It is a more resilient structure. Higher reserves, shorter debt maturities, flexible spending categories, and clear trigger rules for automatic adjustments. I recommend replacing static annual budgets with rolling multi-year frameworks where feasible. A three-year rolling budget with annual updates allows you to see the medium-term trajectory while retaining the flexibility to adjust. It also forces you to confront the future cost of today's decisions. A pension reform passed today shows up in the budget ten years from now. A capital project approved today shows up in debt service twenty years from now. The rolling framework makes those future costs visible. The annual framework hides them. If you cannot implement a rolling framework, at least publish a ten-year fiscal outlook alongside your annual budget. The cost is modest. The benefit is transparency that constrains political opportunism.

