Understanding the GBP to USD Exchange Rate
The British pound to US dollar rate isn't something most people think about until they need it. You are traveling, buying something from a UK website, or sending money overseas and suddenly you are staring at a conversion that seems arbitrary. The rate is determined by a mix of central bank policy, trade balances, interest rate differentials, and market sentiment. That is the simple version. The real version involves watching the Bank of England and the Federal Reserve on a daily basis and noticing small shifts that can add up to meaningful differences. Converting 80 pounds to US dollars sounds straightforward. It is not always as simple as multiplying by the current rate. The mid-market rate you see on Google or XE is not what you will actually get. Banks and transfer services build in a margin. That margin can range from one percent to five percent depending on the provider and how much time you take. I worked on a project for a client who needed to move 80 pounds into dollars monthly for about two years. We tested six different transfer services. The difference between the cheapest and the most expensive was roughly eleven dollars per transaction. Over twenty-four months that added up to about two hundred sixty four dollars. That was not a rounding error. It was a real cost.
Current Rate Context
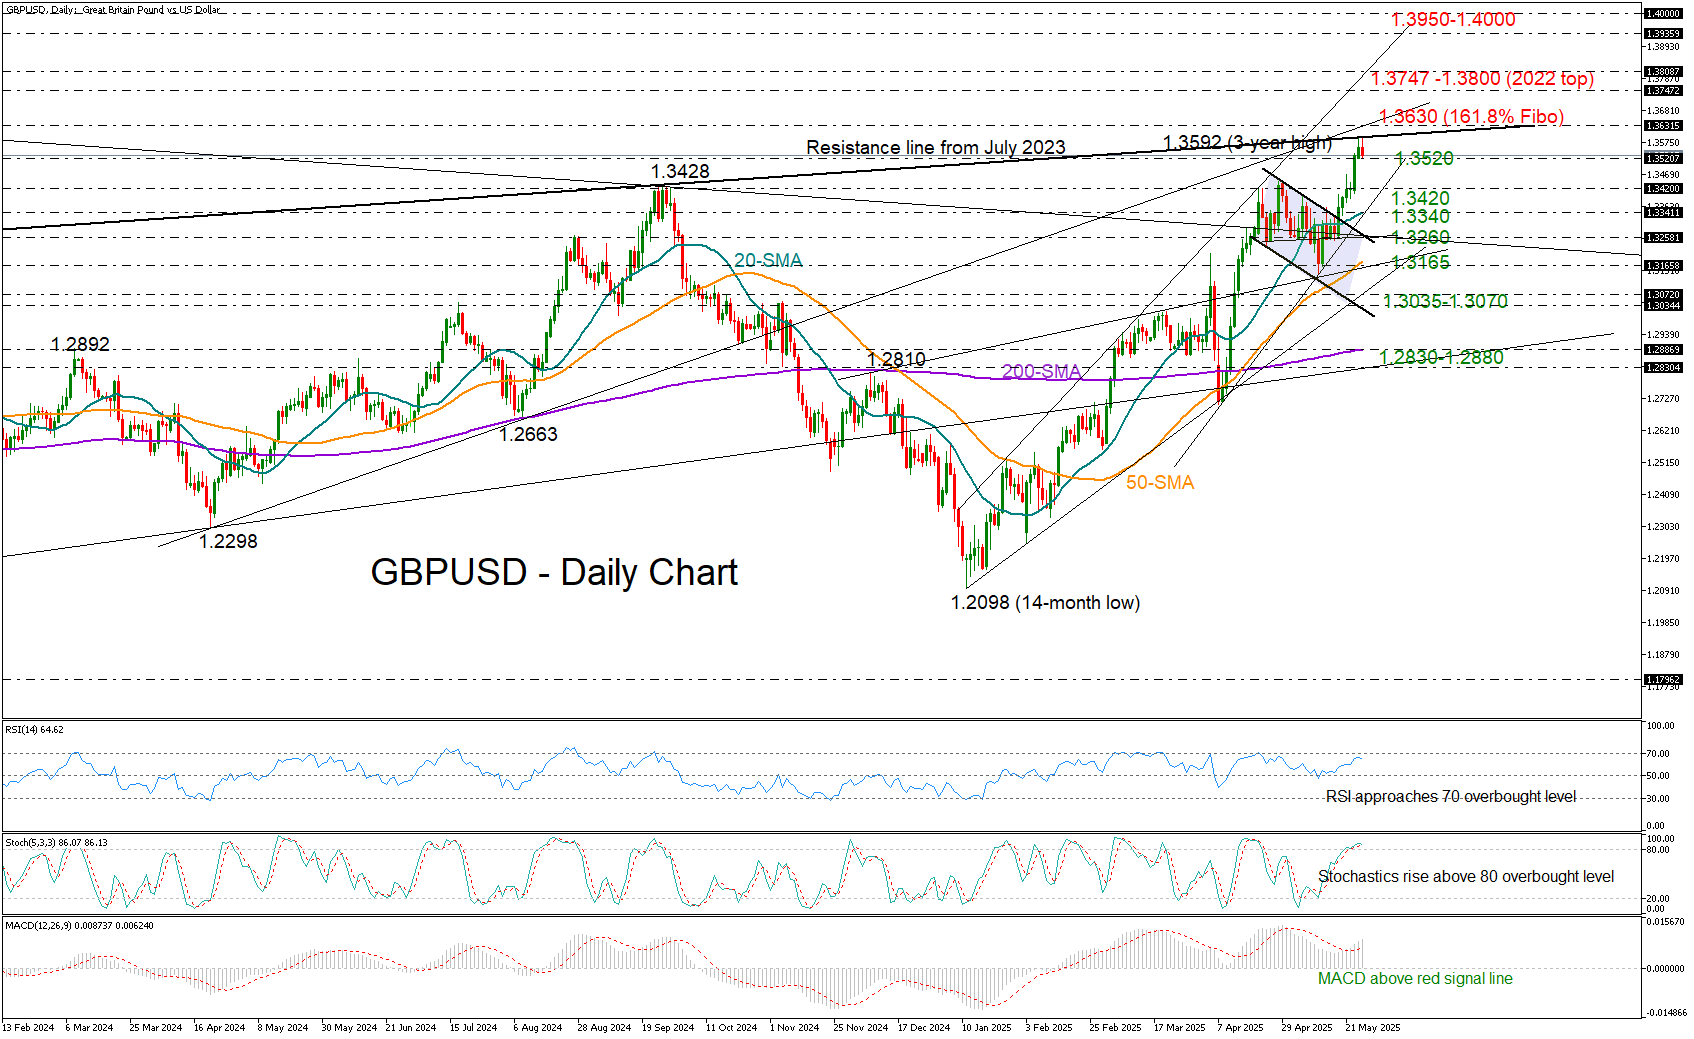
As of mid 2026, the pound has been trading in a broad range against the dollar. The rate has hovered somewhere between 1.22 and 1.29 over the past year. There is no single predictable path. Short term swings of two to three percent are normal. A move of that size on eighty pounds is only a dollar or two, but understanding the pattern matters when you scale up or repeat the conversion. The pound weakened a bit through early 2025 after some dovish signals from the Bank of England. Inflation came down slower than expected in the UK, which kept rates higher for longer. The dollar softened in part because the Federal Reserve began cutting rates. Those two dynamics together pushed the rate upward slightly, landing in the 1.26 to 1.28 zone for much of mid 2025. Nothing dramatic. Just normal macro movement.
What Drives the Rate
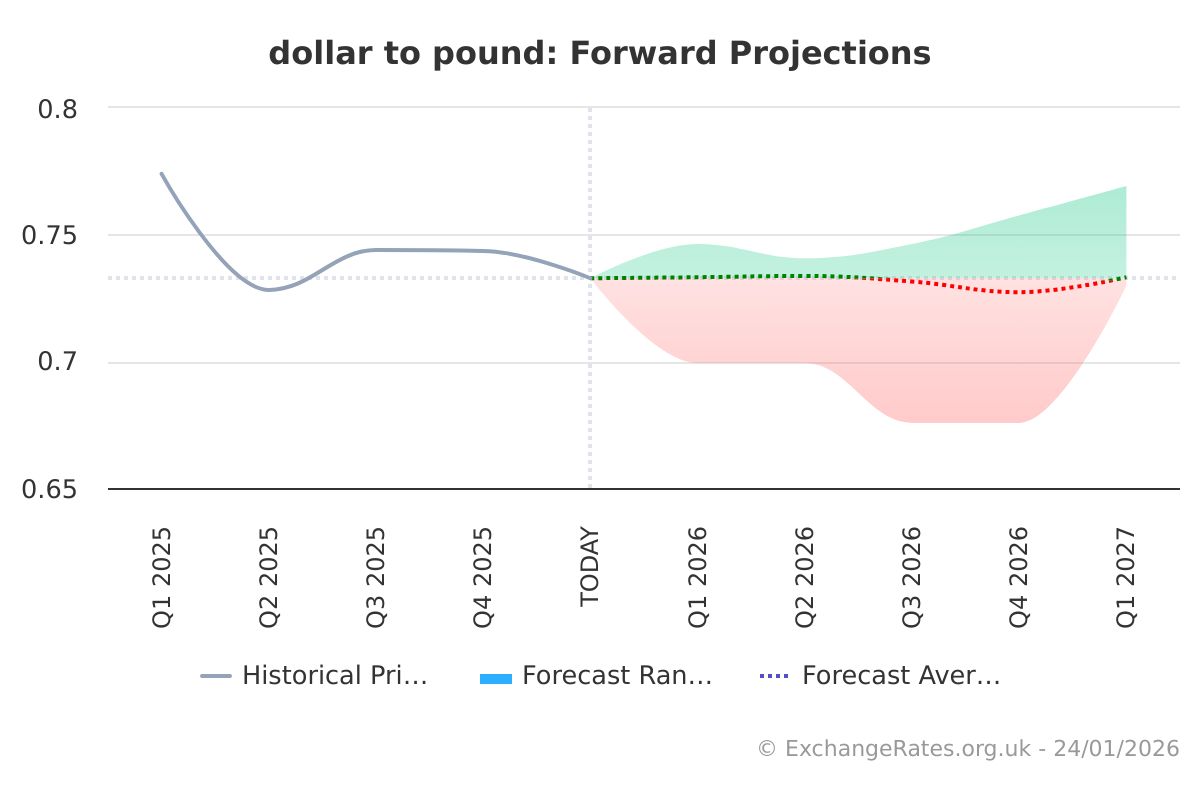
Interest rate spreads are the biggest factor. When the difference between UK and US rates widens, the pound tends to strengthen if UK rates are higher. When the Fed cuts and the BoE holds steady, the dollar weakens relative to the pound. Trade data matters too. A stronger UK export figure generally supports the pound. Political events like elections or budget announcements can cause sharp moves. The market hates uncertainty and reacts quickly. One thing beginners miss is the role of forward markets. Institutions hedge their currency exposure using forwards and options. Those contracts set implicit expectations about where the rate will be in three, six, or twelve months. Watching the forward curve gives you a sense of where professional traders think the rate is heading. It is not a crystal ball, but it is useful context. If the six month forward shows the dollar at 1.24 and the spot rate is 1.27, the market is pricing in a pound decline. That does not mean it will happen. It means the odds favor it slightly.
Get the Full Details

Forecast Scenarios
Forecasting currency rates is unreliable beyond a few months. I will say that plainly. Most models break down after six to twelve months because unexpected events dominate. Geopolitical shifts, surprise inflation readings, or a central bank moving faster than expected can rewrite any forecast overnight. That said, the consensus view among major banks for the next twelve months sits roughly between 1.23 and 1.30. The median point is around 1.265. If you are only converting eighty pounds, the forecast matters less. The range between 1.23 and 1.29 represents about four dollars and forty cents in difference. For a small amount, timing the market precisely is not worth the effort. The cost of trying to time it usually exceeds the benefit. The real value of a forecast is for larger amounts or recurring transfers. Then even a two cent move is worth tracking.
How to Convert 80 Pounds to USD
The process depends on which route you choose. Here is how the common options compare in practice. Bank transfer: Most UK high street banks offer currency conversion. You can buy dollars through your bank app or branch. The rate is convenient but usually includes a margin of two to four percent. If your bank advertises zero fee, check the rate markup. That is where the profit sits. Conversion takes one to two business days for standard transfers. Instant options exist but cost more. Specialist money transfer services: Companies like Wise, Revolut, and OFX charge lower margins. Wise typically offers rates very close to the mid-market rate with a small transparent fee. For eighty pounds, the fee is usually under a dollar. The transfer arrives within hours to one day. This is the option most people should use for small to medium amounts.
Currency exchange bureaus: Physical exchange shops at airports and in city centers offer terrible rates. The margin can exceed five percent. I would avoid this unless you need cash immediately and the amount is trivial. For eighty pounds it might only cost you three or four dollars extra, but it adds up fast if you do it regularly. Card payments: Using a debit or credit card abroad or on a foreign website locks in the rate at the point of sale. Your card provider adds a foreign transaction fee, usually around three percent, plus their own exchange rate. It is convenient but expensive. A card with no foreign transaction fees and a good rate can cut that cost significantly.
A Real Problem I Encountered
During a client project, I hit a specific edge case that took me a while to solve. The client wanted to convert eighty pounds monthly but the funds were held in a British current account that charged high outgoing international transfer fees. Each transfer cost five pounds. That meant ten percent of the amount was eaten before conversion even happened. The effective rate was terrible. The workaround was simple but not obvious at first. We moved the pounds into a multi-currency account that allowed fee free transfers to a Wise account. From there, we converted to dollars and sent to the client's US account. The total cost dropped from about ten dollars per month to less than two dollars. The setup took about twenty minutes and involved closing one account and opening another. It was worth it immediately. For recurring transfers, any solution that cuts fees by half or more is worth the administrative effort.
Pitfalls to Avoid
One common mistake is focusing only on the headline rate. The rate shown on a conversion page might look great, but the total cost includes fees, margins, and possible hidden charges. Always compare the total amount received, not the rate displayed. A rate of 1.27 with a three dollar fee is worse than a rate of 1.26 with no fee on small amounts like eighty pounds. Another issue is locked rate agreements. Some providers let you fix a rate for a future date. This is useful if you expect the rate to move against you. But locking a rate also means you cannot benefit if it moves in your favor. For a one time small conversion, fixing the rate is usually unnecessary complexity. For larger or scheduled amounts, it can protect you from sudden drops. A third pitfall is ignoring the transfer speed. Some cheap services take three to five business days. If you need the dollars by a certain date, the cheapest option might not work. Faster services cost more. It is a trade off between price and timing. For most people, a one to two day window is acceptable and available at low cost.
Actionable Takeaways
For converting eighty pounds to US dollars, use a specialist transfer service with a near mid-market rate. Wise is a reliable choice for most people. Check the total amount you will receive after fees before confirming. If you are doing this monthly, consider setting up a recurring transfer to lock in a routine. Track the rate over time if the amount grows. A two cent movement on eight hundred pounds is two dollars. On eight thousand pounds it is two hundred. If you need cash dollars immediately, a bureau is acceptable for a small amount but expect to pay more. If you have a card with no foreign fees, using it for purchases is simpler than converting and carrying cash. Just be aware of dynamic currency conversion on card machines. Always choose to pay in the local currency so your card provider does the conversion at a better rate.

When the Method Breaks Down
No single service is best in every situation. During periods of high volatility, some providers widen their margins significantly. The rate you see when you start a transfer can change by the time you confirm it. This happens most often around central bank announcements and major economic data releases. If you need certainty, convert during calm periods when markets are stable. Avoid converting on days when the Federal Reserve or Bank of England is releasing decisions. Another scenario where these approaches fail is for very large amounts. If you are converting tens or hundreds of thousands of pounds, the small service fees matter less and you should negotiate with a provider or use a forward contract to lock in a rate. Specialist firms offer better terms at that scale. For eighty pounds, that advice does not apply. Stick to the simple routes.
Bottom Line
Converting eighty pounds to US dollars is not complicated. Pick a low cost provider, check the total you receive, and transfer. Do not overthink it unless the amount is growing or the transfer is recurring. The rate will move. It always moves. Trying to predict every swing is not practical. What matters is avoiding expensive mistakes and using the right tool for the job. The tools are available. The savings come from checking the details before you click confirm.