Section Identifiers and Timing Mechanics
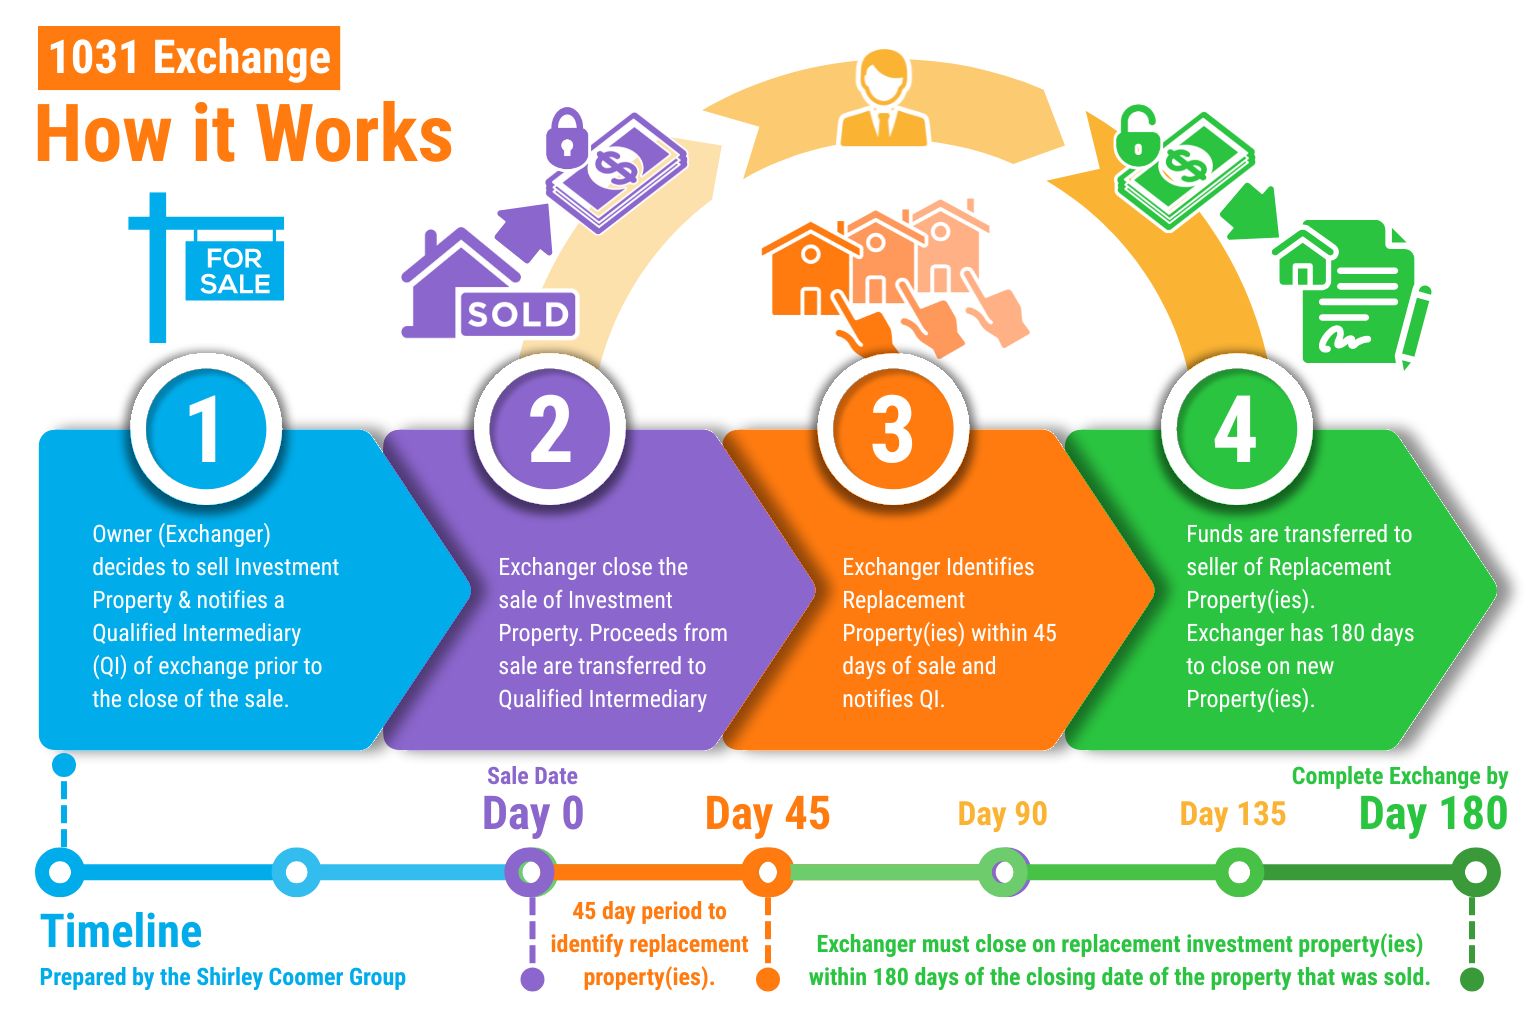
A 1031 exchange lets you defer capital gains taxes when you sell an investment property and reinvest the proceeds into a like-kind replacement. The law is technically Section 1031 of the Internal Revenue Code. It applies to real property held for productive use in a trade or business or for investment. Personal residences don't qualify. Vacation homes usually don't qualify unless you can document genuine rental use. The clock starts the moment you close on the sale of your relinquished property. You have 45 calendar days to identify replacement property and 180 calendar days to close on it. Those deadlines are hard stops. The IRS does not care about weekends or holidays after day one. If your 45th day falls on a Saturday, you still have until midnight that Saturday to submit your identification. Not Monday. Here is where people get tripped up in practice. The 180-day period runs concurrently with the 45-day identification window. It does not start after the 45 days expire. It starts on the same day as the sale closing. I once had a client who thought he had 180 days from the end of the identification period. He did not. He lost his exchange because he waited too long to close on the replacement property. He missed the deadline by eleven days. There is no grace period. No phone call to the IRS fixes this.
The Ultimate Guide To 1031 Exchange Unlocking Tax Benefits For Real Estate Investors
Before you touch any of this, understand the core constraint: the proceeds from your sale cannot touch your hands. If you receive the money, even for twenty-four hours, the entire exchange is disqualified and you owe the taxes immediately. That is why a qualified intermediary exists. The QI holds the funds between transactions. You never see the cash. The QI then releases it to close on the replacement property. Pick your QI carefully. Not all of them are created equal. I have worked with firms that process dozens of exchanges a year and others that treat each one like a novelty. The difference shows up in how they handle edge cases. A thin QI might not know what to do when a title company pushes back on the assignment of contracts. A competent one will have a standard operating procedure for that situation and will have seen it before. Check how long they have been in business. Ask for references from recent clients. Verify they carry errors and omissions insurance. These are basic questions that most people skip.
Identification Rules and the Three Property Limit
You can identify up to three properties regardless of value. This is the three-property rule. It sounds simple but it creates real strategic constraints. If you identify three properties and one of them falls through, you are out of identification slots. You cannot go back and add a fourth. The identification must be in writing, signed by you, and delivered to the QI or the seller of the replacement property before the 45th day expires. Email counts if the recipient can verify it. A text message does not count. A phone call does not count. There is a second identification path called the 200% rule. You can identify more than three properties as long as their aggregate fair market value does not exceed 200% of the value of the relinquished property. This sounds flexible. It is not. I watched a seller try to identify twelve properties under the 200% rule. Nine of them were already under contract with other buyers. Three were zoned for commercial use only. He spent 45 days chasing properties that could not close. He ended up with nothing and owed a tax bill he had planned to defer. The third identification path is the rare property rule. If you identify a property that you already own a substantial interest in, it does not count against your three-property limit. This is niche but useful in certain portfolio restructuring scenarios. Most investors will never need it.
Get the Full Details

Like-Kind Standards and What Actually Qualifies
Like-kind is a broader standard than most people assume. It does not mean identical. It means same nature or character. You can exchange an apartment building for a commercial office building. You can exchange a retail strip center for a multi-family complex. You can exchange vacant land zoned for commercial use for an income-producing commercial building. The common thread is that both properties must be held for investment or productive use in a trade or business. After the Tax Cuts and Jobs Act of 2017, like-kind treatment under Section 1031 is limited to real property only. You can no longer exchange personal property like furniture, equipment, or vehicles for tax deferral purposes. This closed a loophole that some investors exploited. It also eliminated certain strategies that used to be common. If you are reading outdated material online, verify the date. Anything published before late 2017 may contain guidance that no longer applies. Here is a counter-intuitive point that nobody warns you about: a 1031 exchange does not erase your tax liability. It defers it. When you eventually sell the replacement property without doing another exchange, the deferred gain becomes due. The basis carries over. If you plan to hold the property until death, your heirs receive a step-up in basis and the deferred taxes are effectively wiped out. That is a legitimate estate planning consideration. But if you plan to sell the replacement property in five years, you need to budget for the eventual tax hit. Deferral is not exemption.
Reverse Exchanges and Improvement Exchanges
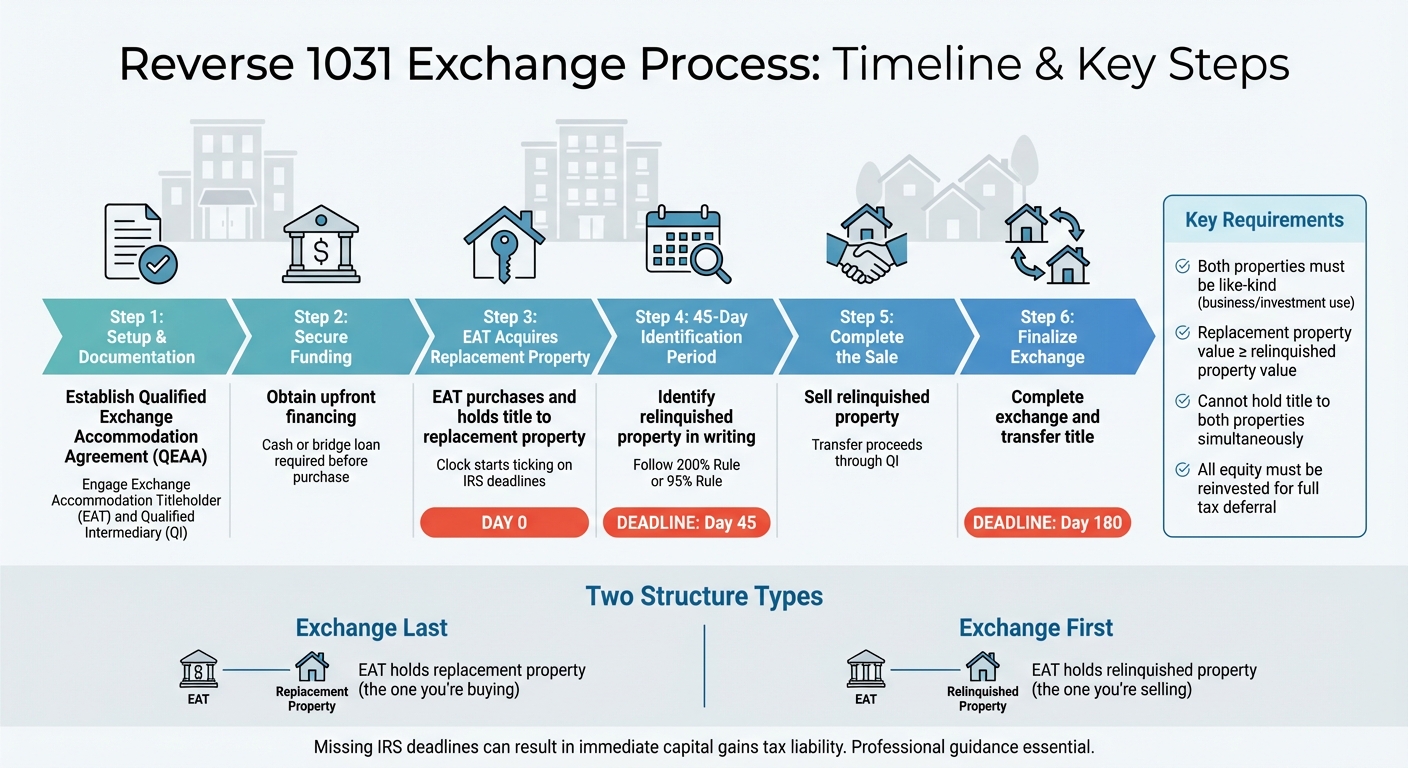
Sometimes you need to buy the replacement property before you sell the relinquished one. A standard forward exchange will not work here. The reverse exchange solves this. A qualified accommodation holder, usually an LLC owned by a trust, acquires the replacement property and holds it until you sell your original property. Then the accommodation holder transfers it to you. The IRS has provided a safe harbor through Revenue Procedure 2000-37. Following it exactly is critical. Deviating from the safe harbor removes your protection. I worked on a reverse exchange where the accommodation holder closed on the replacement property on a Thursday. The title company failed to record the deed properly. The acknowledgment was missing a notary seal. The IRS position would have been that the accommodation holder never validly acquired the property. We caught the error three weeks later. The fix required a corrective deed and a re-execution of the exchange agreement with all parties. It cost approximately eighteen thousand dollars in legal fees and delayed the entire transaction by six weeks. The property values had shifted during that time. The margin on the deal disappeared. This is the kind of risk that does not appear in any summary guide. Improvement exchanges, sometimes called construction exchanges or build-to-suit exchanges, allow you to make improvements or repairs on the replacement property before taking receipt. The exchange funds can be used to pay for those improvements. There is a catch: the improvements must be completed within the 180-day exchange period. Large-scale construction projects frequently exceed that window. If you are considering an improvement exchange, the scope of work must fit inside the timeline or you need a very tight project management setup. I have seen investors budget three months for a kitchen renovation and end up needing eight because of permit delays and material shortages. The exchange timeline does not care about your contractor.
Boot and Partial Exchanges
If you sell a property for two million dollars and buy a replacement property for one point five million, the half million difference is called boot. Boot is taxable. You can also receive cash boot if the QI returns any excess funds to you at closing. Even a small amount of cash boot triggers immediate tax liability on that portion of the gain. The goal is to reinvest all proceeds and acquire replacement property of equal or greater value to achieve full deferral. Another form of boot is relief of debt. If you sell a property with a seven hundred thousand dollar mortgage and buy a replacement property with a four hundred thousand dollar mortgage, the three hundred thousand dollar debt reduction is treated as boot. This is one of the most misunderstood aspects of 1031 exchanges. Investors see a lower mortgage on the replacement property and assume it is fine. It is not fine if you want full deferral. You either need to bring cash to the closing to offset the debt difference or acquire a replacement property with equal or greater debt. Personal property that comes with the sale can also create boot. If your relinquished property includes appliances, furniture, or equipment that transfer to the buyer and you do not acquire equivalent items in the replacement property, the value of those personal items is boot. This matters more than people realize in residential rental exchanges where furnishings are sometimes left behind.
Cost Segregation and Exchange Interaction
Cost segregation studies accelerate depreciation by reclassifying certain components of a building from thirty-nine year straight-line depreciation to five, seven, or fifteen-year categories. This creates larger deductions in the early years. A common question is whether a cost segregation study interacts with a 1031 exchange. It does. When you do a 1031 exchange, the depreciated basis carries over to the replacement property. If you do a cost segregation study on the replacement property, you are building a new depreciation schedule on that carried-over basis. The timing of the study matters. Doing it before closing ensures the accelerated depreciation applies to the correct basis calculation. One thing I learned the hard way: if you attempt a cost segregation study after already closing on the replacement property, the IRS may challenge the study depending on how far into the tax year you are. The rule of thumb is to complete the study before the property is placed in service. That means before you lease it out or before the first tenant moves in. Plan this early. Do not wait until after the exchange closes to think about depreciation strategy.
Common Pitfalls That Kill Exchanges
Documentation errors are the most common failure mode. The identification letter must meet every requirement. Missing signatures, wrong dates, properties not accurately described. One incorrect legal description can invalidate an entire identification. I had a case where a QI filed an identification listing the wrong parcel number for one of three identified properties. The investor thought all three were valid. Two were. The third was not. The IRS would have treated the entire identification as invalid under the default rule if the taxpayer had not separately identified a fourth valid property within the original 45 days. The investor had not. The exchange was partially disqualified. He owed taxes on a portion of the gain that should have been fully deferred. Another frequent mistake is using the wrong type of entity for the exchange. The taxpayer on the relinquished property sale must be the same taxpayer on the replacement property purchase. If you sell in your personal name and try to buy in an LLC, the exchange fails. You can set up an LLC before the exchange and have it acquire the replacement property, but the LLC must be a single-member disregarded entity for tax purposes and the ownership structure must align with your ownership of the relinquished property. Transferring between entities mid-exchange is a minefield. A third pitfall involves related parties. If you sell to a related party, such as a family member or a entity you control, additional rules apply. The related party must hold the property for investment or productive use for at least two years after the exchange. If they sell it sooner, your exchange can be unwound retroactively. This rule exists to prevent circular transactions designed solely to avoid taxes. I have seen investors overlook this because they assumed a brother or sister would hold property indefinitely. Two years is the minimum. There is no exception for good intentions.
When a 1031 Exchange Is Not the Right Move
This strategy has real limitations and it fails in specific scenarios. If you are selling a property with a net loss, a 1031 exchange is pointless. You cannot deduct a realized loss through an exchange. You should just sell and claim the loss. If the replacement property market is tight and you cannot find suitable like-kind property within 180 days, the exchange collapses and you owe taxes. If you need liquidity from the sale and the exchange structure prevents you from accessing those funds, the tax deferral may not be worth the constraint. If you are near retirement and plan to move into a primary residence, Section 121 exclusions up to two hundred fifty thousand dollars for singles or five hundred thousand for married couples may provide better tax relief than a 1031 exchange, especially if you do not plan to continue investing in rental real estate. The administrative burden is real. A well-run exchange takes approximately two to three weeks of active work from the seller including document review, identification drafting, coordination with title companies, and follow-up with the QI. The total elapsed time from listing to replacement property closing typically spans four to six months minimum. If you value speed and simplicity over tax deferral, a straight sale may serve you better.

Practical Next Steps
Start by running the numbers on your specific situation. Calculate the estimated deferred gain based on your current property basis, sale price, and expected replacement property cost. Compare that against the cost of the exchange including QI fees, legal fees, and any title or escrow adjustments. A typical exchange costs between fifteen hundred and five thousand dollars depending on complexity. Factor in the opportunity cost of tying up capital in a replacement property rather than taking liquidity. Assemble your team before you list the property. That means a qualified intermediary, a real estate attorney familiar with 1031 exchanges, and a CPA who understands deferred gain calculations. Having these people in place before you sign a listing agreement gives you options if a suitable replacement property appears quickly. Waiting until after you accept an offer is too late. You will spend your first forty-five days scrambling instead of evaluating actual investment opportunities. Keep a dedicated folder for every exchange document. Identification letters, QI agreements, assignment documents, closing statements. Store them digitally and physically. The IRS can audit an exchange up to the statute of limitations which is generally three years from the filing date of the tax return reporting the exchange. If you do cost segregation or other basis adjustments, keep those records indefinitely because they affect your basis in the replacement property for future sales.


