Black-Scholes isn't a magic key. It's a model with real teeth.
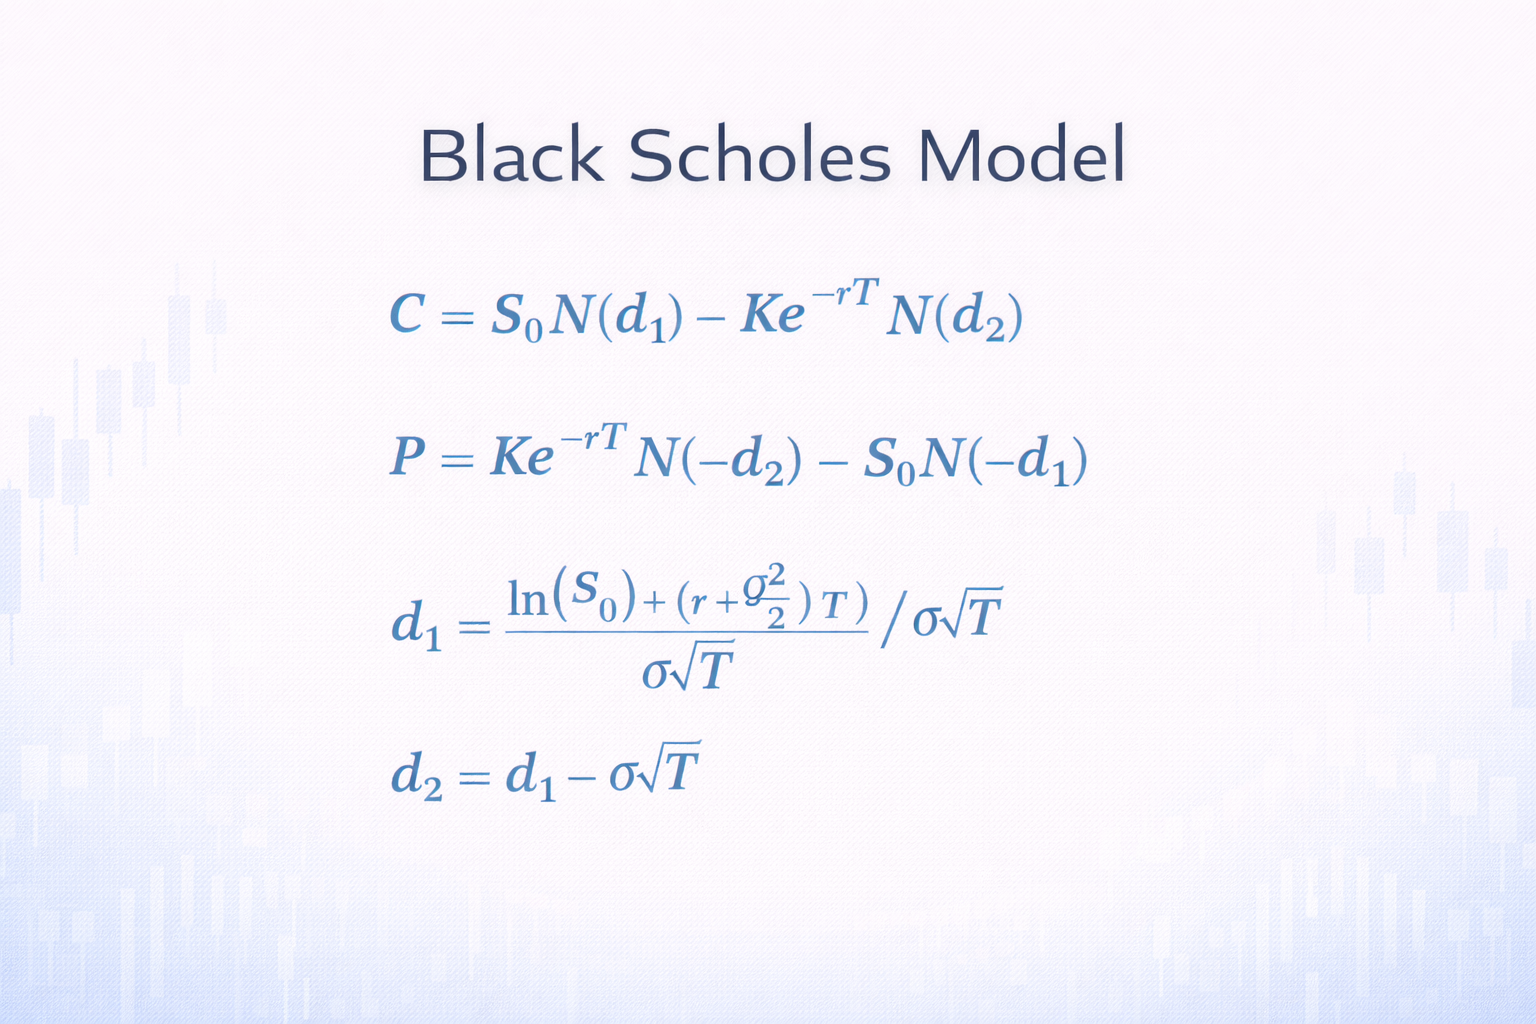
Most people come to this equation thinking it's some ultimate code to unlock markets. It's not. It's a tool for pricing European-style options under a specific set of assumptions. When you understand what those assumptions actually mean in practice, the model becomes useful. When you don't, you'll lose money on it. The formula itself is: C = S × N(d1) K × e^(rT) × N(d2)
Where d1 = [ln(S/K) + (r + ²/2) × T] / ( × T) and d2 = d1 × T S is the current asset price. K is the strike. r is the risk-free rate. T is time to expiration. is implied volatility. N() is the cumulative normal distribution. That's it on the surface. The actual work starts when you try to use this on real data. Here's what I learned the hard way. In 2019, I was pricing a custom variance swap structure for a client who needed a hedge on a narrow earnings event. The implied vol surface was anything but flat. Black-Scholes assumes constant volatility across strikes and maturities. My inputs came from the market, but the model spat out prices that were off by 4% on the wings. A 4% error sounds small until you're dealing with notional sizes in the hundreds of millions. The workaround was to blend the Black-Scholes framework with a local volatility interpolation using the Dupire formula, which essentially lets you feed in the entire vol surface and get strike-dependent vols out the other side. It took about three extra hours of setup but eliminated the pricing gap.
How the components actually behave in practice
Volatility is the variable that breaks people. Everyone knows it matters, but most treat it like a single input you pull from a screen. In reality, implied volatility is a function of both strike and expiration. That's the volatility smile, or more accurately these days, the skews and term structure layered on top of each other. A 30-day option on an index will have a completely different implied vol than a 90-day option, even on the same strike. Black-Scholes doesn't account for that internally. You have to do it yourself by picking the right sigma for your contract. Time decay is another thing the model handles elegantly on paper but trips people up in execution. Theta isn't linear. An option loses time value faster as expiration approaches, and the acceleration is nonlinear. I've seen junior traders calculate theta using the model output for T=0.25 and apply it month-over-month. That's wrong. The actual decay curve is steeper near expiry, especially for at-the-money options. If you're managing a portfolio of short-dated options, you need to recalculate the Greeks frequently, not just once per period. The risk-free rate assumption is where things get quietly dangerous. Black-Scholes assumes a known, constant risk-free rate over the life of the option. In normal markets, you'd use a Treasury yield matching the option's maturity. But during stressed periods, the spread between what you can borrow and what Treasuries pay widens dramatically. I ran into this during the March 2020 crash. The model gave clean numbers, but the actual cost of carry for the hedge was nowhere near the risk-free rate the equation assumed. The fix was to adjust r upward to reflect the actual funding cost of the underlying position, not the theoretical Treasury rate. This isn't standard textbook practice. It's what you do when you need the model to match reality.
Get the Full Details
Common mistakes that cost real money
Using ATM implied vol for OTM options. The model will give you a price, but it'll be wrong. Option prices away from the money are more sensitive to volatility skews than the model accounts for. If you're pricing OTM puts for hedging purposes, you need to use the implied vol at that specific strike, not the ATM reference point. The difference compounds quickly across multiple legs. Ignoring dividends. The basic formula assumes a non-dividend-paying stock. For stocks that pay meaningful dividends, you need to adjust S downward by the present value of expected dividends. I had a situation where a client was pricing LEAPS on a high-dividend name and completely missed this adjustment. The model was underpricing the call by roughly 6%. Not trivial on a large position. Applying it to American options. Black-Scholes prices European options only. American options can be exercised early, which changes the math entirely, especially for deep ITM calls on dividend-paying stocks where early exercise can be optimal. You need a different model, like binomial trees or Finite Element methods, for accurate American option pricing. I've seen people run Black-Scholes on American options and then manually adjust, which is a patch at best and unreliable at worst.
What the model actually gives you and what it doesn't
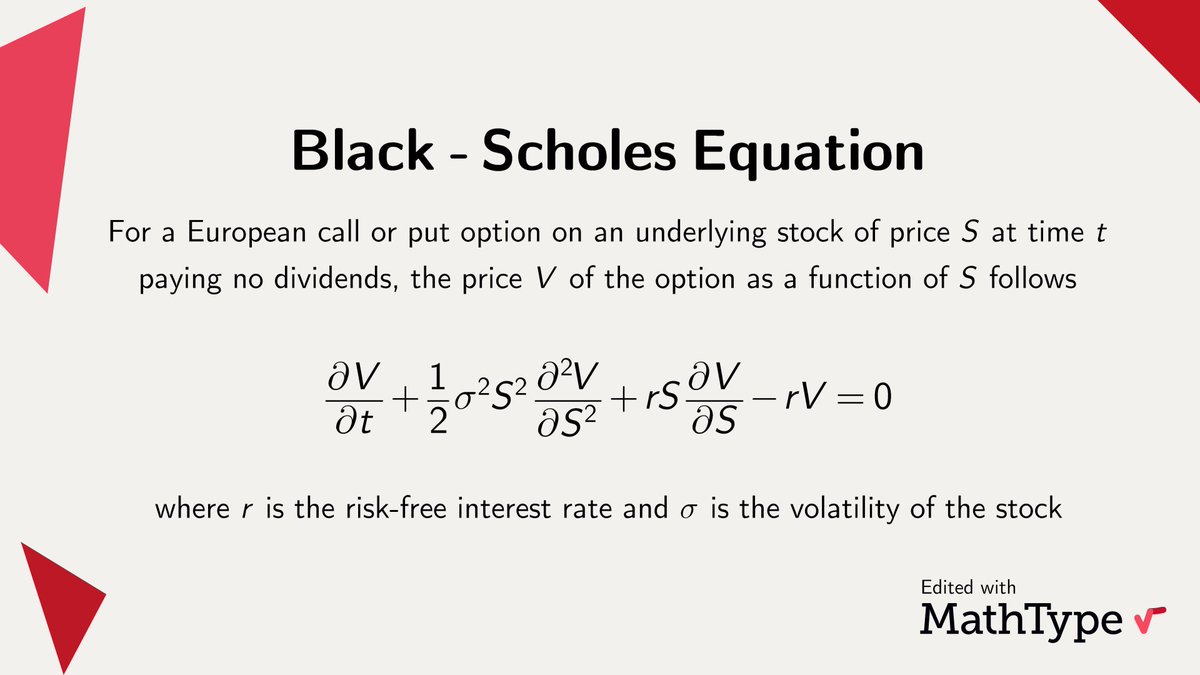
Black-Scholes gives you a theoretical fair value assuming the model's conditions hold. It gives you Greeks, which are tools for measuring sensitivity, not predictions. Delta, gamma, vega, theta, rho — these are partial derivatives, not guarantees. They tell you how the price moves for small changes in underlying parameters. Large moves break the linear approximations. The model doesn't tell you whether an option is overpriced or underpriced relative to what the market thinks. That requires comparing the model price to the market price and understanding why the difference exists. Is it liquidity? Skew? Expected event risk? The gap between model price and market price is where the actual edge lives, not in the formula itself.
Getting started without blowing up your account
Set up a spreadsheet or use Python with the scipy.stats.norm library. The calculation takes about two minutes once you have the inputs. Validate your numbers against a known benchmark, like CBOE option data, before trusting the model for anything real. I spent weeks building pricing scripts in college that looked correct until I compared them against actual traded prices. The errors were small but consistent, usually from a rounding issue in the log calculation or mixing up continuous versus discrete compounding for the risk-free rate. Start with simple scenarios. Price a single European call on a non-dividend-paying stock. Then layer in complexity one variable at a time. Add dividends. Add different strikes. Add shorter time horizons. Each change teaches you something about where the model bends. When you move to portfolio-level work, realize that the model's biggest weakness is its assumption of log-normal returns. Real markets have fat tails. Crash events happen more often than the model predicts. I had a period where a portfolio of short gamma positions looked perfectly hedged according to Black-Scholes and then lost money because the underlying moved in a way that no single Greek calculation could capture. The model assumes constant volatility and continuous trading. Neither is true in practice. You hedge between rebalancing windows. Volatility changes when you're not looking. These gaps don't show up in any formula.
The practical takeaway is that Black-Scholes is a starting point, not a destination. It gives you a framework for thinking about option pricing and risk. But the actual work is in understanding where the assumptions fail and adjusting accordingly. I still use it daily, but I always pair it with empirical checks against live market data before making any pricing decision. The model won't ruin you. Blind faith in it will.