Where to Actually Find 990s and What the Pages Mean
The IRS doesn't make this easy on purpose. If you want a nonprofit's Form 990, your first stop should be the ProPublica Nonprofit Explorer or the IRS Tax Exempt Organization Search. Both are free. ProPublica is generally faster for quick lookups, while the IRS database has the actual PDFs scanned from paper filings for older returns. I've spent more afternoons than I'd like to admit bouncing between the two because one will have a form the other doesn't. Most people who ask me about this just want to know if a charity is legit. Digging into their 990 is actually the quickest way to find out. The form tells you who runs the organization, where the money goes, and whether any insiders are pocketing it. Here's how I decode them without losing my mind.
The Ultimate 990 Finder Guide Decode Nonprofit Tax Forms Unlock Financial Secrets
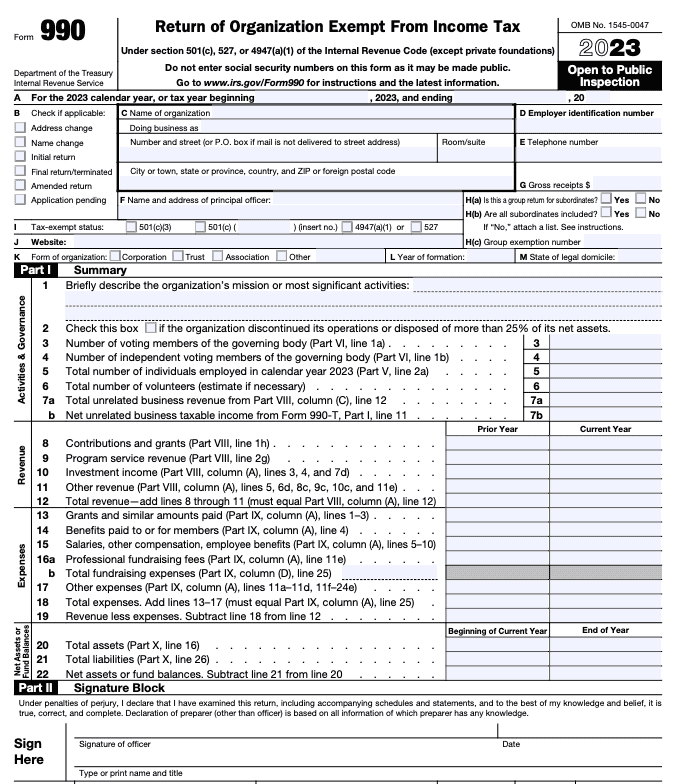
I wrote this because every time someone asked me how to read a 990, I'd send them three different links and no real guidance. The forms themselves are 44 pages long for larger organizations, and half of it is instructions that don't apply to you. I needed a practical way through it, so I built a system over the last few years that cuts the reading time down to about twenty minutes for a standard Form 990. Start with Part VII. That's where compensation lives. Look at the top ten paid employees and contractors. If the executive director makes three times what the average staffer makes, that's worth noting. If the board chair is also listed as a key employee receiving compensation, flag it. That's a related-party transaction that should have been reviewed by an independent committee. Part VIII is the functional statement, which is the nonprofit version of a income statement. Revenue on top, expenses below. The trick most people miss is that Program Service Revenue on line 12 is often tiny. Most nonprofits don't make money from their actual mission. They make it from grants, donations, and government contracts. If a charity claims to provide Meals to Homebound Seniors and its largest revenue source is a $2 million federal contract, that's not a scandal, but it changes how you evaluate their independence and risk profile.
Here's something nobody tells you about Form 990, Part X, the balance sheet. Nonprofits can classify assets in ways that make them look healthier or weaker than they actually are. A $500,000 endowment might be split between temporarily restricted and permanently restricted. Temporarily restricted means someone somewhere put conditions on when that money can be spent. Permanently restricted means it's locked up indefinitely. Reading the fine print on Schedule B, the contributions schedule, will tell you who's actually funding the org. If eighty percent comes from two foundations, the organization has concentration risk that isn't obvious from the face of the form. I ran into a specific problem last year while researching a regional arts nonprofit. Their Form 990 showed total revenue of about $1.8 million and program expenses of $1.4 million. On paper, that looked solid. But when I dug into Schedule G, the supplementary information for grants and contributions, I found that $900,000 of that revenue came from a single government arts council grant that was up for renewal that fiscal year. The board minutes, which I pulled separately through a public records request, showed that the council had already flagged the organization for underperforming on their deliverable metrics. The 990 itself didn't mention this anywhere. It was buried in footnotes and supporting documents that most people never check. That grant renewal got denied six months later. The organization folded within a year. The form looked fine because it was looking backward at what had already happened. This is why reading just the summary pages isn't enough. The real story is in the attachments. Schedule G, Schedule J for compensation, and Part IX for the statement of functional expenses. The functional expense breakdown shows how much went to programs versus management versus fundraising. The rule of thumb you'll see everywhere is that above 75 percent to programs is good. Below 50 percent is a red flag. But that rule breaks down for small nonprofits where the overhead of running the organization eats a larger share. A 501(c)(3) making under $500,000 in revenue will naturally have higher administrative percentages because they can't spread fixed costs across a large budget. Don't punish them for it. Look at the absolute dollar amounts instead.
Get the Full Details
Another counter-intuitive thing: a low fundraising ratio doesn't always mean a healthy organization. Some charities deliberately keep their fundraising expenses minimal because they rely on institutional donors who don't want to see high overhead. That's fine strategy, but it also means you're not seeing the full cost of acquiring those donors. The form will show you what they chose to report, not what it actually costs to bring in new money. When you're using any 990 finder tool, the biggest limitation is that forms are filed on a delay. Newer organizations should file by the 15th of the fifth month after their fiscal year ends. For calendar-year filers, that's May 15. But the IRS processes filings in batches, and ProPublica updates their database on a rolling basis. You might be looking at a form that's six to eighteen months old depending on the organization's size and filing history. If someone is asking you for due diligence on a current decision, that lag matters. An organization could have gotten slapped with an Revocation notice from the IRS or filed for bankruptcy since their last submission, and the public record won't reflect it until they file their next 990 or respond to a public records request. If you need real-time financial data on a nonprofit, the 990 alone won't give it to you. You'd need audited financial statements, which some larger organizations publish on their own websites. Look for a link labeled Financials or Annual Report in the footer. Those documents go back further and include notes that the IRS form strips out. The 990 is a tax document. The audit is an accountability document. They often tell different stories.
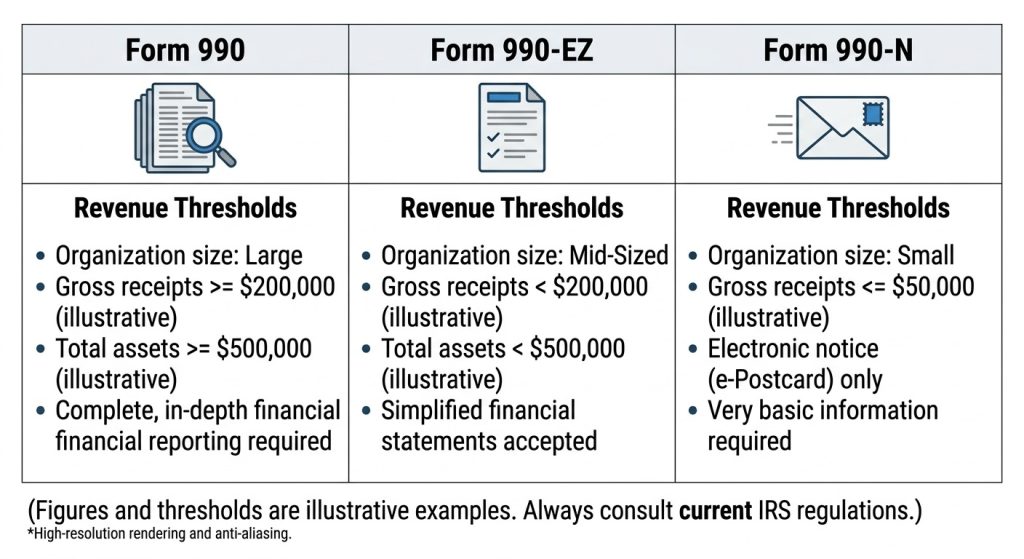
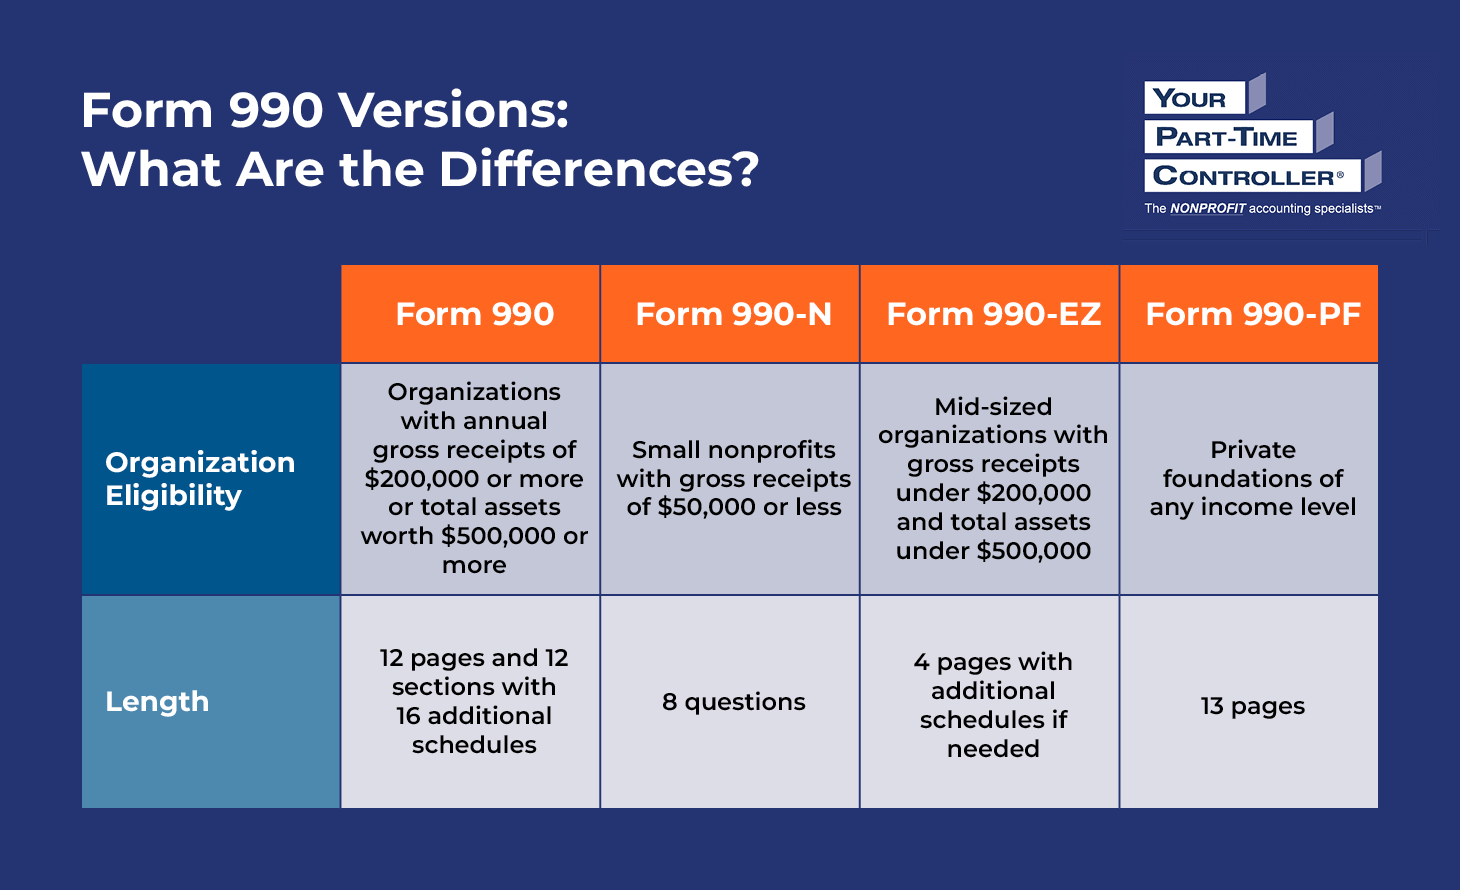
For smaller orgs that don't audited, there's nothing. Their 990-N, the electronic notice for gross receipts under $50,000, is just a postcard. It has no financial detail. If an organization claims to be a charity and their most recent filing is a 990-N, that's technically legal but it means you're flying blind. I've seen donors hand over five-figure gifts to organizations that couldn't produce a single line item showing where the money went the year before. The tools I recommend are straightforward. ProPublica Nonprofit Explorer for quick searches and PDF downloads. GuideStar, now part of Candid, if you need deeper historical data and ratings. The IRS Exempt Organizations Select Check tool if you just want to confirm filing status and tax-exempt classification. None of these cost anything. GuideStar does push you toward paid subscriptions, but the free tier covers most basic research. I've never paid for it. One practical tip that saves time: use the search filter for organizations that file Form 990, not 990-EZ or 990-N. The EZ version is a simplified filing for organizations with under $200,000 in revenue and under $500,000 in assets. It has far fewer schedules and less detail. If you're doing serious research, skip the EZ results and look for the full form. The N is useless for analysis. Filtering your search saves you from wading through incomplete data.
Understanding these forms takes practice. The first time I read a 990 it took me three hours. Now I can get through a standard one in twenty minutes because I know exactly which lines matter and which are noise. The structure never changes, so once you've done it a dozen times, your brain starts skipping ahead. That's when you miss things though. I still make mistakes. Last quarter I almost missed a related-party lease because I was skimming Part XIII and didn't catch that the organization was paying rent to a foundation whose board included the executive director's spouse. It was in the footnotes of Schedule L. I caught it on the third pass. That's the reality of decoding nonprofit tax forms. It's tedious, it's complete, and it's the best public data you have on how these organizations actually operate. No amount of marketing or mission statements replaces looking at where the money went.