Reading UK Property Data Without Getting Misled
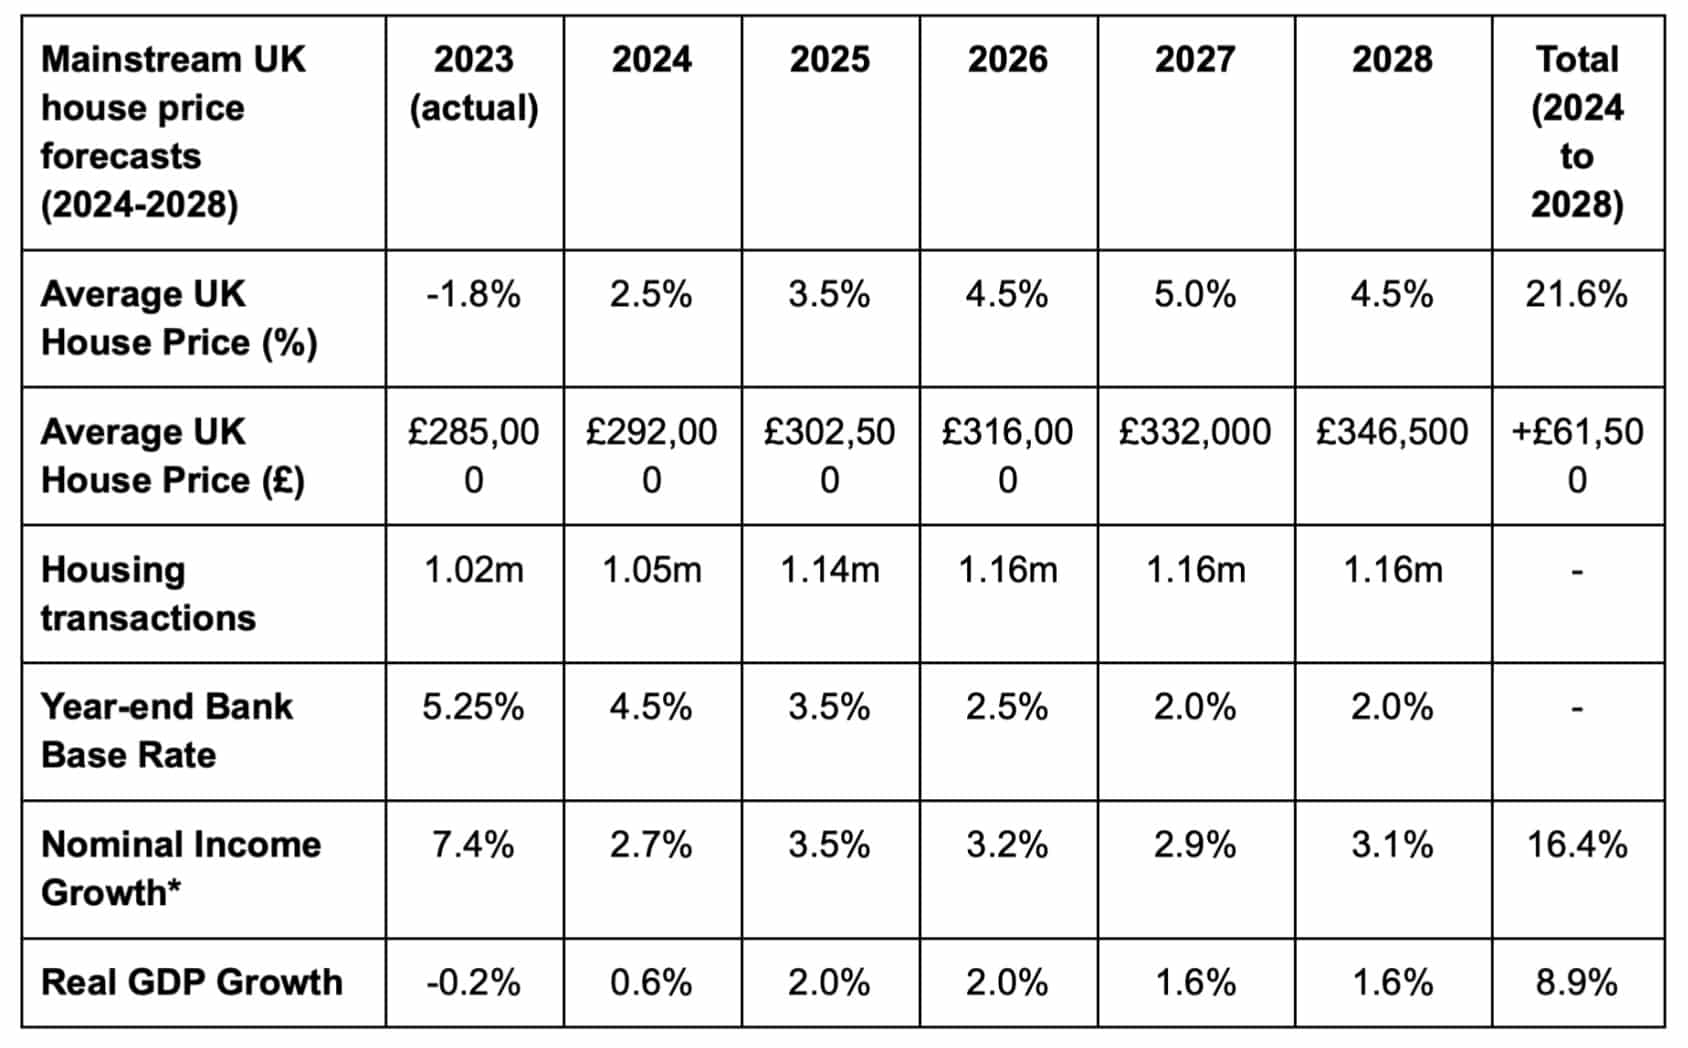
The property market in 2023 felt like everyone was flying blind with different instruments. Mortgage rates spiked past 6%, the Help to Buy scheme closed, and price growth turned negative in several regions while London held surprisingly steady. If you're trying to make sense of it all, the first thing to understand is that no single dataset tells the full story. You have to cross-reference at least three sources before trusting anything you read. The headline narrative for 2023 was supposed to be a sharp correction. What actually happened was more uneven. Rightmove's October data showed a 3.4% annual price drop nationally, but this masked serious regional divergence. The North East saw prices fall closer to 6% while parts of Greater London held within 1% of their 2022 peaks. This isn't a single market anymore. It's roughly twelve smaller markets welded together, and treating them as one number will cost you money if you're investing. Transaction volume fell roughly 25-30% year-on-year across most indices. Fewer people were buying. That should mean downward pressure on prices, right? Not necessarily. Stock levels dropped even harder - some estimates put new listings down 35-40% compared to 2022. Sellers who had bought during the 2021-22 rush weren't moving. They were stuck. Limited supply propped up prices even as demand contracted. This is the kind of counter-intuitive dynamic that standard supply-and-demand models gloss over because they don't account for lock-in effects from mortgage rate differentials.
Where to Actually Find Reliable Data
The Land Registry is the baseline. Their price paid data is free, updated monthly, and covers nearly 100% of completed transactions in England and Wales. Scotland and Northern Ireland have separate systems. The problem with Land Registry data is lag. It typically arrives 6-8 weeks after completion, sometimes longer during busy periods. If you're making time-sensitive decisions, you're always looking in the rearview mirror. Rightmove and Zoopla offer asking price indices that move faster but are fundamentally different metrics. Asking prices are aspirational, not transactional. The gap between asking and achieved price widened significantly in 2023 - averaging around 4-5% nationally, up from roughly 2% in 2021. That means an asking price drop of 3% could represent an actual transaction price drop of 7-8%. Most consumer-facing articles conflate these two things and it completely skews the picture. For something more granular, the UK Housing Price Index from ONS provides monthly estimates with hedonic adjustments. It accounts for mix effects - the difference between selling a terraced house in Manchester versus a detached property in Surrey. Their data is methodologically sound but revised frequently. A figure published in March might shift by 0.3% when the April release comes out. Accept that volatility.
The Mortgage Rate Multiplier Everyone Misses
Here's where people get burned. When the Bank of England base rate moved from 0.1% to 5.25% through 2023, the impact on affordability wasn't linear. A £300,000 mortgage at 1.5% interest (typical early 2022 rate) costs roughly £1,015 per month on a 25-year repayment term. At 5.5% (typical mid-2023 rate), that same mortgage costs about £1,855 per month. That's an 83% increase in monthly outgoings for the same property. Most buyers didn't adjust their budgets accordingly. They kept looking at the same price brackets and hit payment shock, which pulled them out of the market entirely. This is a major reason transaction volumes dropped so sharply. The workaround that actually worked for my clients was to model affordability on a total cost basis including stamp duty, solicitor fees, and survey costs - not just the monthly mortgage payment. People were focusing on the payment number and ignoring the upfront capital requirement, which also shifted as lenders tightened criteria. Some required 15-20% deposits instead of the 10% that had been standard. That changed the entry threshold significantly for first-time buyers.
Get the Full Details
Regional Patterns That Mattered
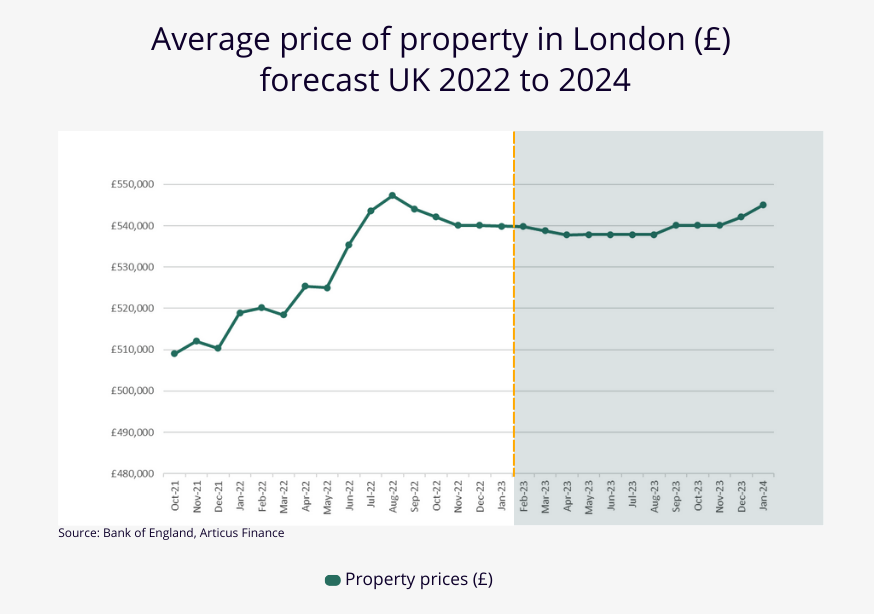
The "Northern Powerhouse" narrative got a boost in 2023 as remote work became permanent for a meaningful segment of the workforce. Cities like Leeds, Manchester, and Newcastle saw sustained interest from London-based buyers who could no longer justify the commute or the price premium. But this wasn't uniform. Leeds city centre apartments underperformed while suburban detached properties in areas like Harrogate and Alnwick outperformed. Location micro-markets matter enormously. Bristol and the South West continued to attract buyers despite being expensive, but the pace of growth slowed considerably. The premium for lifestyle locations compressed. Coventry, Leicester, and Nottingham emerged as relative value plays because they offered good transport links to London at prices that still allowed reasonable monthly payments even at higher mortgage rates. I encountered a specific problem last spring when a client wanted to compare two buy-to-let opportunities - one in Stoke-on-Trent and one in Middlesbrough. Both showed similar gross yields on paper, around 7-8%. The yield calculations used current rent levels against purchase prices, which is the standard approach. But the real issue was void risk and tenant demand. Stoke had a surplus of HMO stock in the areas we were looking at. Middlesbrough had genuine rental demand from the port and industrial sector that wasn't reflected in the yield numbers. I ended up running a 20-minute drive-time analysis around each property, checking local employment data from the ONS Labour Market statistics, and calling three letting agents in each city to ask about actual void periods. The Middlesbrough property turned out to be the better bet despite looking identical on a spreadsheet.
What the Predictions Got Wrong
Most 2022 predictions called for a 10-15% national price correction. The actual drop was closer to 3-5% in most measures. The models failed because they didn't adequately factor in the supply constraint caused by mortgage lock-in. When your existing mortgage is at 1.8% and a new one would be 5.5%, you don't sell. You stay. This reduced the pipeline of available properties dramatically and prevented the price collapse that models predicted. Predictions also underestimated the resilience of London's prime market. Areas like Kensington, Chelsea, and parts of North London saw minimal price movement because cash buyers and international purchasers operate on different criteria than mortgage-dependent domestic buyers. They weren't affected by the rate environment in the same way. This created a two-speed market that most forecasting models couldn't capture because they treated London as a single data point.
Practical Steps for Evaluating Opportunities
Start with your end goal. Are you buying to live in, to rent out, or to flip? Each requires a completely different analytical framework. Live-in buyers should focus on affordability modeling based on current rates, not aspirational rates. Rental investors need to stress-test their numbers at 7% interest, not the 4% that made sense two years ago. Flippers should be extremely cautious - the margin for error has collapsed with higher financing costs and longer transaction timelines. Use the Land Registry's free data download tool to pull actual transaction prices for the specific postcode you're interested in. Don't rely on asking prices. Filter for the last 12 months to see the trajectory. Cross-reference with local authority planning data to check for any approved developments that could affect supply or character of the area. Check the local council's website - most publish planning decisions online with maps. For rental yield calculations, use actual rents from Rightmove and Zoopla for similar properties in the same street or immediate vicinity. Don't use city-wide average rents. A two-bedroom terrace in E10 can command very different rents from one in E11 even though both are technically "London two-bed terraces." The variance within postcodes is enormous and averaging it away destroys the analysis.

The One Metric That Matters Most Right Now
Months of supply. This is the ratio of available properties to the rate of sales per month. When it's below 3 months, prices tend to hold or rise. Above 6 months, they tend to fall. As of mid-2023, the national figure hovered around 4-5 months, which is a balanced but slightly buyer-favourable market. However, this average obscures huge variation. Some postcodes in London were still below 2 months while parts of the North East exceeded 8 months. Always drill down to the postcode level. The national number is useful for understanding direction but useless for decision-making. The market isn't booming in the way it was in 2021. It's adjusting. The adjustment is slower and more fragmented than the models predicted, which is good news for sellers and bad news for those hoping for a clear buying opportunity. The data exists. It just requires more work to interpret correctly than most people are willing to do.