Understanding Military Compensation: What Actually Hits Your Bank Account
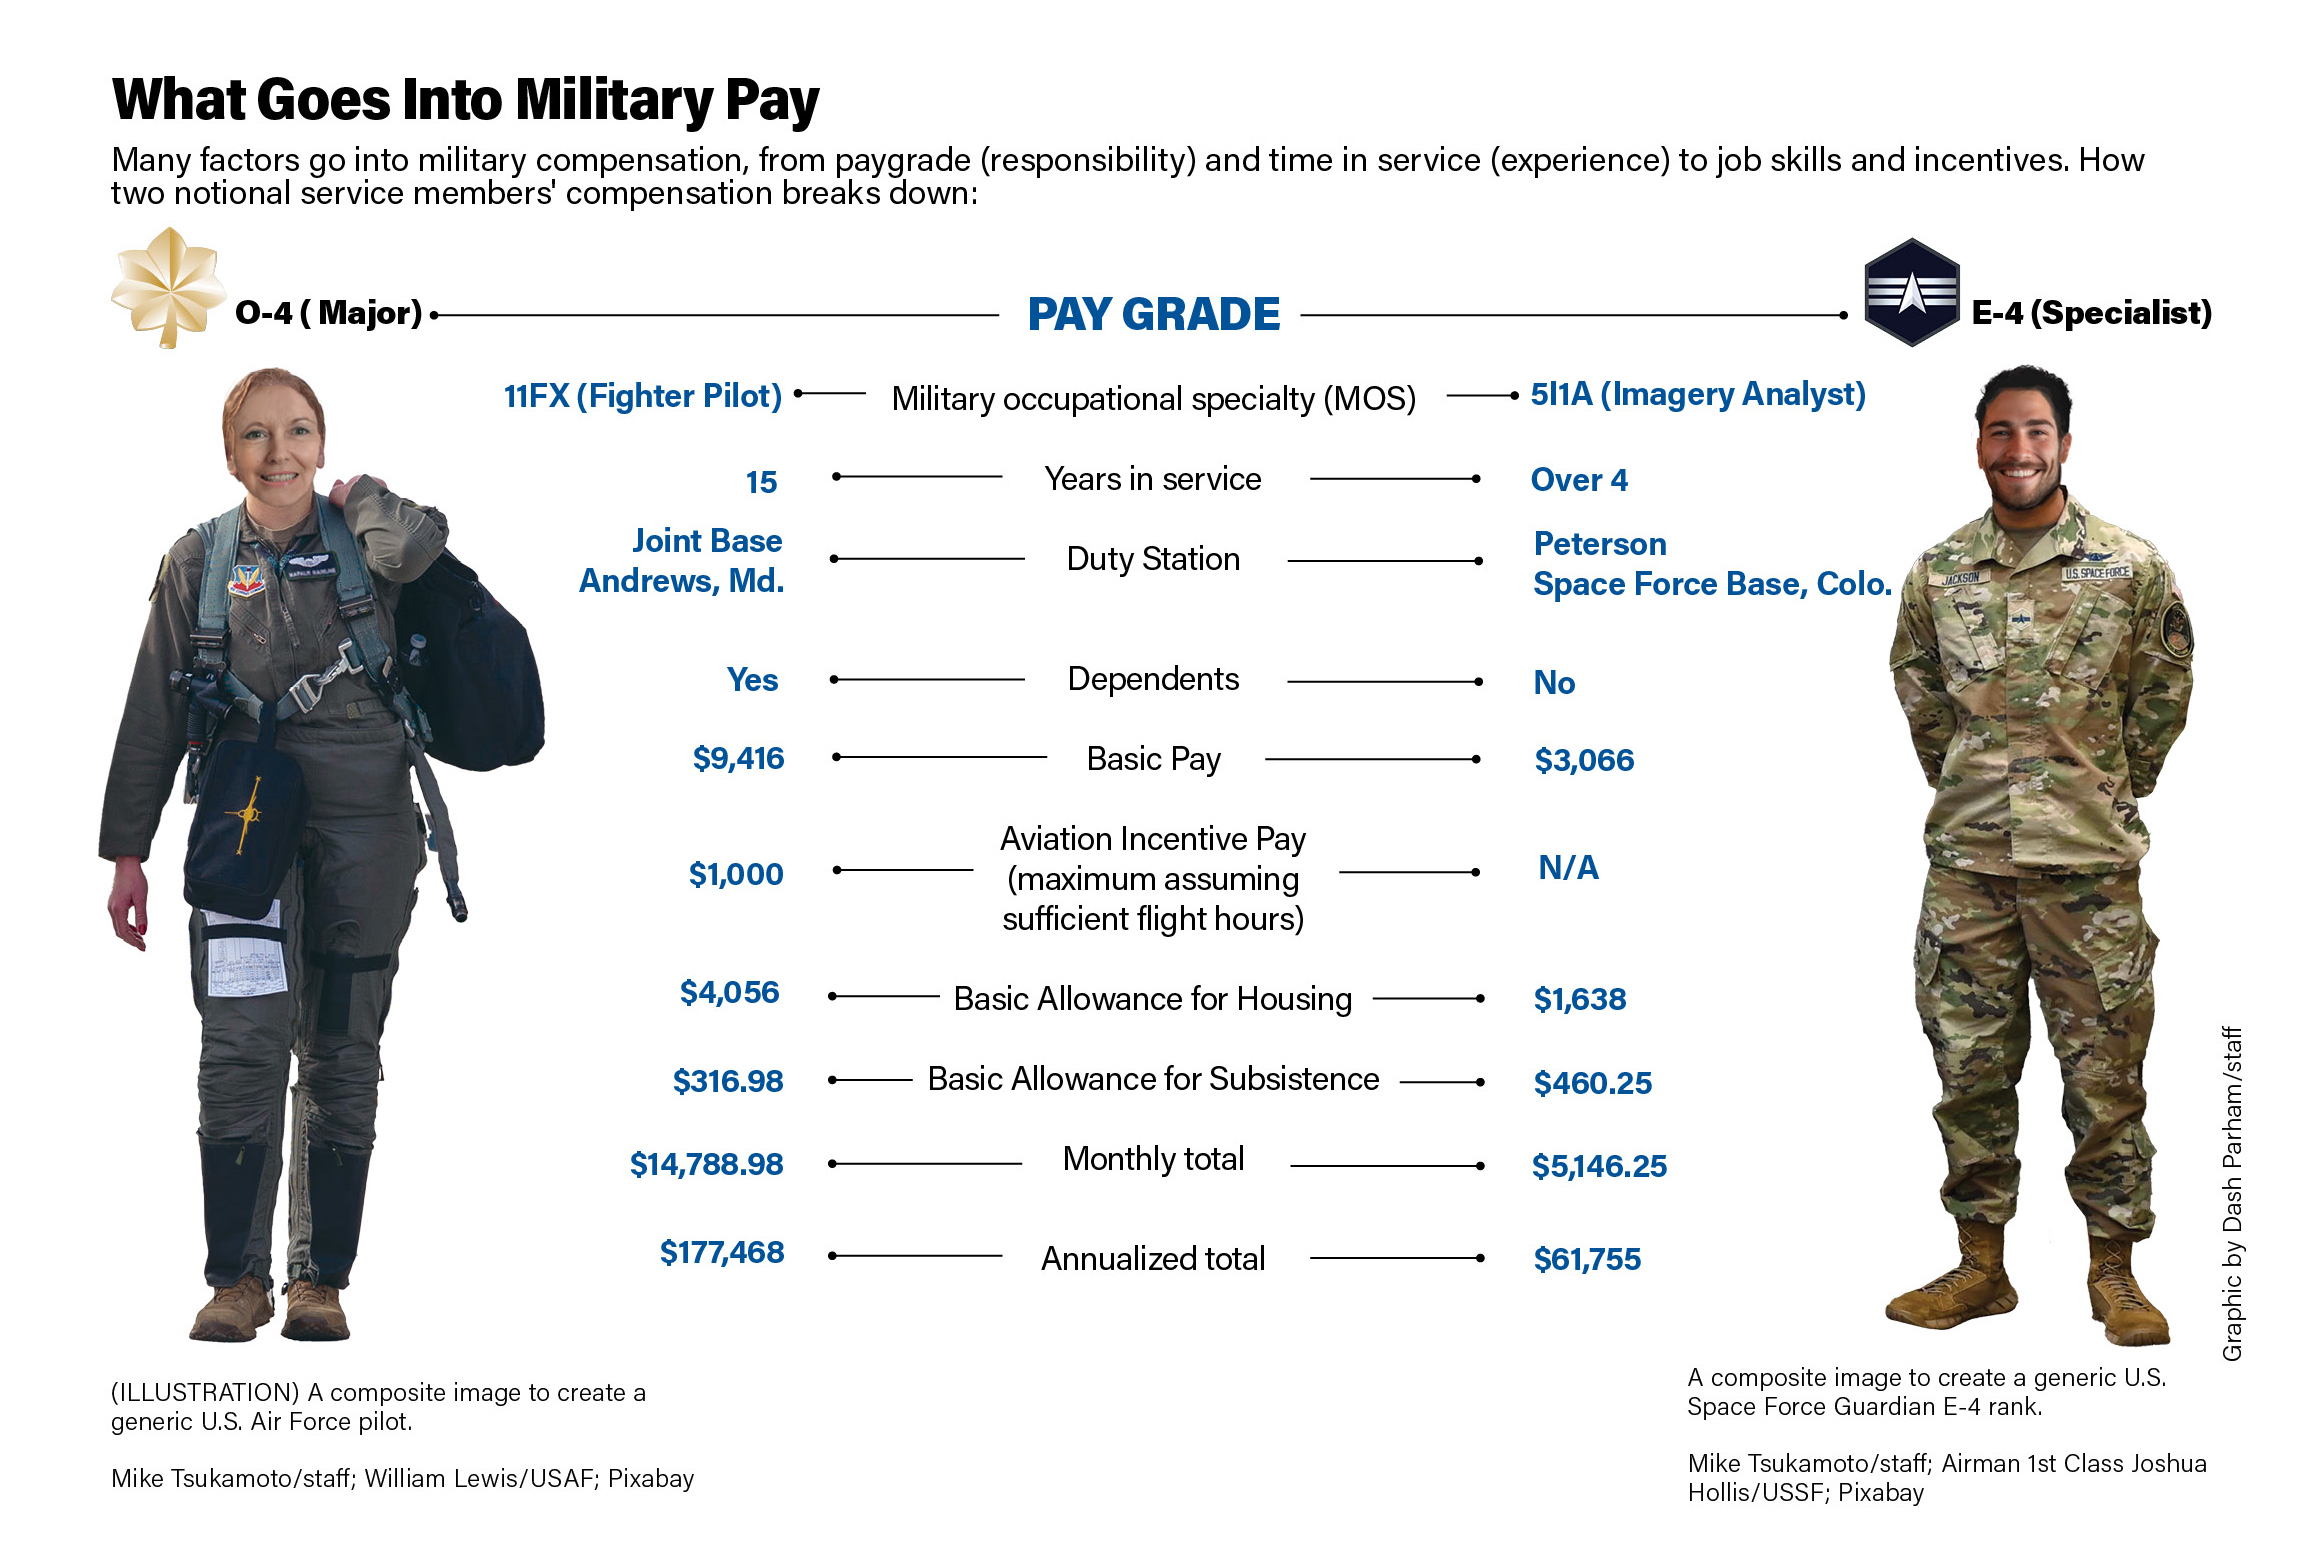
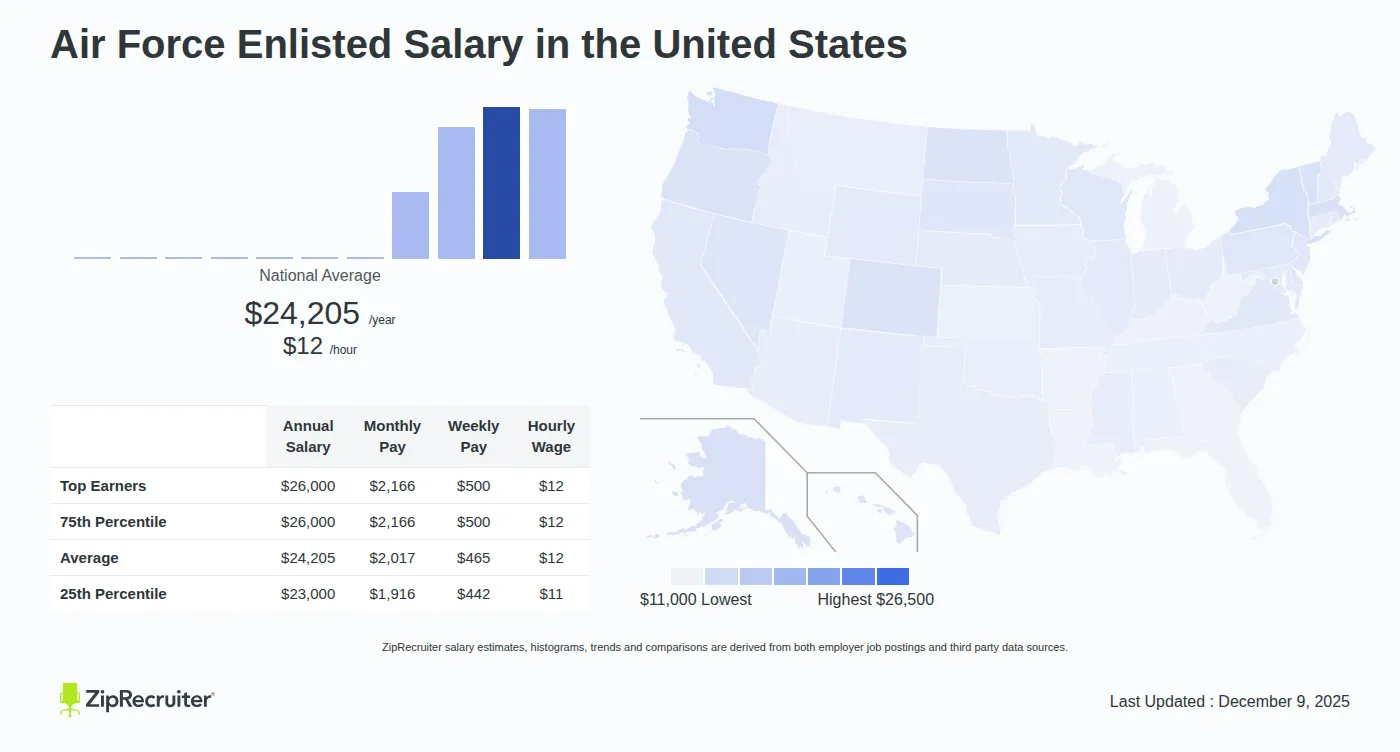
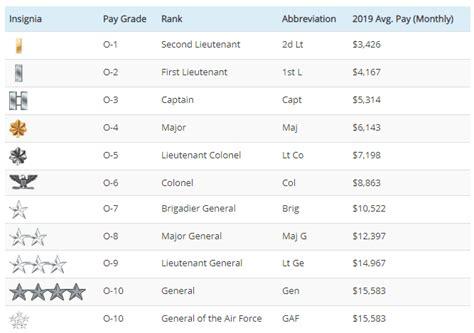
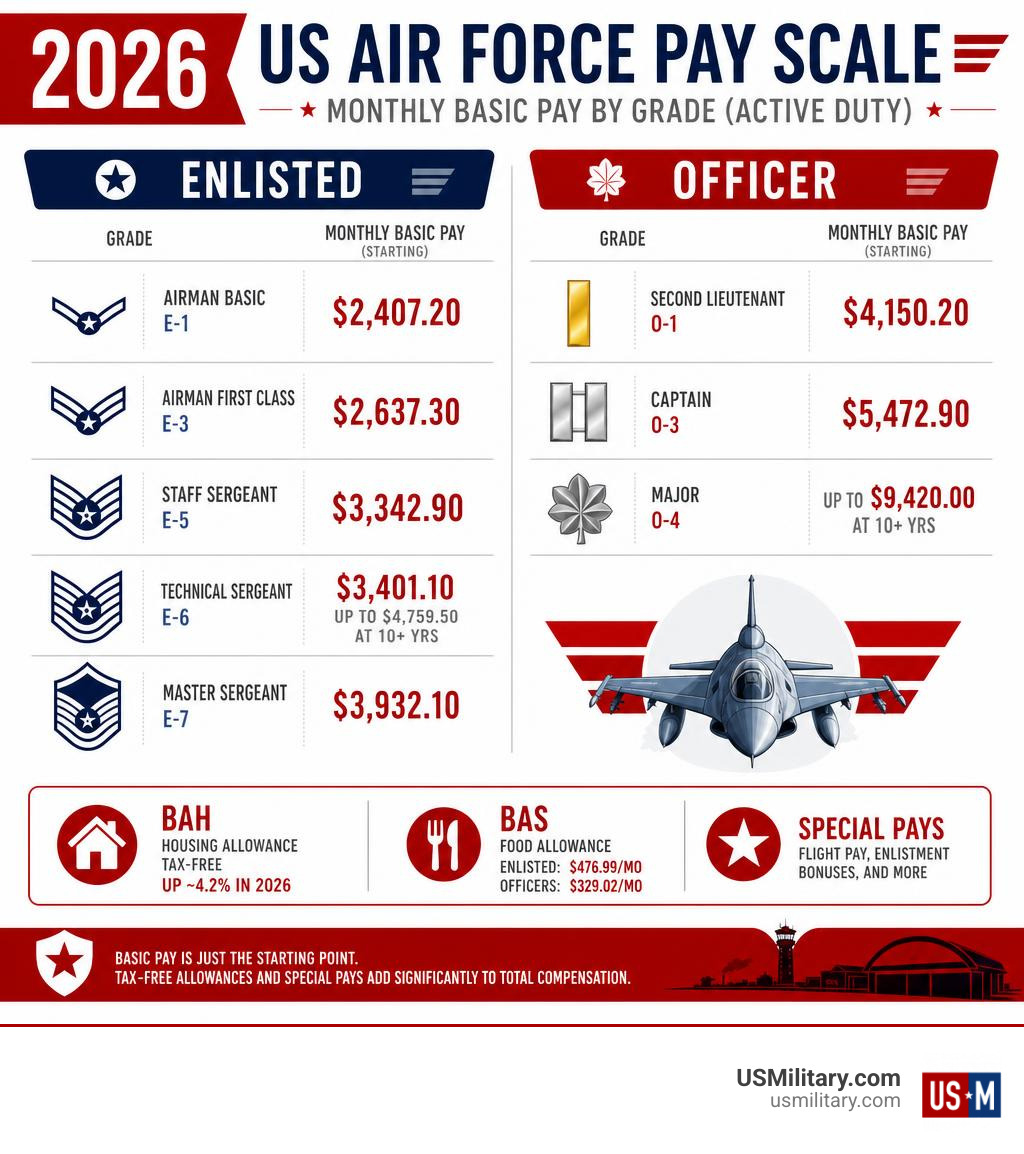
When I first looked into enlistment compensation, the numbers on the recruitment poster didn't match what my friend's brother was actually taking home. That gap between advertised pay and real take-home pay is where most people get confused, so let me walk through how this actually works in practice. Base pay for an Air Force enlisted member follows the military pay chart, which is determined by rank and years of service. A fresh E-1 with zero time makes roughly $1,785 a month before deductions. By the time you reach E-3 with two years, you're looking at around $2,124 monthly. An E-7 with twelve years sits near $4,840. These are the numbers Congress sets, and they haven't changed dramatically in recent years despite cost-of-living adjustments. But base pay is only roughly 60% of total compensation, and that's the part most people don't understand when they're making their decision. The rest comes through tax-advantaged allowances that don't show up on your W-2 the same way.
Basic Allowance for Housing (BAH) varies significantly by location. If you're stationed in San Diego with dependents, BAH might be $3,200 monthly. If you're at a base in rural Texas, it could drop to $1,400 for the same rank. The calculation uses zip code, pay grade, and dependency status. Single service members get about 95% of the full BAH rate, which is a detail that catches people off guard. Basic Allowance for Subsistence (BAS) is simpler. It's roughly $280 a month for all enlisted ranks, and about $480 for officers. This doesn't vary by location. You get it whether you eat at the dining facility or buy your own groceries, though most people factor it into their personal budget anyway. Here's something recruitment usually buries: the High Year Tenure (HYT) system creates a hard ceiling for many enlisted ranks. An E-5 without a promotion might be forced out after twelve years depending on the career field. I knew someone who spent eight years as a E-4 because the promotion board was brutal in their specialty. Base pay at E-4 with six years is roughly $2,800 monthly, plus allowances. That's decent money, but the stagnation is real and it affects retirement calculations down the line.
Special Pays are where the numbers get interesting. Language proficiency pay runs $250 to $1,000 monthly depending on fluency level and criticality. Danger pay (Hostile Fire Pay) adds $225 when you're in a designated area. Special Duty Assignment Pay for roles like recruiters or drill sergeants can add $300 to $600 monthly. Aviation Career Incentive Pay for pilots starts around $500 monthly and scales up with experience. These are often the difference between a comfortable middle-class life and just getting by. The THRSC (Total Homeowner Rental Subsistence Credit) and similar housing programs have replaced some older allowances, and the transition created confusion for several years. If you're looking at this information for a decision, make sure you're reading current regulations, not ones from 2018 that might reference expired programs. Retirement is the elephant in the room. The Blended Retirement System (BRS) changed everything for anyone who entered after 2018. You get immediate vesting in the Thrift Savings Plan with automatic 5% government contribution if you contribute at least 5%. That's essentially free money that compounds. The pension portion is 2% per year of service times your high-three average base pay, payable at 60 (or 62 with the reduced option). A E-7 retiring after 20 years with BRS gets roughly 40% of their final base pay as a pension, plus the TSP account that could be worth $200,000 to $400,000 depending on market performance.
Get the Full Details

Someone who stays 30 years under BRS gets 60% of their high-three base pay as a pension. For an E-9 with 30 years, that's roughly $8,000 monthly from the pension alone, plus TSP, plus BAH if they choose to live on base or take the allowance. That's legitimately comfortable in most parts of the country. But here's what the recruitment pitch doesn't emphasize enough: the promotion bottleneck is real. Going from E-4 to E-5 requires a promotion board review, minimum time in service, and meeting criteria that varies by career field. In some specialties, the wait time is 18 to 24 months. During that wait, you're stuck on E-4 pay while doing essentially the same job. I worked with a E-4 who waited three years for promotion to E-5 in a crowded specialty. Three years of $2,800 monthly when his peer in a different AFSC was already E-5 at $3,200. Education benefits under the Post-9/11 GI Bill are substantial but have limitations. You get 36 months of tuition and fees coverage at the public in-state rate, plus a monthly housing allowance while in school. The Yellow Ribbon Program covers private school costs at participating institutions. But if you use up those benefits for a bachelor's degree, you have nothing left for graduate school unless you qualify for additional programs like the Montgomery GI Bill or service-specific scholarships.
Healthcare is another major component. TRICRA covers you and your family at minimal cost. Emergency room visits might cost $50 copay. Prescriptions follow the military formulary with tiered copays. Dental and vision are separate programs with different coverage levels. The actual value is hard to calculate precisely, but a comparable civilian health insurance plan for a family would run $800 to $1,200 monthly in premiums alone. One edge case that trips people up: deployment pay isn't taxable. Combat zone tax exclusion (CVT) covers all military pay earned in a designated combat zone. If you're deployed to an approved area, that $4,000 monthly becomes completely tax-free. Combined with BAH and BAS, your effective take-home rate during deployment can exceed what you'd make in a civilian six-figure salary, and you pay zero federal income tax on it. Perks beyond the paycheck include commissary shopping (tax-free groceries below market prices), exchange store discounts, Morale Welfare and Recreation (MWR) programs, and access to on-base facilities like gyms, pools, and recreation centers. A family of four spending $1,500 monthly on groceries at the commissary might save $200 to $300 compared to civilian grocery stores, not counting the tax savings.
The pay delay issue is worth mentioning. Military pay processes on the 1st and 15th of each month. If those dates fall on weekends or holidays, you get paid the previous business day. Late payments are rare but happen during system upgrades or force reductions. I've heard stories of 48-hour delays during transition periods, and while the government does pay interest on late wages, the cash flow disruption is real for people living paycheck to paycheck. Separation pay is another consideration. If you leave before 20 years, you don't get a pension. You get your TSP account (what you contributed plus matching), severance if you qualify, and education benefits. For a E-5 with eight years leaving voluntarily, that TSP might be $40,000 to $60,000 depending on contributions and market timing. It's not nothing, but it's nowhere near the retirement security of a 20-year veteran. Here's a practical tip that experienced members wish they'd known: maximize your TSP contributions early. The 5% government match is immediate and vested. If you contribute 5% of your $3,000 monthly base pay, that's $150 monthly from the government for free. Over 20 years at an average 5% return, that alone becomes roughly $65,000. Contribute more and the numbers grow substantially. This is the single most impactful financial decision you can make as a service member.
The deployment tax benefits are often underutilized. If you're eligible for the CVT, make sure your pay is correctly coded. Some units mess this up during transitions, and you might overpay taxes that should be excluded. File Form 4187 with your unit personnel office if you suspect an error, and request a refund when you file your return. Civilian job transferability is another factor. Certain AFSCs translate well to civilian careers (cybersecurity, healthcare, engineering). Others don't. An E-5 who's been a parachute rigger for eight years faces a harder transition than an E-5 who's been a network systems administrator. Consider how your specialty will read on a civilian resume before committing to a long career. The compensation picture is genuinely competitive when you look at total package value, not just base pay. But the trade-offs — deployments, frequent moves, rigid structure, separation from family — are real costs that don't appear on any pay chart. Understanding the full picture before you sign helps you make an informed decision rather than one based on recruitment materials alone.