Calculating Diluted EPS When Options Are Outstanding
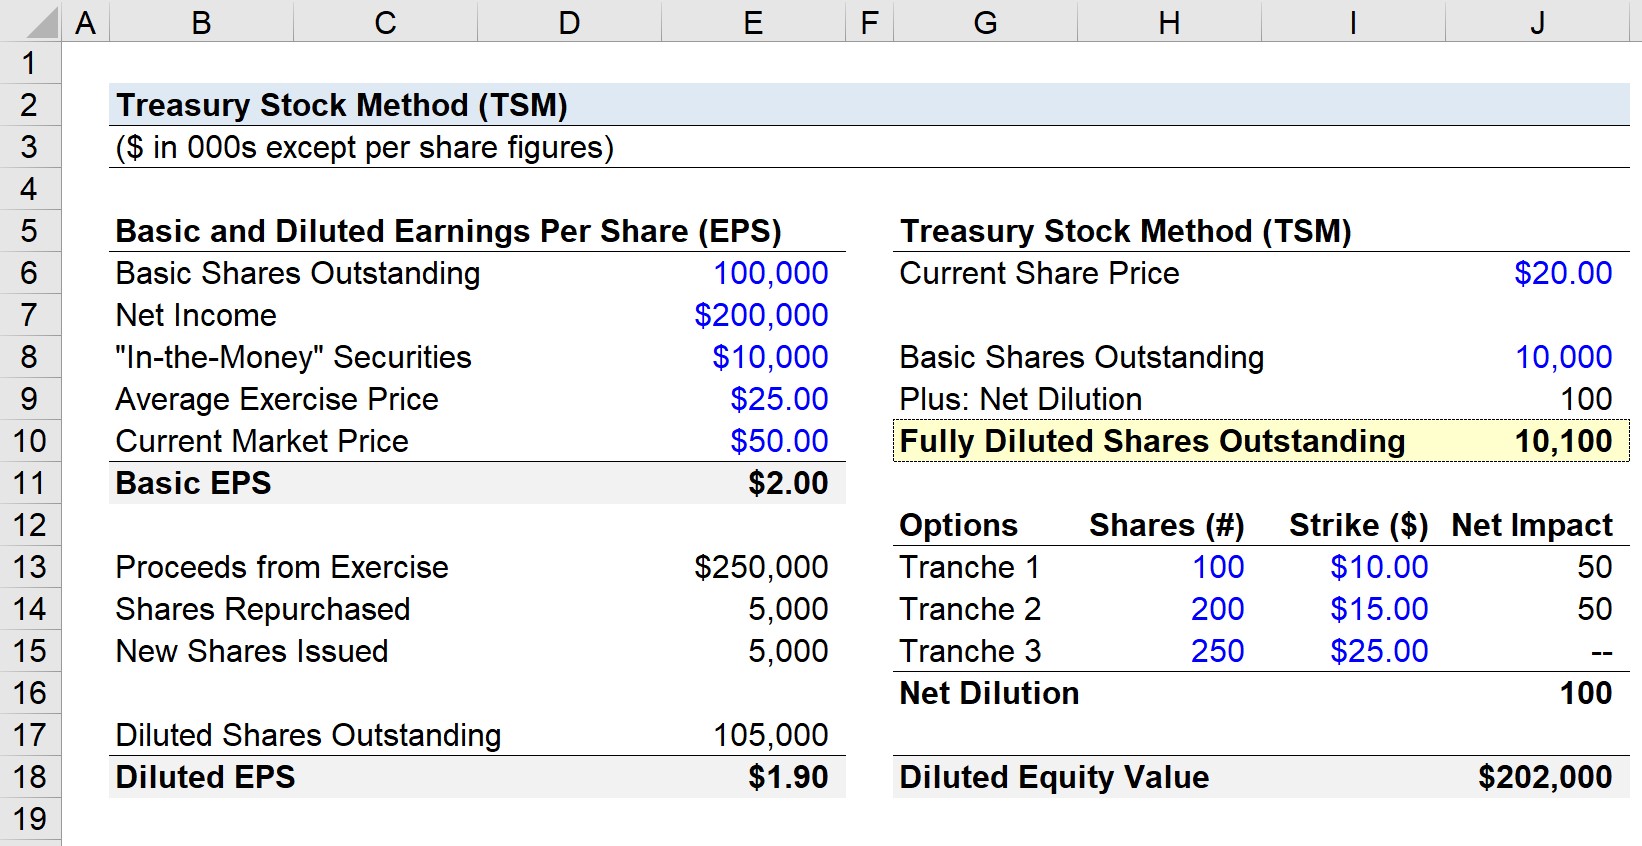
Most candidates blow right through the basic EPS formula and then trip on diluted earnings per share because they don't actually understand what the treasury stock method is doing under the hood. It's not a separate formula. It's just a logical exercise in figuring out how many additional shares would exist if every in-the-money option got exercised, then buying back as many of those shares as possible with the proceeds at the average market price during the period. I remember sitting in a mock exam and seeing a question where the company had both stock options and convertible bonds outstanding. The instinctive move was to just add the options using treasury stock and the bonds using the if-converted method separately, which is correct, but the options number was derived from a vesting schedule mid-year, not a simple beginning-of-year figure. I spent about six minutes recalculating the weighted-average options outstanding before realizing the answer choices gave me away. The fix is straightforward once you internalize the mechanics: treat each tranche of options separately based on when they were outstanding, apply treasury stock to each, then sum the incremental shares.
The Mechanics, Not the Memory Trick
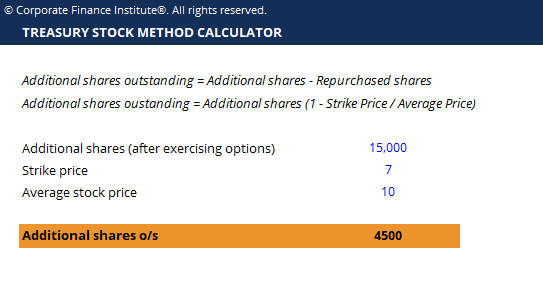
The procedure goes like this. You start with the proceeds the company would receive if all in-the-money options were exercised. That is the exercise price multiplied by the number of options. Then you divide those proceeds by the average market price of the stock over the reporting period. The result is the number of shares the company could theoretically buy back. The incremental shares added to the denominator are the original option shares minus those buyback shares. Only in-the-money options matter. If the exercise price is above the average market price, the options are out-of-the-money and they have no dilutive effect. You ignore them entirely. Here is the part people mess up. The proceeds come from the exercise price, not from any hypothetical fair value you calculated using Black-Scholes or some other model. The CFA curriculum uses the treasury stock method purely as a mechanical numerator adjustment within the EPS calculation. No option pricing model enters the formula. If a question gives you the grant date fair value of the options, that number is a distractor for diluted EPS purposes. It might be relevant for share-based compensation expense in the income statement, but it does not feed into treasury stock calculations. Another subtlety that catches people is the treatment of proceeds when the options are cashless exercisable. If the plan allows holders to exercise without paying cash, you cannot assume the company receives any proceeds. In those cases the incremental share count is simply the total number of options, because there is no buyback happening. I ran into this on a practice problem where the problem stated the options were settled net in shares. That means cashless exercise. The answer required adding all the option shares to the denominator with zero buyback offset. Most people in my study group marked the wrong answer because they blindly applied the treasury stock formula regardless of exercise terms.
Let me walk through a concrete example. A company has 10,000 stock options outstanding with an exercise price of $40. The average market price during the period is $50. The proceeds would be $400,000. Dividing $400,000 by $50 gives 8,000 shares that could be repurchased. The incremental shares are 10,000 minus 8,000, which equals 2,000. Those 2,000 shares get added to the denominator for diluted EPS. Now change the average market price to $35. The options are out-of-the-money. Proceeds divided by market price would give more shares than exist, which makes no sense in this context, so you simply record zero incremental shares. The method already tells you to exclude out-of-the-money options, so the calculation terminates there.
Get the Full Details

Common Pitfalls on the Exam
The first mistake is forgetting that only in-the-money options participate. Exam writers love to include out-of-the-money options in the data set to see if you will erroneously add dilutive shares. The second mistake is using the ending stock price instead of the average stock price. The average price is what matters because it represents the typical trading level across the entire period. The third mistake is doubling up the buyback. You only buy back shares once with the proceeds. Some candidates calculate buyback shares and then somehow subtract them from the wrong place in the denominator. The incremental shares go into the diluted share count directly. There is also the interaction with convertible securities to consider. When a company has both options and convertibles, you process them in order. Options first using treasury stock, then convertibles using the if-converted method. The output of the option step feeds into the denominator that the convertible step uses. Reversing the order can produce a different result if the securities are deeply dilutive, because the share count changes the per-share impact. The CFA curriculum expects you to apply treasury stock first, then if-converted, though in most exam questions the difference is negligible because the numbers are designed to avoid this edge case.
When the Method Breaks Down
The treasury stock method assumes the company can repurchase shares at the average market price. That assumption fails in thin markets or during periods of extreme volatility where the average price is not representative of what the company could actually pay. It also assumes all proceeds are used for buybacks, which is not how companies operate in reality. The method is a standardized convention for financial reporting, not a simulation of corporate behavior. If you encounter a problem that asks about actual anti-dilutive behavior or real-world treasury operations, treasury stock method results will not reflect that. Use a narrative adjustment or flag the limitation instead of forcing the formula. One more thing. The method does not account for the tax benefit of stock option exercises in the basic CFA Level 1 framework. Advanced courses may introduce a tax effect adjustment to the proceeds, but for the exam you work with pre-tax proceeds unless explicitly told otherwise. Adding tax benefits prematurely will inflate your incremental share count and push you toward the wrong answer choice. If you want practice problems, the CFA curriculum itself has a dedicated section on diluted EPS with treasury stock calculations, and the official mock exams include at least one question per testing window that tests this exact mechanism. The reading companion volume also has worked examples with partial solutions that show the intermediate buyback step, which is useful for checking your arithmetic before you commit to a final answer.