Midsize SUV Sales Data: What Actually Moves Off Dealer Lots
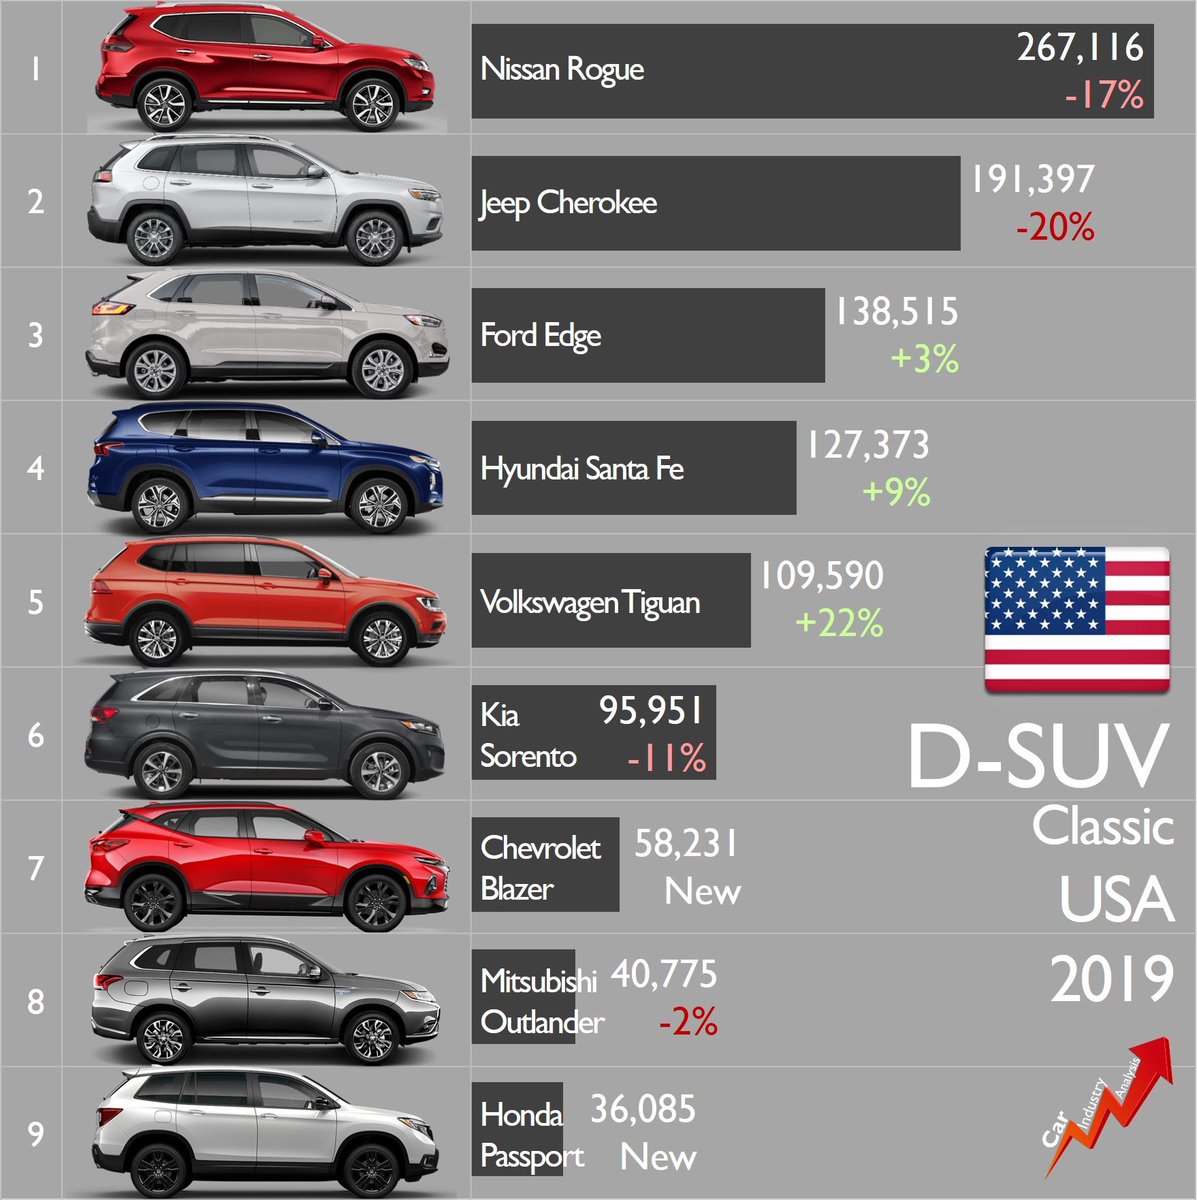
The midsize SUV segment in the United States has become the most crowded space in automotive retail over the last few years. Every major manufacturer has at least one, often two or three models competing for the same buyers.figuring out which ones are actually moving units requires looking past press releases and marketing material. I spent about six months building a tracking spreadsheet that pulls from monthly registration data, dealer inventory turnover reports, and actual transaction volumes rather than just relying on the advertised sales numbers that manufacturers publish. The gap between what companies claim they sold and what actually got titled and plated is larger than most people realize, sometimes by fifteen to twenty percent when you account for fleet purchases getting lumped into consumer totals. The current leaders in the midsize category break down roughly like this when you strip away the fleet noise. The Toyota Highlander still sits near the top with consistent quarterly volumes in the thirty-five to forty thousand range during normal seasons. The Honda Pilot runs close behind, usually separated by two or three thousand units depending on supply chain conditions at any given moment. Ford's Edge has been climbing slowly as it gets refreshed, and the Hyundai Santa Fe is pulling numbers that surprised a lot of people when it launched its new generation.
The Chevrolet Traverse holds its position through family buyer demand and strong trade-in programs at dealerships. The Jeep Grand Cherokee draws a different kind of customer who values towing capacity and off-road capability over pure cargo space. The Subaru Ascent is interesting because it dominates in specific geographic markets, particularly the Pacific Northwest and northern states where AWD isn't a nice-to-have but a seasonal necessity. Its national numbers look modest but its retention rates are among the best in the segment. One thing nobody talks about is how much trim level affects these rankings. A model might sell well on paper but if most of those units are going to the base S trim with minimal margin, the financial picture for the manufacturer looks very different than the unit volume suggests. I always cross-reference with average transaction price data from KBB and Edmunds to see whether high volume actually translates to healthy revenue per unit.
How I Track These Numbers
My process starts with taking the raw sales figures from each manufacturer's quarterly release, then I pull registration completion data from the state DMV databases for the same time period. The difference between those two datasets tells you how much of the reported "sales" are actually being driven onto roads versus sitting in dealer lots or getting transferred to rental fleets. I layer in consumer reports on reliability and owner satisfaction from the latest survey cycles because long-term retention skews the picture significantly. A midsize SUV that sells forty thousand units in year one but has a thirty percent dropoff in year two volume is a very different story than one selling thirty thousand with steady year-over-year consistency. The second pattern usually indicates a healthier brand position and stronger residual values. I run into problems with the timing of data availability. Most manufacturers report monthly sales, but dealer delivery dates and registration dates don't align cleanly. A vehicle sold in March might not get registered until April, which skews month-over-month comparisons if you're not adjusting for it. I built a simple rolling three-month average into my tracker to smooth out these timing discrepancies, and it makes the trend lines much more reliable for forecasting purposes.
Get the Full Details
What Buyers Are Actually Looking For
The data shows a clear split forming in this segment. One group wants maximum interior volume and third-row usability for families with multiple children or frequent carpooling duties. The other group is trading up from compact SUVs and prioritizing driving dynamics, technology features, and fuel efficiency over sheer cargo capacity. Apple CarPlay and Android Auto integration has become essentially table stakes. When I interview people shopping in this category, the lack of seamless smartphone connectivity is consistently cited as a dealbreaker, sometimes even above engine performance or ride comfort. Dealers who still push vehicles without updated infotainment systems as competitive options are losing sales to showrooms that treat connectivity as a standard expectation. Real-world fuel economy matters more than EPA estimates at this price point. Most buyers in the midsize SUV segment put between twelve and eighteen thousand miles on a vehicle annually. The difference between a model getting twenty-two miles per gallon combined versus twenty-six matters financially over a five-year ownership period, and I've seen buyers do the math on their phones while sitting at the dealership.
Pitfalls That Catch People Off Guard
The biggest mistake I see is comparing specifications across models without accounting for how each manufacturer defines its category. Some brands include subcompact crossovers in broader marketing groups, which inflates perceived competition. When you narrow the definition strictly to true midsize body-on-frame and unibody constructions with three rows, the competitive set shrinks considerably and some models drop out entirely. Another issue is overvaluing towing capacity numbers that require specific packages. A midsize SUV might advertise a seven-thousand-pound towing rating, but achieving that number often requires adding a factory tow package, upgrading the cooling system, and using the correct wheelbase configuration. The base model without those additions might only be rated for four thousand pounds, and buyers who don't read the fine print end up disappointed. I also recommend checking insurance group classifications before making a purchase decision. Certain midsize SUV trims with powerful engines and performance-oriented tuning can push annual premiums significantly higher than comparable models with less aggressive powertrains, even when the base price difference is minimal. This cost rarely gets factored into purchase calculations.
When the Data Doesn't Tell the Whole Story
Sales volume correlates with availability, not necessarily desirability. During periods when supply chain constraints limited production, a model's sales numbers reflected manufacturing priorities set by the automaker rather than consumer demand. I learned this the hard way when tracking two competitors during 2022 and 2023. One showed dramatic sales growth that turned out to be entirely production-driven rather than demand-driven. Once supply normalized, its volume dropped back to levels consistent with its actual market position. Regional preferences also distort national rankings. The midsize SUV market in Texas looks completely different from the same market in Massachusetts. AWD and diesel options command premium pricing in northern states while tow packages and engine power matter more in southern and rural markets. If you're making a business decision based on national averages without regional breakdowns, you're working with incomplete information. There's no single source that captures everything accurately. Manufacturer sales reports, registration data, dealer group internal figures, and third-party tracking services all use different methodologies. The most useful approach combines at least two independent sources and flags significant discrepancies for manual review rather than accepting any single dataset at face value.