Why UK Tariff Rates Feel Like a Part-Time Job
I spent three years classifying imported goods for a mid-sized electronics distributor. The simplest part was importing from the EU after Brexit. The hardest part was everything else. Tariff classification isn't just about looking up a number. It's about understanding the Combined Nomenclature, knowing when the UK specifically amended EU classifications, and figuring out what happens when your product falls between two codes. The UK operates on the UK Global Tariff (UKGT), which replaced the EU Common External Tariff when the transition period ended on December 31st, 2020. But here's what most people miss: the UKGT isn't a clean break from EU HS codes. The UK still uses the same 8-digit Combined Nomenclature structure for most goods. The differences come in the later digits and in specific duty rates that the UK government adjusted unilaterally.
The Story Of UK Tariff Rates A Comprehensive Guide To Navigating The Complexity Of Trade Tensions
The foundation is the Harmonized System, maintained by the World Customs Organization. Every country uses the first six digits identically. The UK adds two more digits at the CN level, bringing it to eight digits for import declarations. Some tariff lines go to ten digits for statistical purposes through the USITC-style breakdown. When you're filing an import entry through CDS, the customs system checks your commodity code against the current tariff schedule. The schedule includes the duty rate, any VAT implications, and whether there are any anti-dumping duties, countervailing duties, or safeguards applied to that specific code. Missing any of these can result in a post-clearance audit finding that hits you months later. I remember one shipment of LED display panels that was classified under CN code 8528 72 00. Straightforward enough. But the importer had sourced them from Vietnam, and there was an anti-dumping duty of 42% specifically targeting Chinese-origin panels that were being rerouted through Vietnamese assembly plants. The classification code was correct, but the origin declaration triggered the additional duty. We caught it before customs submission by cross-referencing the supplier's certificate of origin against the DHLC anti-dumping database, which saved roughly £18,000 on that single shipment.
How to Find the Right Commodity Code
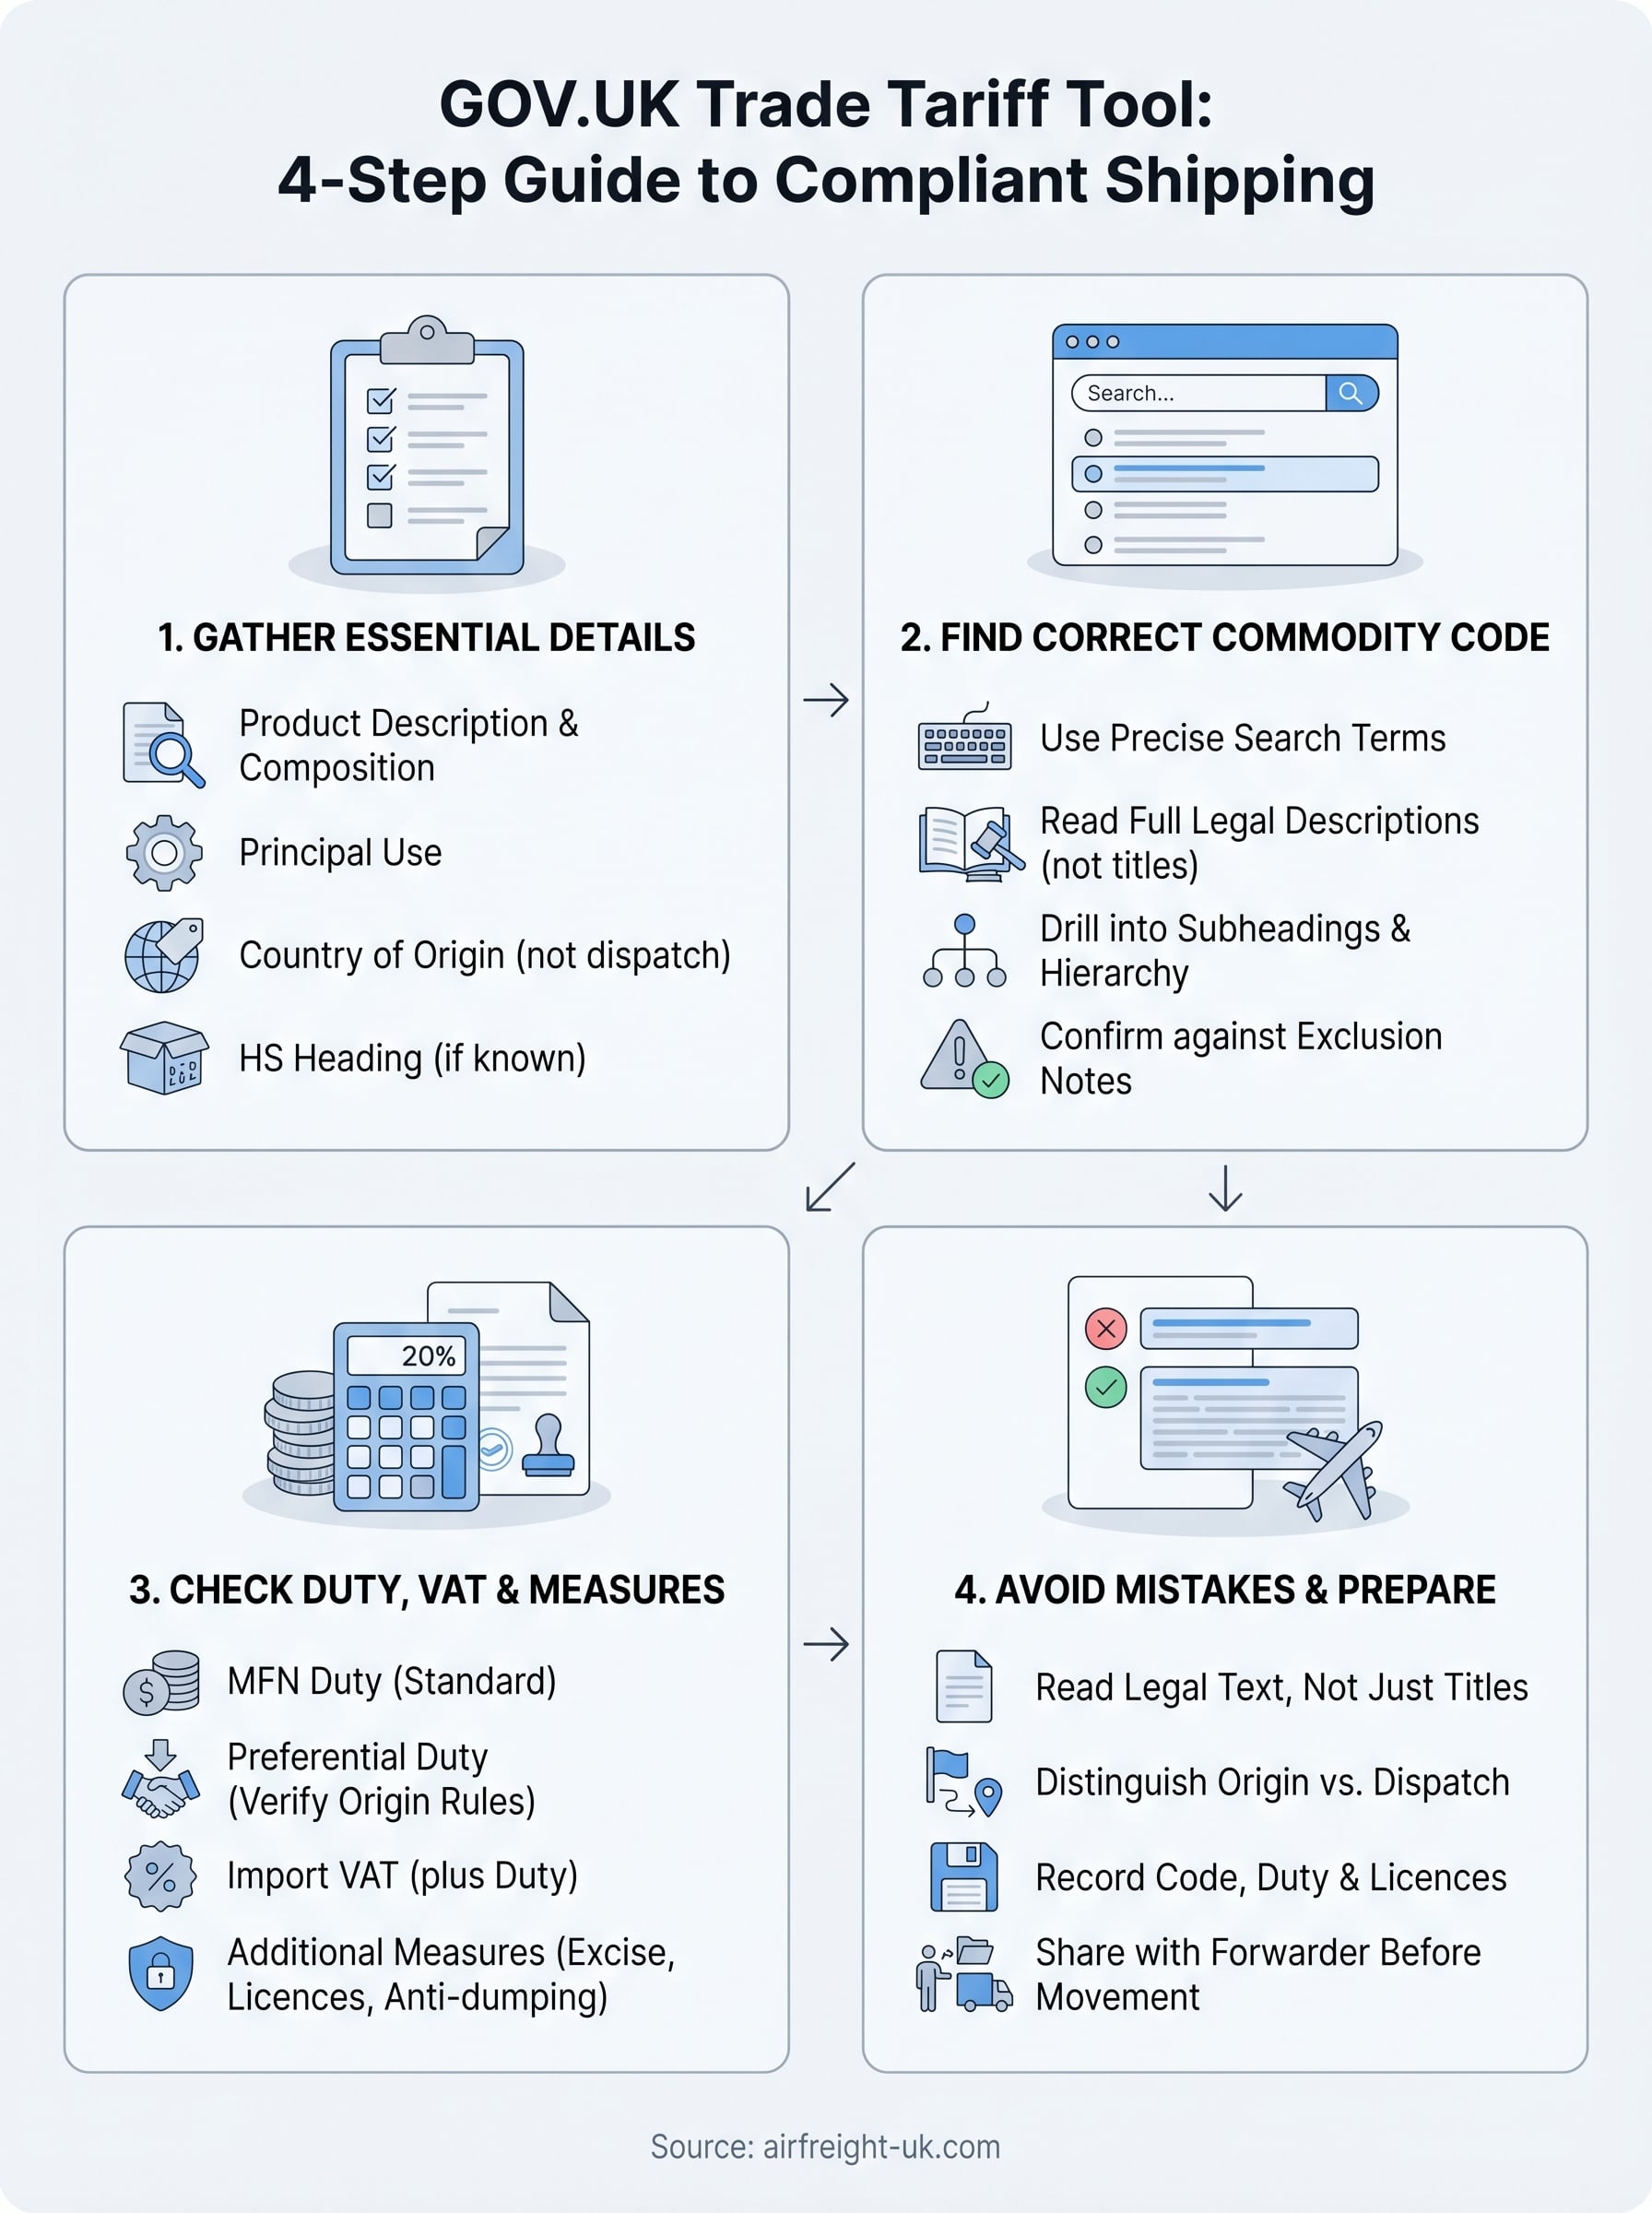
The primary tool is the UK Trade Tariff at gov.uk/trade-tariff. You can search by keyword, by HS code, or by country of origin. The search function is decent but not great. It returns results in a table format that's usable on desktop but painful on mobile. Here's the practical workflow I recommend. First, identify the technical specifications of your product. Not the marketing description. The actual physical characteristics, materials composition, and intended function. This matters because customs classification follows the General Rules of Interpretation, and Rule 1 states that classification is determined by the terms of the headings and any relative section or chapter notes. Second, look up the heading that best describes the product. Don't jump to a subheading. Read the chapter notes first. Chapter notes can override what seems like the obvious classification. I've seen products misclassified multiple times because someone skipped the chapter notes and went straight to the heading text.
Get the Full Details
Third, drill down through the subheadings using the CN tree. Each level has legal notes. The notes at each level can exclude products that seem to fit. For example, heading 8517 covers telephone sets, but note 3 to Chapter 85 explicitly excludes certain types of audio equipment that share similar technology. If you don't read that note, you'll pick the wrong code. Fourth, verify the full 8-digit code against the tariff schedule to confirm the duty rate, VAT rate, and any additional measures. This step is non-negotiable. A wrong code doesn't just mean you pay the wrong amount. It means your import license might be invalid for that classification, and you could face penalties during a retrospective check.
Duty Calculation Basics
The UK applies several types of duties. The standard customs duty is based on the commodity code and the customs value of the goods. Customs value is typically the transaction value, which is the price actually paid or payable when the goods are sold for export to the UK, with certain adjustments added. The adjustments include the cost of packing, any assists provided by the buyer, royalties and license fees related to the goods, and the value of any elements supplied by the buyer that are used in the production of the imported goods. These adjustments are where most under-declarations happen. I've seen importers consistently forget to include the value of tooling and molds they provided to overseas manufacturers, resulting in a customs value that was 15 to 20% too low. Once you have the customs value, apply the duty rate from the tariff schedule. Then add VAT at the standard rate of 20% on the sum of the customs value plus the duty plus any excise duties. The order matters because VAT is calculated on a higher base that includes the duty itself.
For example, if the customs value is £100,000 and the duty rate is 4.2%, the duty is £4,200. VAT is then 20% of £104,200, which equals £20,840. Total payable is £125,040. Simple arithmetic. Mistakes in the calculation are rare. Mistakes in determining the customs value are common.
Preferential Tariffs and Trade Agreements
The UK has standalone trade agreements with many countries now. The ones that matter most for importers are the agreements with the EU, Switzerland, and a growing network of countries including New Zealand, Singapore, Australia, and Japan. Each agreement has different rules of origin and different duty rates. Rules of origin are where preferential tariffs get complicated. Most UK agreements use either a change in tariff classification threshold or a regional value content requirement. The change in tariff classification rule means the manufacturing process must transform the goods sufficiently within the partner country. The regional value content rule requires a minimum percentage of the product's value to originate in the agreement territory. A supplier's declaration of origin is usually sufficient to claim preferential treatment. The UK no longer requires certified origin documentation for most agreements. Your supplier needs to confirm the goods qualify under the relevant agreement's rules, and you need to keep that record for four years. That's it. But you need to verify the supplier's claim independently. I once accepted a supplier's origin declaration for textiles without checking the yarn-forward rule, and the goods were made from Chinese fabric that was merely cut and sewn in Bangladesh. The preferential duty was wrong, and the subsequent customs demand included the full duty plus interest.
When Everything Goes Wrong
Post-clearance audits are the normal enforcement mechanism. HMRC reviews import declarations from the previous four years. If they find classification errors, they will issue a demand for the additional duty. Interest accrues from the date the duty should have been paid. There's no penalty for an honest mistake if you self-disclose, but hiding an error makes it a deliberate concealment situation with penalties starting at 30% and going up to 100% of the lost revenue. The self-disclosure process is handled through the Disclosure Facility on GOV.UK. You can make an anonymous preliminary inquiry first. Then if you decide to disclose, you have a window to provide the details. The key advantage of self-disclosure is that penalties are significantly reduced compared to if HMRC discovers the error themselves. The reduction depends on when you disclose. A prompt disclosure gets the maximum penalty reduction. One edge case that catches people out is re-importation of UK-origin goods that were exported and then re-imported after some processing abroad. If the goods qualify under the inward processing relief scheme, you can avoid paying duty on the re-import. But the conditions are strict. The goods must be the same goods that were exported, and you need to maintain proper records showing the identity and continuity of the products throughout the processing period. I worked with a company that sent components to Turkey for assembly and then re-imported the finished products under IP relief without keeping adequate traceability records. HMRC rejected their claim and assessed full duty on the processed goods, which carried a higher rate than the original components.
Practical Tools and Resources
Beyond the official UK Trade Tariff, there are commercial classification databases that update more frequently and offer better search functionality. Descartes Datamyne, Panjiva, and ImportGenius all provide customs data and classification references, though they charge subscription fees. For most small importers, the free government tools are sufficient if you take the time to use them correctly. Binding Tariff Information is the official confirmation you can request from HMRC for a specific commodity code. A BTI is binding for three years across the entire UK and provides legal certainty. The application takes about 60 days, so plan ahead if you're launching a new product line. The fee is around £200 per application. Given that a misclassification can cost tens of thousands in retroactive duties, the BTI fee is negligible. For ongoing compliance, I recommend maintaining a classification register for every product you import. Record the commodity code, the legal basis for the classification, the source of the duty rate, the origin rules applied, and the date of the last review. Review it at least annually because tariff schedules change regularly. The UK publishes annual updates to the UKGT, and during trade disputes, supplementary duties can be added with very short notice.

The complexity of UK tariff rates isn't going away. The post-Brexit system gives the UK more flexibility to set its own trade policy, which means more changes, more negotiated agreements, and more opportunities for classification errors. The system rewards people who invest in understanding the underlying rules rather than treating tariff classification as a box-ticking exercise.