What the Nikkei 225 Actually Is
The Nikkei 225 is Japan's headline stock index, covering 225 of the largest and most actively traded companies on the Tokyo Stock Exchange. It's price-weighted, which means a company with a higher share price gets more influence over the index's movement than a company with a lower share price, regardless of the company's actual market value. This is the part most beginners get wrong when they compare it to the S&P 500. I've tracked Japanese equities since the early 2000s, and I can tell you that the price-weighting quirk creates real headaches when you're trying to hedge or replicate the index. A stock like Keyence, which trades at well over 60,000 yen per share, will dominate daily movements even though its market cap isn't the largest. Meanwhile, a mega-cap like Sony might have a lower share price and less weight than you'd expect. This distorts the index's relationship to the broader Japanese economy.
The Story Of Nikkei 225 Your Guide To Japans Top Index
If you're looking for a straightforward guide, the Nikkei 225 tracks the top 225 blue-chip companies in Japan. It was launched by the Nihon Keizai Shimbun newspaper in 1950, with an initial base value of 38.94 yen. That number is arbitrary, but it gives you a reference point when you're looking at historical data. The index went through major adjustments in 1969 and again in 1985 when they switched to a market-cap-like adjustment factor to reduce the impact of extreme price movements. Here's something most guides won't tell you: the Nikkei 225 is not a good representation of the Japanese market as a whole. It's heavily concentrated in industrials and technology. Financials and consumer staples are underrepresented compared to the TOPIX, which is a broader market-cap-weighted index. If you're allocating capital to Japan, you need to understand which index you're actually exposed to. The Nikkei moves differently than the average Japanese company. I learned this the hard way in 2013. I was managing a portfolio that was hedged using Nikkei futures, assuming the index captured the right risk factors. It didn't. The financial sector rebounded harder than the industrial sector during Abenomics, and my hedge was off by roughly 15 percent relative to the broader market. I switched to a TOPIX-based overlay shortly after.
How to Track the Nikkei 225
There are several ways to gain exposure. You can trade Nikkei 225 futures on the Osaka Exchange, which are highly liquid and denominated in yen. The contract size is 1,000 yen times the index level, so at current levels around 38,000, each point of movement is worth 100,000 yen, or roughly 650 US dollars depending on the exchange rate. This matters when you're calculating margin requirements. For retail investors, the easiest route is through ETFs. The ones that track the Nikkei 225 include the iShares Nikkei 225 ETF (FYX) listed on the London Stock Exchange and various Japanese domestic funds. These have expense ratios around 0.10 to 0.30 percent annually, which is cheap relative to active management but adds up over decades. I've held these in portfolios and can tell you the tracking error is usually under 20 basis points per year, though it widens during periods of extreme yen volatility. Another option is CFDs through brokers like IG or Saxo Bank. These let you trade the index without holding the underlying futures contracts. The spreads are typically 1 to 3 points, and leverage is available up to 5:1 depending on your jurisdiction. I don't recommend this for long-term holders because the financing costs erode returns, especially when interest rates rise. In a zero-rate environment like Japan experienced for years, the cost was negligible. That's changed.
Get the Full Details
The Price-Weighting Problem
Let me explain why price-weighting matters in practice. In a price-weighted index, if a stock splits two-to-one, the index drops by half the stock's previous price contribution, all else equal. This creates artificial downward pressure whenever a constituent executes a stock split. The Nikkei 225 has seen this repeatedly, most notably with SoftBank Group's splits and other high-priced tech names. Most people don't realize that stock splits can move the Nikkei by 100 to 200 points on their own, completely independent of any fundamental change. I've seen traders react to these moves as if something meaningful happened, when really it was just a mechanical adjustment. The index provider publishes a dividend adjustment factor quarterly, but the split adjustment happens in real time, which creates these unpredictable jumps. The workaround is to look at the Nikkei 225 Total Return version, which accounts for dividends, or to cross-reference with the TOPIX when evaluating whether a move is genuine. I keep both charts open on my screen. If the Nikkei is up 200 points and the TOPIX is flat, I know there's a weighting artifact at play. This habit saved me from making a bad trade decision in 2021 when a major constituent split sent the index lower on a day when fundamentals hadn't changed.
Historical Context That Matters
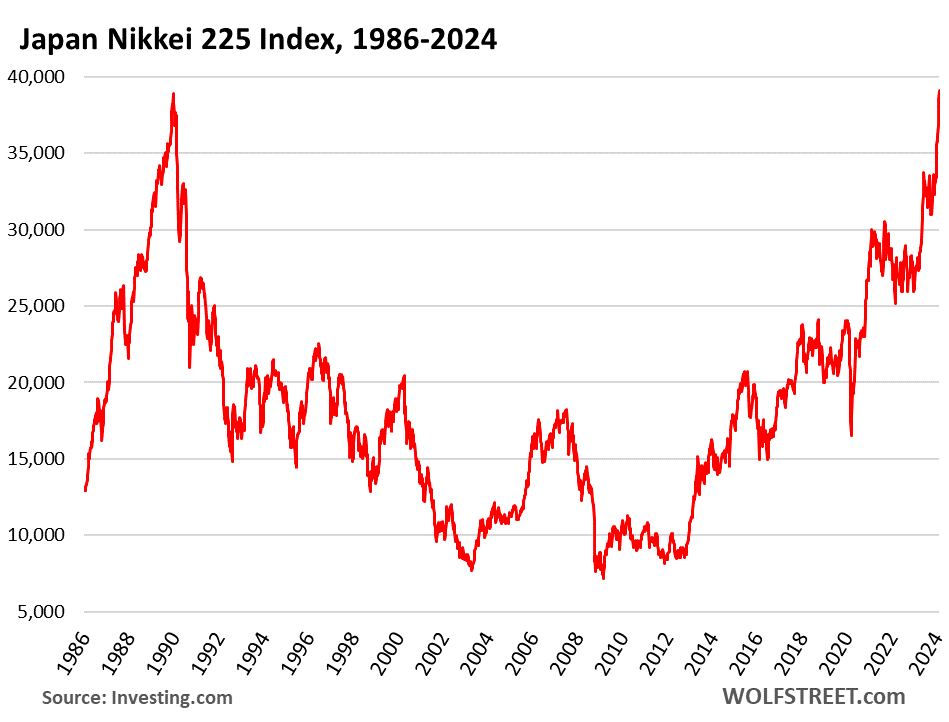
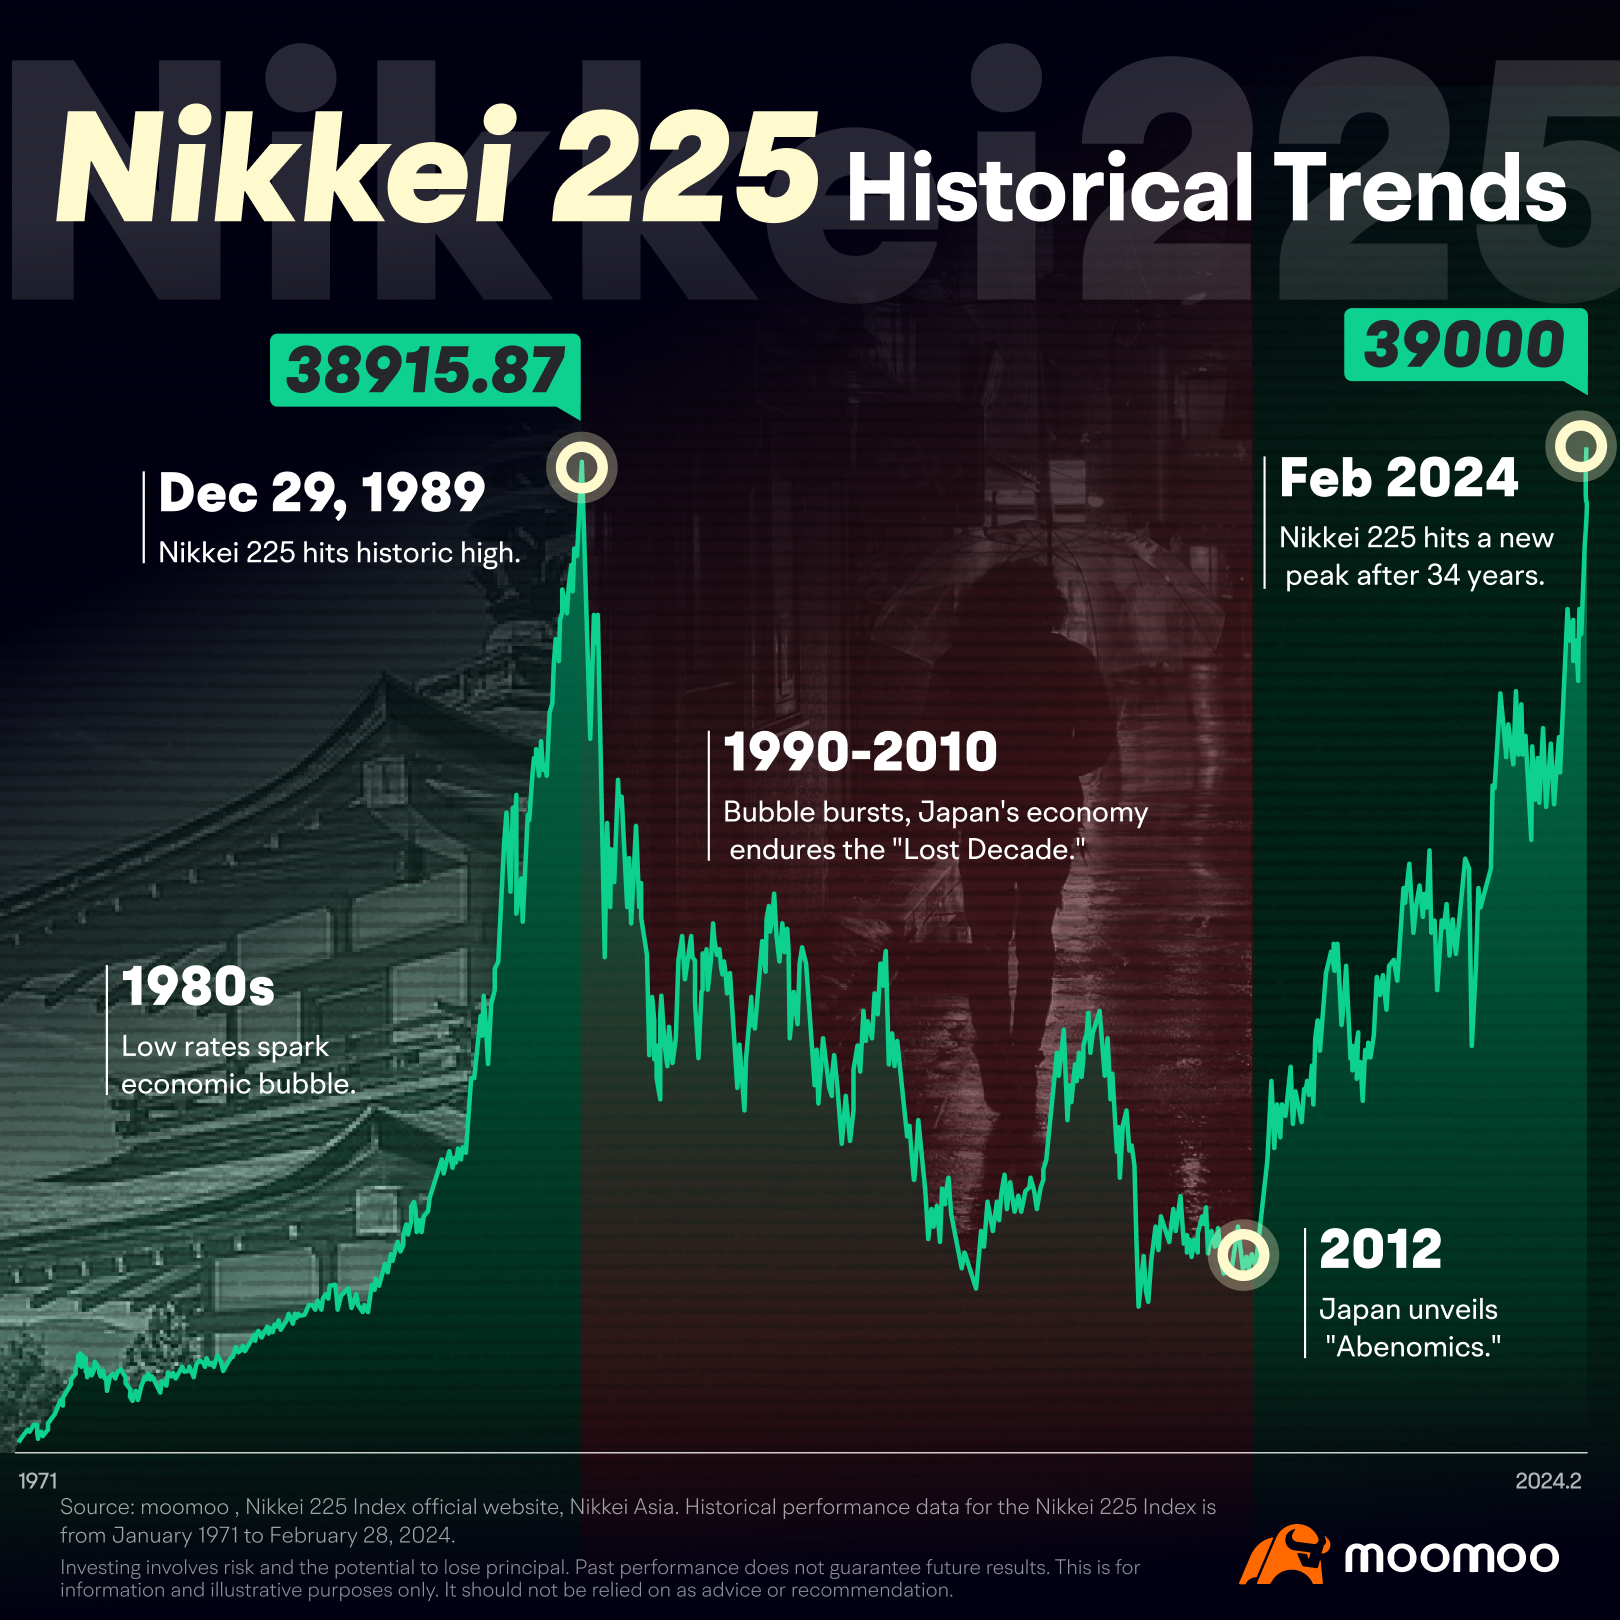
The Nikkei peaked at nearly 39,000 in December 1989 during the bubble economy. It took until 2024 for the index to reclaim that level, which is 34 years. This is the longest bear market in the history of major equity indices. Most textbooks skip over the details of what happened during the lost decades, so let me be blunt: the Nikkei didn't just stagnate. It went through multiple false recoveries, sector rotation crises, and currency shocks that made timing extremely difficult even for professionals. The yen's role in this story is often overlooked. When the yen strengthens, the Nikkei tends to underperform for Japanese exporters, who make up a large portion of the index. A 10 percent yen appreciation typically drags the index down 5 to 8 percent over the following quarter, depending on global risk sentiment. I've used yen forward contracts to hedge this exposure, and it works well when the move is predictable. When it's not, you're just paying premium for protection. I remember trading through the 2008 financial crisis. The Nikkei dropped from around 12,000 to below 7,000 in three months. Most retail investors panicked and sold at the bottom. I held through because the price-weighting meant that some of the hardest-hit stocks were the ones with lower share prices, which actually reduced the index's downside relative to a market-cap-weighted equivalent. This is a counter-intuitive point that rarely comes up in analysis, but it mattered significantly during that drawdown.
Practical Considerations for Investors
If you're considering Japanese equities, the currency risk is the dominant factor for foreign investors. The Nikkei can rise 20 percent in yen terms and still deliver a negative return in dollars if the yen falls 25 percent against the dollar. I've seen this happen multiple times. The yen has ranged from roughly 75 to 160 against the dollar over the past 40 years, and each extreme move creates significant headwinds or tailwinds for unhedged investors. The valuation gap between Japanese and global equities has narrowed considerably since 2023. The Nikkei's forward P/E is now around 15 times earnings, compared to 12 times for the S&P 500. This compression reflects improved corporate governance, shareholder returns, and structural reforms under the Tokyo Stock Exchange's pressure on companies to improve capital efficiency. It's not cheap by historical standards, but it's not overvalued if you believe the earnings growth trajectory holds. I recommend allocating no more than 5 to 10 percent of a diversified portfolio to Japanese equities unless you have a specific thesis about yen strength or Japanese structural reforms. The correlation with global risk assets has increased to around 0.7 over the past decade, which means Japan is no longer the diversification play it once was. If you want emerging market exposure, India or Vietnam offer better growth prospects with lower correlation to developed markets. I've adjusted my allocations accordingly.
Where to Find Reliable Data
For real-time quotes and historical data, the Tokyo Stock Exchange website provides official figures, though the interface is dated and slow. Bloomberg Terminal and Refinitiv Eikon are faster but require subscriptions. For free sources, Yahoo Finance offers Nikkei 225 data with decent historical depth, though the dividend adjustment methodology isn't always transparent. I use a combination of Yahoo for quick checks and a proprietary database for backtesting. The Nikkei 225 constituent list changes approximately twice a year during the regular review, usually in June and December. Companies are added or removed based on market cap, liquidity, and listing status. I track these changes because they can create short-term buying or selling pressure as index funds rebalance. The impact is typically 1 to 2 percent of daily volume for the affected stocks, which creates a small but predictable arbitrage opportunity for those willing to execute the trades. If you want to download historical data for backtesting, most platforms offer CSV exports. The data is generally clean from 1990 onward, though pre-1990 figures are sparser and may require manual verification against published annual reports. I spent a week verifying 1980s data against microfilm copies of the Nikkei Daily News when I was building an early model, and let me tell you, the digitization effort was worth it. The discrepancies between sources were significant enough to affect strategy conclusions.
The Bottom Line
The Nikkei 225 remains the most widely followed Japanese equity benchmark, but it has limitations that casual observers miss. The price-weighting creates mechanical distortions. The sector concentration skews risk exposure. The currency component dominates returns for foreign investors. Understanding these factors separately from the headline index level is what separates informed allocation from guesswork. I've been wrong about Japan multiple times, usually because I overestimated the impact of structural reforms or underestimated yen volatility. The recent outperformance since 2023 is real, but it came after three decades of underperformance that tested every investor's conviction. If you're entering now, size the position appropriately and hedge the currency unless you have a strong view on yen direction. That's the practical takeaway from 30 years of watching this index.