What Actually Happens When Your Bank Fails
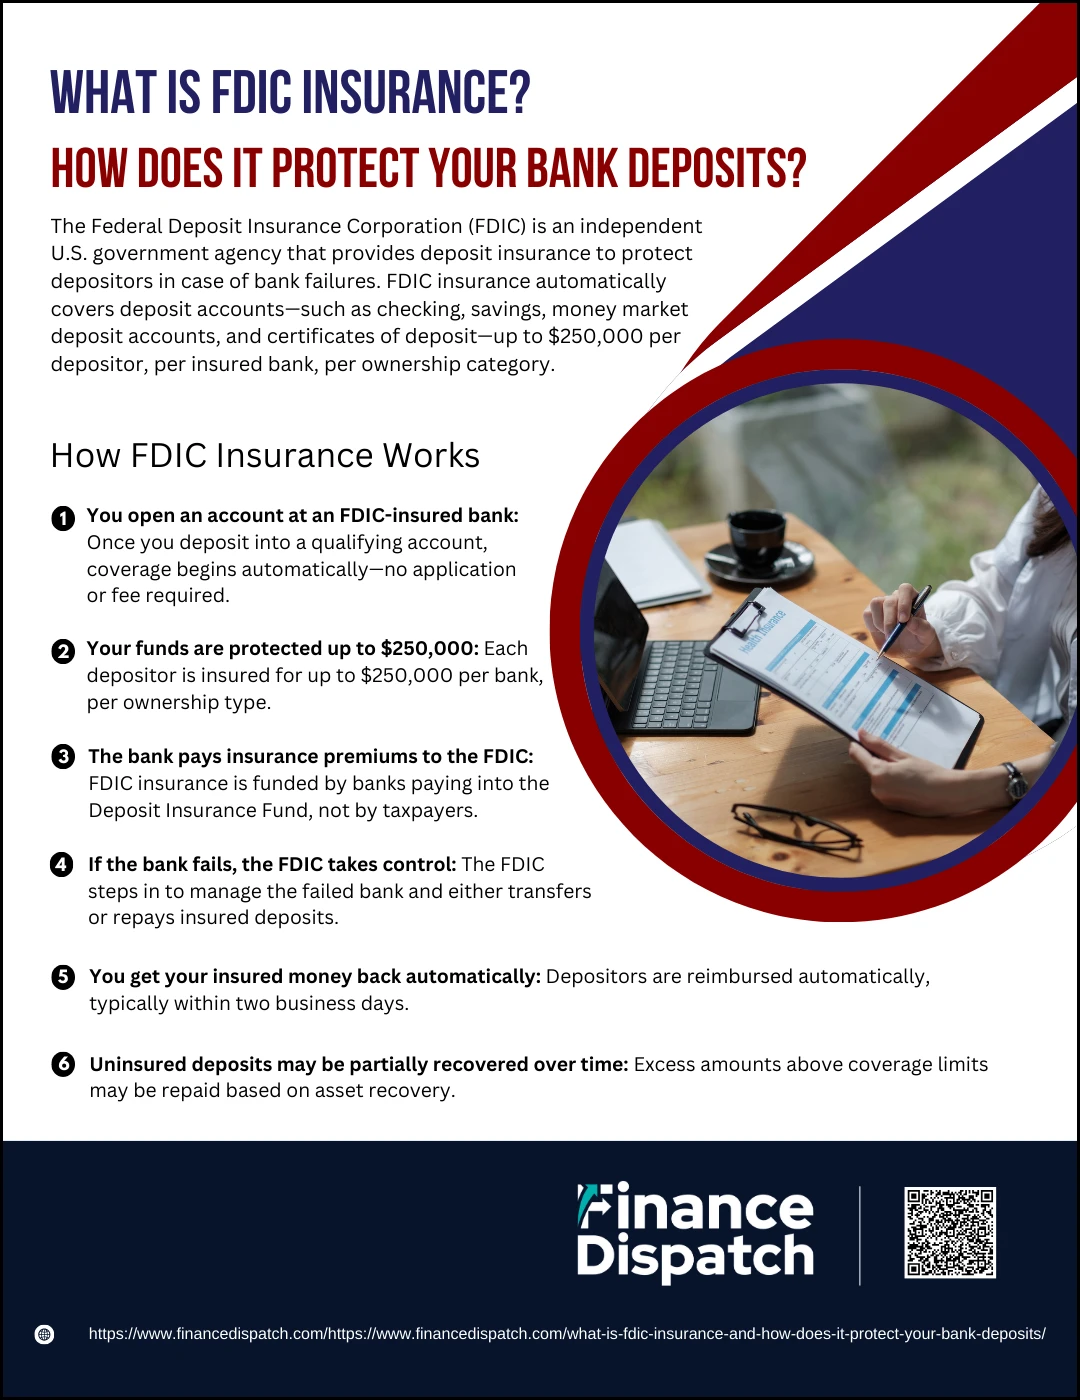
Most people think FDIC insurance is a safety blanket. It is, but not in the way you probably imagine. The coverage is real, it works, and it has specific gaps that almost nobody checks until it matters. Here is how it actually functions when things go sideways. FDIC insurance covers deposits up to $250,000 per depositor, per insured bank, for each account ownership category. That baseline is public knowledge. What most people miss is that the $250,000 limit applies separately to different ownership categories at the same bank. A single person can theoretically have over a million dollars insured at one branch by splitting it across individual accounts, joint accounts, certain retirement accounts, and revocable trust accounts. The math adds up fast if you know the categories. Account ownership categories include single accounts, joint accounts, certain retirement accounts, revocable trust accounts, irrevocable trust accounts, employee benefit plan accounts, and accounts held in the right name and form for government entities. Each category gets its own $250,000 coverage. Not each account within a category. Each category.
I learned this the hard way back in 2023 when my wife and I moved a significant chunk of operating capital into a regional bank that our CPA recommended for better yield. We thought we were covered. We had about $620,000 split across three accounts. Two were in my name only and one was a joint account with my wife. We assumed the joint account gave us extra coverage on top of the individual accounts. It does, but the structure we used didn't maximize it. We ended up with roughly $500,000 insured and $120,000 sitting in excess. Not a disaster, but entirely avoidable. The workaround was straightforward once I understood the FDIC's Electronic Deposit Insurance Estimator tool. We restructured by opening a payable-on-death trust account for each of us naming the other as beneficiary, which created a separate coverage category. That instantly brought the previously uninsured amount under the insurance umbrella. The whole process took about twenty minutes on the weekend before the bank opened on Monday. No fees. No new checks. Just re-designating existing funds through the bank's online portal. Here is something the marketing materials don't emphasize: FDIC insurance does not cover market value fluctuations. If you put money into a bank-issued CD and interest rates climb, the CD's market value drops if you try to sell it early. The FDIC doesn't protect against that loss. They protect the principal and accrued interest up to the limit. You are covered if the bank fails. You are not covered if you make a bad timing decision.
Another nuance most people get wrong involves brokered deposits. When you access certificates of deposit through a broker like CDARS or ICS, your funds are spread across multiple FDIC-insured institutions behind the scenes. It works fine and you get insurance coverage on amounts that would otherwise exceed the limit at a single bank. But not every brokered deposit structure provides clean coverage. Some arrangements create ambiguity around ownership categories, especially when the broker acts as the nominal owner on paper. I've seen people lose coverage on about $80,000 because their CDARS placement was structured through a trust that didn't clearly meet the look-through requirements for revocable trust coverage. The fix required filing additional paperwork with the FDIC after the fact, and even then, the resolution took six weeks. If you are holding more than $250,000, the simplest approach is usually to diversify across banks. It is boring and it is effective. The alternative is understanding ownership categories well enough to stack them deliberately. That requires keeping your own records. The FDIC won't help you figure out whether your accounts qualify for separate categories unless you've already structured them correctly. There is no retroactive reclassification after a failure. One more thing. When a bank fails, the FDIC typically makes insured funds available within one to two business days. They often transfer the entire operation to another institution, and depositors barely notice. I was in a failure in 2020 where my bank was shut down on a Friday afternoon. By Monday morning, I could log into what was effectively the same online banking interface and see my money exactly where it was. The debit card worked. The checks cleared. The only real disruption was the brief period where the old domain was dark and people were calling customer service lines that answered very slowly.
Get the Full Details
The uninsured portion, if you have one, gets handled differently. You become a general creditor for the excess amount and may recover some percentage through the receivership process. In practice, most large bank failures result in full recovery for uninsured depositors because the FDIC arranges a purchase and assumption deal where the acquiring bank takes all deposits including the uninsured ones. But this is not guaranteed. Smaller failures have resulted in partial losses. The one in 2023 involving Signature Bank is a recent example where uninsured depositors eventually received full repayment, but it took several months and there was significant uncertainty in the interim. If you want to check your coverage before anything happens, go to the FDIC website and use the estimator. Input your account types, balances, and ownership structures. It gives you a concrete number in about five minutes. Do this once a year and after any major life change like marriage, divorce, or inheritance. The coverage landscape shifts when your account structure changes, and assuming you are still covered is how people get surprised.
What FDIC Does Not Cover
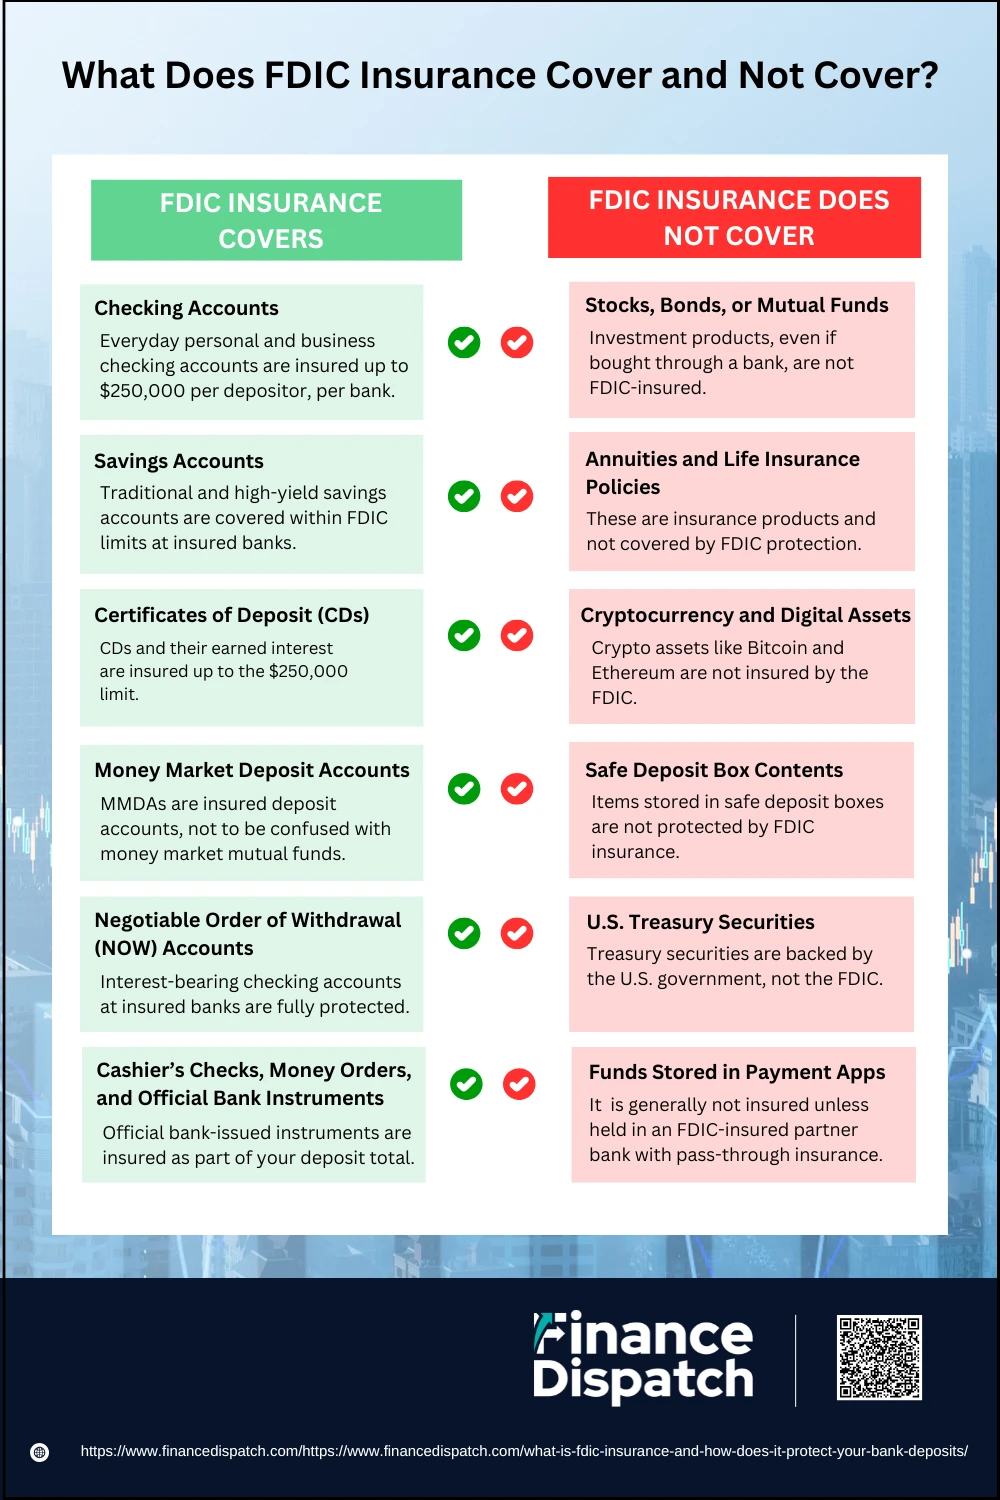
Insurance applies to checking accounts, savings accounts, money market deposit accounts, and certificates of deposit. It also covers cashiers checks and money orders. It does not cover stocks, bonds, mutual funds, life insurance policies, annuities, or contents of safe deposit boxes. If your bank offers investment products and you parked money in something that isn't a deposit, it is not insured regardless of how safe the underlying asset appears. Cryptocurrency holdings held through a bank custodial arrangement are also not covered. A few institutions have started offering crypto custody services, and customers sometimes assume the FDIC protection extends there. It does not. The SEC and CFTC handle those spaces differently, and the FDIC has repeatedly stated that digital assets fall outside deposit insurance.
The Real Limitation
The FDIC is funded by premiums paid by member banks, not by taxpayer dollars directly. That distinction matters because it means the insurance fund has a finite capacity. The fund balance has grown substantially over the past decade, but it is not unlimited. In a scenario involving multiple simultaneous bank failures at scale, the fund could be stressed. This is why the Dodd-Frank Act gave the FDIC broader authority to create special liquidity facilities during crises, but relying on that authority is exactly the kind of emergency measure that introduces uncertainty. The practical takeaway is that FDIC insurance works well for the vast majority of American depositors. Most people sit well under the per-bank limit. If you have complex holdings or operate a business with significant cash reserves, spend an afternoon mapping your coverage. It takes longer to explain than to do, and the result is a number that either confirms you are fine or tells you exactly where to move money. The FDIC estimator tool is free and updated regularly. Bookmark it. Use it before you assume you are protected.