Illinois Payroll: What Actually Happens When You Run It
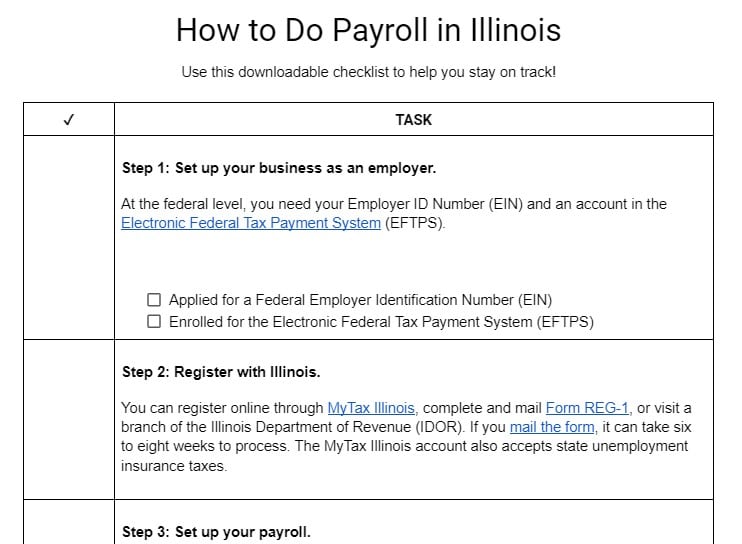
Illinois payroll is one of those things that sounds simple on paper and quietly breaks your week when you get it wrong. The state doesn't have a single unified filing portal, which means your team will spend more time navigating government websites than actually processing payroll. I learned this the hard way when I was running a multi-location setup with employees in Chicago, Naperville, and Springfield at the same time. Illinois withholds state income tax at a flat rate of 4.95% as of the current fiscal year. That part is straightforward. What trips people up is that the flat rate only applies to the state level. Local jurisdictions stack on top, and Chicago alone sits at roughly 1.6% to 2.4% depending on where the employee lives, which makes the effective combined rate climb past 6.5% for some workers. You register with two agencies, not one. The Illinois Department of Employment Security (IDES) handles unemployment insurance and new hire reporting. The Illinois Department of Revenue (IDOR) handles income tax withholding. If you have employees working in Chicago, you register separately with the City of Chicago Office of Finance for municipal tax withholding. That's three separate logins before you process a single paycheck.
Unemployment insurance in Illinois operates on a experience-rated system. Your contribution rate depends on your industry, workforce size, and layoff history. New employers start at a mandatory minimum of 2.25% on the first $15,900 of each employee's annual wages. Experienced employers see rates between 2.25% and 8.47% depending on their reserve ratio. The taxable wage base resets every calendar year. You pay UI on the first $15,900 per employee, no matter how much they earn above that.
Filing Requirements and Deadlines
State withholding tax returns are filed quarterly using the IDOR Illinois Withholding Tax Return (IL-927). The due dates are April 30, July 31, October 31, and January 31. If you owe over $500 in any quarter, you're required to make semi-weekly electronic deposits. That means Wednesday and Friday deposits for the following week's liability. Missing a deposit deadline carries a penalty of 5% per month or part of a month, up to 25%. Unemployment insurance quarterly reports go through IDES using the UCUI Form 145. The deadlines align with the calendar quarters and are due the last day of the month following each quarter. Here's a detail most guides miss: IDES accepts both paper and electronic filing, but if your quarterly UI tax liability exceeds $500, electronic filing becomes mandatory. Paper filings for large employers get rejected outright now. New hire reporting in Illinois must be submitted within 20 days of the employee's start date. You report through the Illinois New Hire Reporting Center, which is a free online system. Failing to report new hires can result in fines up to $500 per violation. I've seen small businesses get hit with cumulative fines because they treated new hire reporting as optional. It isn't optional.
Get the Full Details

The Chicago Local Tax Complication
This is where Illinois payroll gets genuinely annoying. If your employees live or work in Chicago, you withhold an additional local tax at a rate determined by the employee's municipality of residence. The city maintains its own withholding schedule and requires separate quarterly filings. Chicago employers file Form U-TIL on a monthly or quarterly basis depending on their liability volume. The practical problem is that your payroll software needs to map each employee's address to the correct municipal rate. Not every suburb has a local tax. Cook County suburbs like Naperville and Aurora don't. But places like Evanston and Oak Park do, and the rates differ. I once had an employee who moved from a no-tax suburb to Evanston mid-quarter, and our payroll system didn't catch the rate change until the quarterly filing window closed. The fix involved pulling the employee's W-4 equivalent (the IL-RFW-1 form) and manually updating the withholding code in the system before resubmitting. Chicago also imposes a separate employer-side tax called the Chicago Business Personal Property Tax Replacement Tax, which some employers conflate with withholding obligations. It's not. Don't mix them up. They're tracked independently.
Illinois Paid Leave and Other Required Deductions
Illinois requires employers to provide Paid Leave for all Workers under the Prevention of Fraudulent Use of Leave Act. Eligible employees accrue one hour of paid leave for every 40 hours worked, up to 40 hours per year. Employers must provide notice of this right and cannot retaliate against employees who use it. Tracking this on top of federal FMLA and any local paid sick leave ordinances adds another layer of complexity to your payroll run. Workers' compensation insurance is mandatory for any business with one or more employees. This isn't withheld from wages. It's a separate premium paid by the employer based on classification codes and payroll volume. The Illinois Workers' Compensation Commission oversees this. Rates vary wildly by industry. An office employer might pay under $0.50 per $100 of payroll. A roofing contractor could pay $8 or more per $100. The health care licensing fund assessment applies to employers in the health care industry. This is a separate quarterly remittance to IDOR and isn't part of standard payroll deductions. It's calculated based on the employer's gross receipts from health care services.
A Real Problem I Ran Into and How I Fixed It
During a payroll migration from a legacy system to a modern platform, I encountered a situation where three employees had combined Chicago and suburban addresses that the new system couldn't resolve correctly. Their withholding calculations came out approximately $40 short per paycheck in combined state and local taxes. Over a full quarter, that translated to underpayment penalties and interest that cost us roughly $200 beyond the original tax shortfall. The workaround was deliberate and boring. I pulled each employee's IL-RFW-1 form, verified their residence address against the official Chicago municipal tax boundary map maintained by the City Clerk's office, and manually entered the correct municipal codes into the payroll system. Then I ran a side-by-side reconciliation comparing the new system's calculated withholding against the old system's output for two complete pay periods. Once the numbers matched within a dollar, I filed amended quarterly returns for the affected period. The IDOR website allows you to submit amended withholding returns through their online portal, but you have to select the correct amendment reason code or the system rejects the submission.
Common Pitfalls That Cost Money
First, assuming the 4.95% flat rate applies uniformly. It doesn't. Local taxes stack on top and the rates vary by municipality. Every employee's residential address matters for accurate withholding. Second, missing the semi-weekly deposit requirement for withholding taxes exceeding $500 per quarter. The IRS-style deposit schedule in Illinois is aggressive. If you're on the semi-weekly schedule and miss a Wednesday deposit because it fell on a holiday that shifted to Thursday, your Friday deposit is still due on Friday. The state doesn't automatically shift your schedule. You have to verify the deposit calendar each period. Third, treating Illinois new hire reporting as something you can batch monthly. The 20-day rule is strict. Some states give you 30 days. Illinois gives you 20. If you hire someone on the 1st of the month and forget until the 20th, you've already violated the deadline.
Fourth, not reconciling your quarterly withholding remittances against your actual payroll records before filing. I've watched payroll managers submit the quarterly return, see the numbers look close enough, and move on. The difference between "close enough" and "correct" is what determines whether you get a notice in 90 days or never hear anything. Run the reconciliation. Always.
What Illinois Payroll Software Should Handle
Any competent system should automatically calculate the 4.95% state rate, layer on the correct municipal withholding based on employee residence, generate the IDOR and IDES forms pre-populated, maintain the new hire reporting timeline with reminders, track paid leave accruals, and produce a quarterly summary that matches your general ledger. If your software doesn't do at least four of those six things natively, you're going to spend more time on compliance work than on actual payroll processing. The Illinois Department of Revenue publishes the current withholding tax tables at ilrev.gov. The IDES employer portal at ides.illinois.gov handles UI filings. Both require separate accounts with separate credentials. Set up both on day one before your first payroll run. Trying to register while your first paycheck is due is a reliable way to lose a full business day.