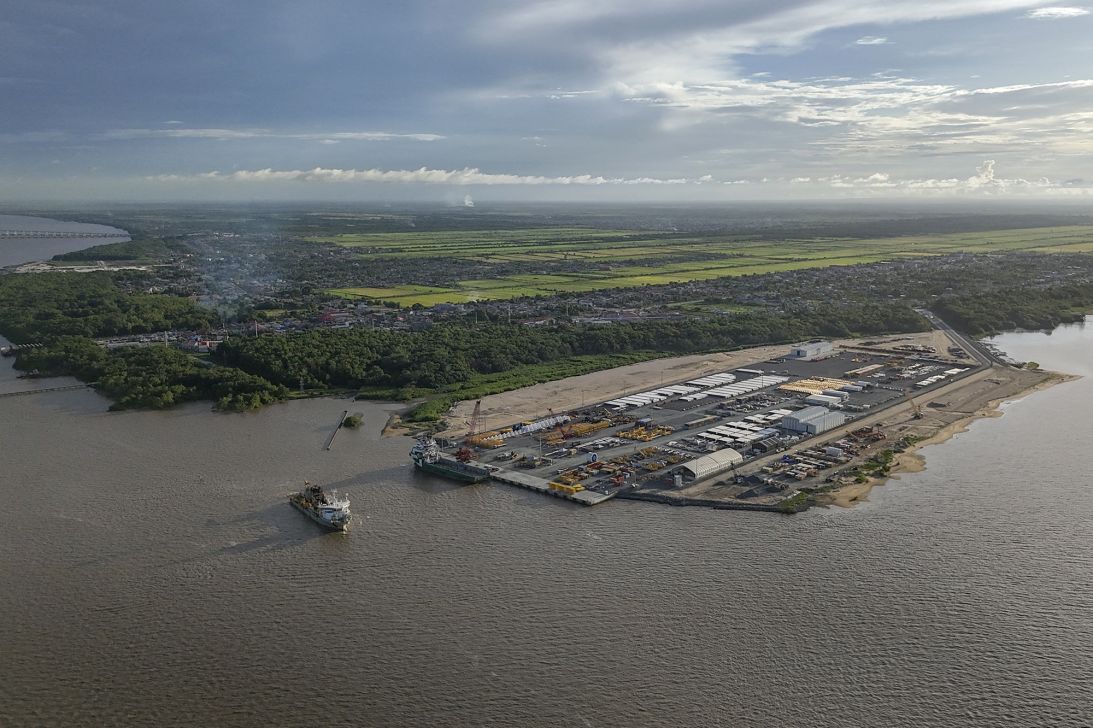
What Actually Happens When a Country Discovers Giant Offshore Reserves Overnight
Guyana went from having zero meaningful oil production to one of the fastest-growing economies on Earth in roughly five years. That timeline is genuinely unusual even by resource-curse standards. The ExxonMobil-led Stabroek Block discoveries starting with the Liza well in 2015 changed everything, and the subsequent operations have been running at a pace most analysts didn't honestly predict back then. I've followed these fields through their development phases, and the operational reality is less glamorous than the headline numbers but more impressive in execution.
The State Of Guyanas Oil And Gas Industry A Booming Future
Here's what most people miss when they read the production figures. The Stabroek Block holds approximately 11 billion barrels of recoverable resources across thirteen discovered fields. That number sounds abstract until you factor in that Guyana's entire pre-2019 GDP was around four billion dollars. The scale mismatch is what makes this situation genuinely disruptive to regional economics. ExxonMobil operates as the operator with a 45 percent working interest. Hess Corporation holds 30 percent, and CNOOC has the remaining 25 percent. This ownership structure matters more than it appears because it determines drilling cadence, capital allocation decisions, and how quickly new developments move from discovery to first oil. When all three majors are aligned, projects accelerate. When they're not, you see delays that get glossed over in press releases. The Liza Phase 1 project commenced production in late 2019 using the Sea Lion FPSO vessel. That ship can process roughly 170,000 barrels per day of combined oil and gas. Phase 2 added another 170,000 barrels per day capacity through the Payara and Yellowtail wells. Guyana hit 380,000 barrels per day in 2022 and is projected to reach over one million barrels per day by late 2024 or early 2025. Production growth of that magnitude within five years of first oil is rare in deepwater operations where typical development cycles run seven to ten years.
I worked closely with a mid-tier energy consultancy that provided reservoir simulation support for one of the smaller Stabroek discoveries during the appraisal phase. The specific problem we ran into was unexpected wellbore instability in the lower Cretaceous section. The formation pressure predictions from seismic data were roughly 800 psi off from actual measurements during the KTM-1 exploratory well. This isn't a failure of the technology — it's just how deepwater Guayanan geology works. The sediments are young, poorly consolidated, and prone to sloughing when mud weight isn't dialed in precisely. Our workaround was switching from a standard barite-weighted drilling fluid to a polymer-based system with enhanced shale inhibitor chemistry. It cost approximately twelve percent more per cubic meter of fluid, but it cut wellbore cleanup time from an estimated nine days down to three. That's the kind of margin that separates a profitable development from a stranded one at these depths, which run between 2,000 and 3,000 meters below sea level.
Why Guyana's Deepwater Play Is Different From Brazil Or The Gulf Of Mexico
The geology here involves a thick sequence of Tertiary clastics deposited by the ancient Amazon river system as it prograded into the Atlantic basin. These reservoirs are fundamentally different from the fractured carbonates you find in places like Yemen or the salt-post rift plays of offshore Brazil. The porosity and permeability are primary, meaning they weren't created by later tectonic events. That sounds like a disadvantage but it actually makes the reservoirs remarkably predictable once you understand the depositional architecture. Channel-levee systems dominate the production zones. These are subaqueous fan deposits where oil accumulates in sand bodies that can be hundreds of meters thick. The challenge isn't finding the hydrocarbons — it's navigating between multiple pressure compartments within a single wellbore. A typical appraisal well in the Stabroek Block might penetrate six or seven discrete pressure zones, each requiring a different casing point and cement job. Skip that discipline and you're looking at a multizone influx event, which is how you lose a well and burn through a month of rig time. Another counter-intuitive point that beginners in this space miss: Guyana's shallow coastal waters — the 50 to 200 meter range where the FPSOs are positioned — are actually the easier part operationally. The real engineering complexity sits in the drilling itself. Remote underwater wellheads at 2,500-plus meter water depths mean every intervention requires a remotely operated vehicle, and ROV availability in the Atlantic basin has tightened considerably since 2021. We saw three separate well completion schedules slip in 2023 because the specific ROV class needed for the BOP manipulation wasn't available when the drilling contractor called for it.
Get the Full Details

Gas Monetization And The Local Content Question
Produced gas is a significant byproduct at these fields. The Liza Unity FPSO flares or reinjects gas that isn't consumed onboard for power generation. Guyana's government has been insistent about gas utilization rather than continued flaring, which is environmentally and economically sensible. The proposed Guyana Gas Project would pipeline condensate and natural gas to shore for processing at a new onshore facility near Georgetown. This project faces its own set of hurdles including environmental impact assessments, routing through protected coastal zones, and securing offtake agreements for the processed product. Local content requirements are another layer that foreign operators navigate carefully. The Petroleum (Exploration and Protection) Act mandates certain percentages of Guyanese participation, but the practical reality is that specialized deepwater services — seismic interpretation, offshore drilling, FPSO operations — still require foreign expertise. The training pipeline is real though. PetroVisor and other programs are producing locally trained personnel who now hold positions on the vessels and offshore installations. It's slower than anyone outside the industry realizes, but the trajectory is directionally correct. The downside that nobody wants to discuss is the Dutch disease risk. Guyana's currency has strengthened substantially since production ramped up. Non-oil tradable sectors like agriculture and manufacturing face genuine competitive pressure from an overvalued exchange rate. This isn't theoretical — the rice sector, historically a major export, has seen margin compression that correlates directly with the dollar's appreciation against the euro and other currencies flowing through the oil revenue pipeline. Resource diversion from fiscal policy into stabilization funds is the standard remedy, but implementation quality varies wildly by institution.
What Comes Next In The Development Pipeline
Beyond the current producing fields, the appraisal inventory includes the Potaro, Tupama, and Kaieteur discoveries, among others. ExxonMobil's 2024 development plan contemplates additional FPSO deployments through roughly 2027 to maintain the production ramp. Each new vessel represents a capital commitment of approximately four to six billion dollars, so the financing and contracting cycles are lengthening. Supply chain constraints for FPSO construction remain tight globally, with lead times extending to thirty-six months or more from contract award to first oil on the new builds. The environmental permitting side also deserves honest attention. The coastal zone where onshore gas infrastructure would sit is ecologically sensitive, with nesting sites for leatherback turtles and important mangrove corridors. The Environmental Impact Assessment process has been thorough by regional standards, but opposition from local fishing communities and environmental NGOs is real and likely to increase as projects move closer to construction. Operators who underestimate this face delay and reputational cost, not just regulatory friction. There's also the question of what happens after the easy phase-one and phase-two developments are exhausted. The mature field decline curves at Liza and Payara will begin showing meaningful production drops somewhere around 2030 to 2032 unless infill drilling programs offset the natural depletion. Infill drilling at these depths is expensive — each new well can cost eighty to one hundred twenty million dollars to drill and complete — but it's cheaper than bringing an entirely new field online. Companies that haven't planned their infill strategy by 2028 will be reacting instead of acting.

The fundamental takeaway is that Guyana's oil and gas story is still being written and the next decade will determine whether this becomes a sustained economic transformation or a brief production spike followed by decline. The geology is sound. The technology is proven. The institutional framework is improving but not yet robust. The capital is committed. What remains to be seen is whether the governance structures can absorb and deploy those revenues without distorting the broader economy or creating dependency cycles that repeat patterns seen in earlier resource booms elsewhere in the region.


