What Actually Happened With Social Security in 1935
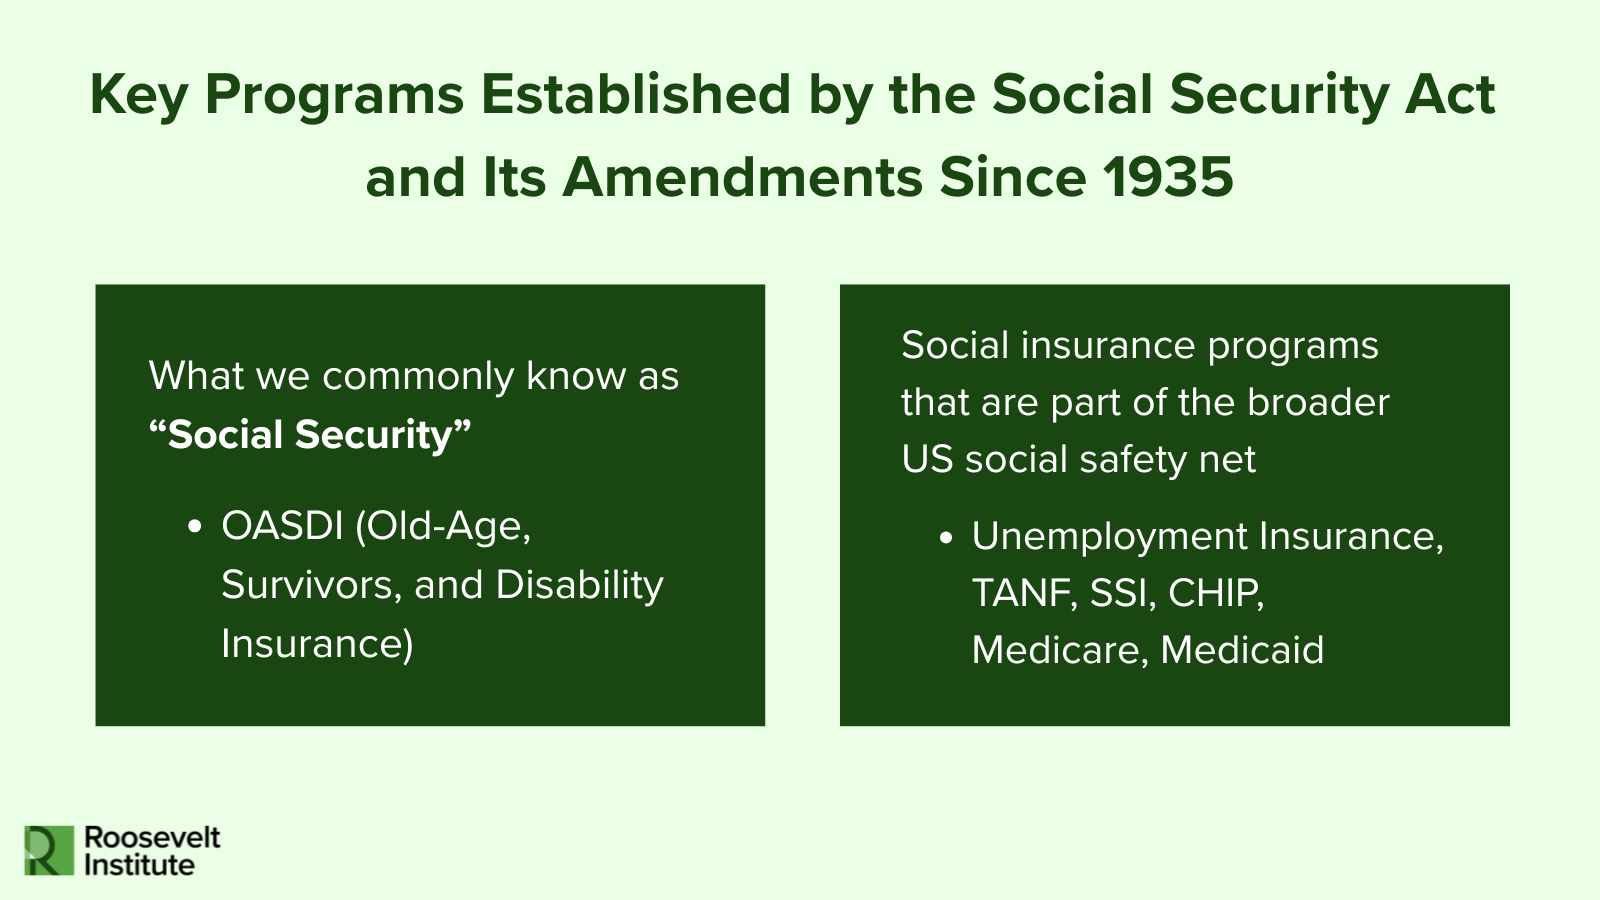
The Social Security Act was signed into law on August 14, 1935. It wasn't some sudden miracle that fixed everything overnight. It was a complicated piece of legislation that created the foundation for how Americans now handle retirement, disability, and welfare support. The original act had seven titles, and only some of them became what people now call "Social Security" in the everyday sense. Most people think Social Security just means retirement checks. That's Title II of the original legislation. But the full act also created Aid to Dependent Children (Title IV), which eventually became AFDC and then TANF. It established federal unemployment insurance (Title III). It funded maternal and child health services (Title VI). The original act was a basket of programs, not a single program. Here's what nobody emphasizes enough: the old-age insurance program didn't start paying benefits until 1940. There was a five-year gap between when the program was funded and when anyone actually received a check. The first monthly benefit went to Ida May Fuller, who had worked three years in the textiles industry. She received 22 cents per month for a decade starting in 1940. She'd paid $24.75 into the system total. She lived another eighteen years past that and collected about $22,889 in total benefits.
The financing structure is probably the most misunderstood part. FICA taxes are split between employer and employee at 6.2 percent each for the OASI portion and 1.45 percent each for Medicare. Self-employed people pay both shares, which comes to 12.4 percent for Social Security and 2.9 percent for Medicare. This isn't a voluntary insurance program in any meaningful sense. It's mandatory payroll taxation with benefit formulas attached. I spent years helping people navigate the actual mechanics of the system after it was built, and the thing that always surprises clients is how disconnected the tax history is from the benefit calculation. Your benefit is based on your thirty-five highest-earning years, indexed for wage inflation. If you worked only twenty years, the remaining fifteen slots count as zero. This penalizes career interruptions heavily, and career interruptions disproportionately affect women and people who provided unpaid caregiving. The system treats a parent who stayed home for twelve years the same as someone who earned minimum wage for twelve years. There's a common misconception that Social Security is solvent forever because the trust fund exists. The truth is more mechanical. The Old-Age and Survivors Insurance Trust Fund holds surplus reserves, currently around $2.9 trillion. The actuaries project it will be depleted around 2033 under current law. After that, ongoing tax revenue would cover roughly 75 percent of scheduled benefits. This isn't a cliff. Benefits wouldn't disappear. They'd be reduced to what current payroll taxes can support unless Congress acts. The alternative to automatic reduction is an across-the-board cut or a tax increase, neither of which is politically popular.
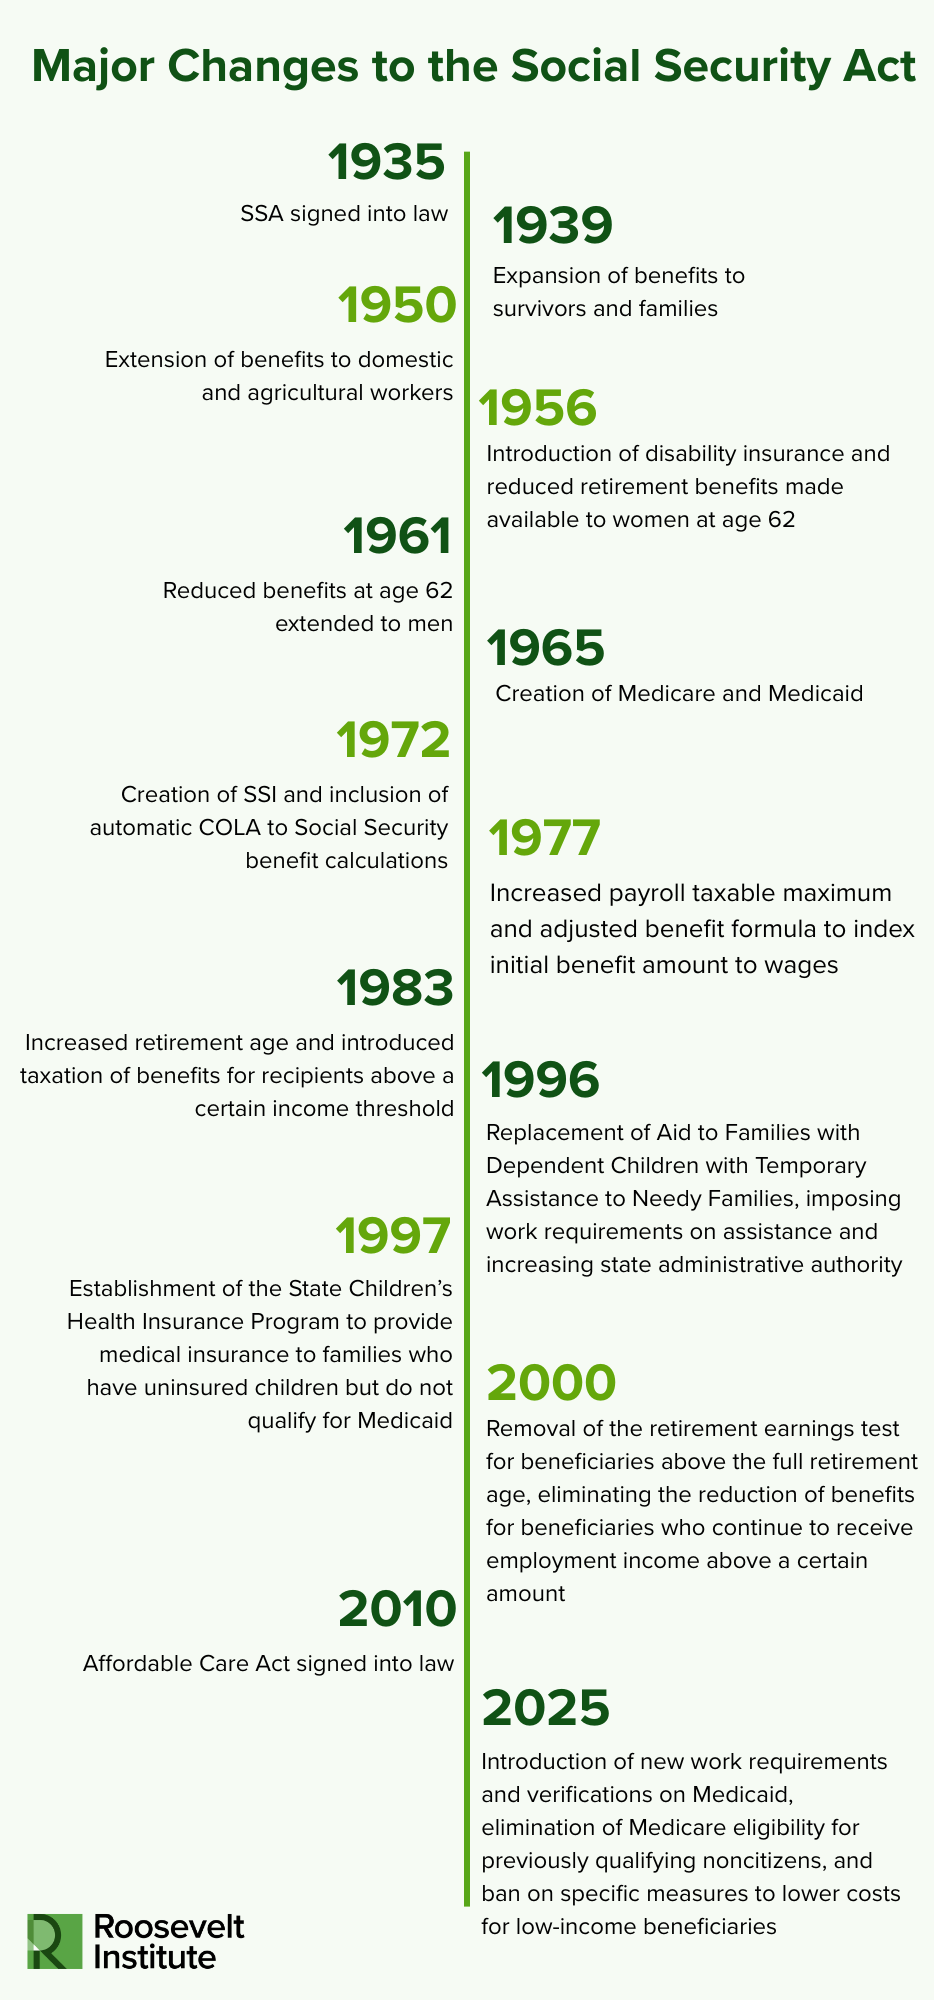
The program underwent significant changes in 1977 and 1983. The 1977 amendments changed how benefits were calculated, shifting from a flat percentage model to a progressive formula that replaced a higher percentage of pre-retirement income for lower earners. The 1983 Greenspan Commission recommendations raised the retirement age gradually to 67 for people born in 1960 or later, taxed Social Security benefits for higher-income retirees, and brought federal employees into the system. These changes extended the solvency window by decades. No similar adjustment has been made since. One counter-intuitive detail about claiming strategy: filing early at 62 doesn't just reduce your benefit by 30 percent. The reduction is permanent and compounds across your lifetime. Someone who delays from 62 to 67 sees an 77 percent increase in their monthly benefit. Over a typical lifespan, the delayed filer often ends up ahead financially, but this depends entirely on health outcomes and family history. There's no universal right answer. The break-even point usually falls around age 78 to 80 depending on your specific benefit amount. The disability side of the act, Title XVI, operates on completely different rules than the retirement system. SSDI requires sufficient work credits, but the medical determination process is where people hit walls. The SSA maintains a list of impairments, but having a listed condition doesn't guarantee approval. The real bottleneck is the ability to perform any substantial gainful activity. If you're under the age of 50, the SSA assumes you can adjust to other work. This is where my experience becomes relevant. I encountered a case with a client who had severe arthritis affecting fine motor control. The medical records clearly documented the diagnosis, but the initial denial came because the ALJ found he could sedentary work. The workaround was introducing vocational expert testimony at the hearing level that the specific limitations in his case eliminated all sedentary options. The hearing decision reversed the denial. This kind of evidence strategy matters more than the raw medical documentation.
Get the Full Details
The survivor benefits under Title II are also undervalued. A surviving spouse can claim benefits as early as 60, or 50 if disabled. Children receive benefits until age 18 or 19 if still in high school. The lump-sum death payment of $255 is symbolic at this point, but it exists in the statute. Most people don't know they need to report a death within three months or face potential overpayment recovery. The earned income test is another area where people get tripped up. If you're below full retirement age and earning above the annual limit, your benefits get reduced by one dollar for every two dollars earned. In 2024, the limit was $22,320. The monthly approach applies in the year you reach full retirement age, where the reduction is one dollar for every three dollars above a higher threshold. Once you hit full retirement age, there's no earnings test at all. This creates weird incentives where people reduce their work hours artificially around their birthday month. Medicare Part A is included under Title XVIII and is automatically available to anyone who paid Social Security taxes for forty quarters. The premium-free Part A is what makes the broader system valuable beyond just the retirement check. Hospital insurance covers inpatient stays, skilled nursing facility care, hospice, and some home health. The Part B premium is income-adjusted through the IRMAA brackets, which catches a lot of middle-income retirees who assumed Medicare was flat-rate. The income-related monthly adjustment amounts can add hundreds of dollars per month to a Part B premium for higher earners.
The lasting structural impact is harder to quantify but more important than the monthly benefit amounts. Before 1935, there was no federal framework for elderly support. States handled poor relief locally, and private pension coverage barely existed outside of a few industries. The Social Security Act created a portable, lifelong benefit tied to work history that followed people across state lines. This portability was genuinely revolutionary for a country with high domestic migration rates. It also normalized the idea that the federal government had responsibility for economic security in old age. The program's coverage has expanded unevenly. Federal employees were added in 1983 but given a choice to opt out, and many systems opted into their own parallel retirement structures. Railroad workers have a separate but coordinated system under the Railroad Retirement Act. Public sector workers in some states remain excluded. The self-employed have always been covered, but compliance with self-employment tax payments is a persistent enforcement challenge that generates less public attention than it should. If you're dealing with an actual claim or benefit issue, the most useful resource isn't the website. It's the state-level SSA office and the local Field Representative. The online tools are accurate for basic calculations, but they can't handle edge cases involving periods of incomplete reporting, foreign work credits under totalization agreements, or complex spousal benefit scenarios. A specialist appointment at a field office typically takes twenty minutes and can resolve questions that would otherwise require weeks of online searching and form submissions.
The tax component stays constant regardless of economic conditions. Payroll taxes fund current benefits in a pay-as-you-go system with accumulated reserves. This means the program's health is directly tied to employment levels and wage growth. Periods of high unemployment create immediate pressure even when the trust fund reserves look adequate on paper. The 2008 recession demonstrated this clearly. Benefit payouts accelerated while contribution revenue dropped, and the trust fund drawdown that followed took years to stabilize. Looking at the long arc, the original 1935 framework has been amended roughly 175 times. Each amendment addressed a specific gap or equity problem. The 1950 amendments broadened coverage significantly. The 1972 amendments introduced cost-of-living adjustments automatically. The 1994 amendments created the SSI program consolidation. None of these changes fundamentally altered the core structure, which is why the system persists despite repeated solvency warnings. The basic architecture works, but the demographic pressures of an aging population and declining birth rates make the current trajectory unsustainable without further adjustment. The most practical takeaway for someone reading this is that the system rewards continuity and punishes gaps. If you have control over your work history, staying continuously employed and ensuring your wages are properly reported matters more than any claiming strategy or optimization trick. The benefit formula is transparent. The inputs are what determine the outputs. Understanding that relationship upfront saves far more time than trying to game the system after the fact.