Why Grant County Is Still Arguing About Water Bills
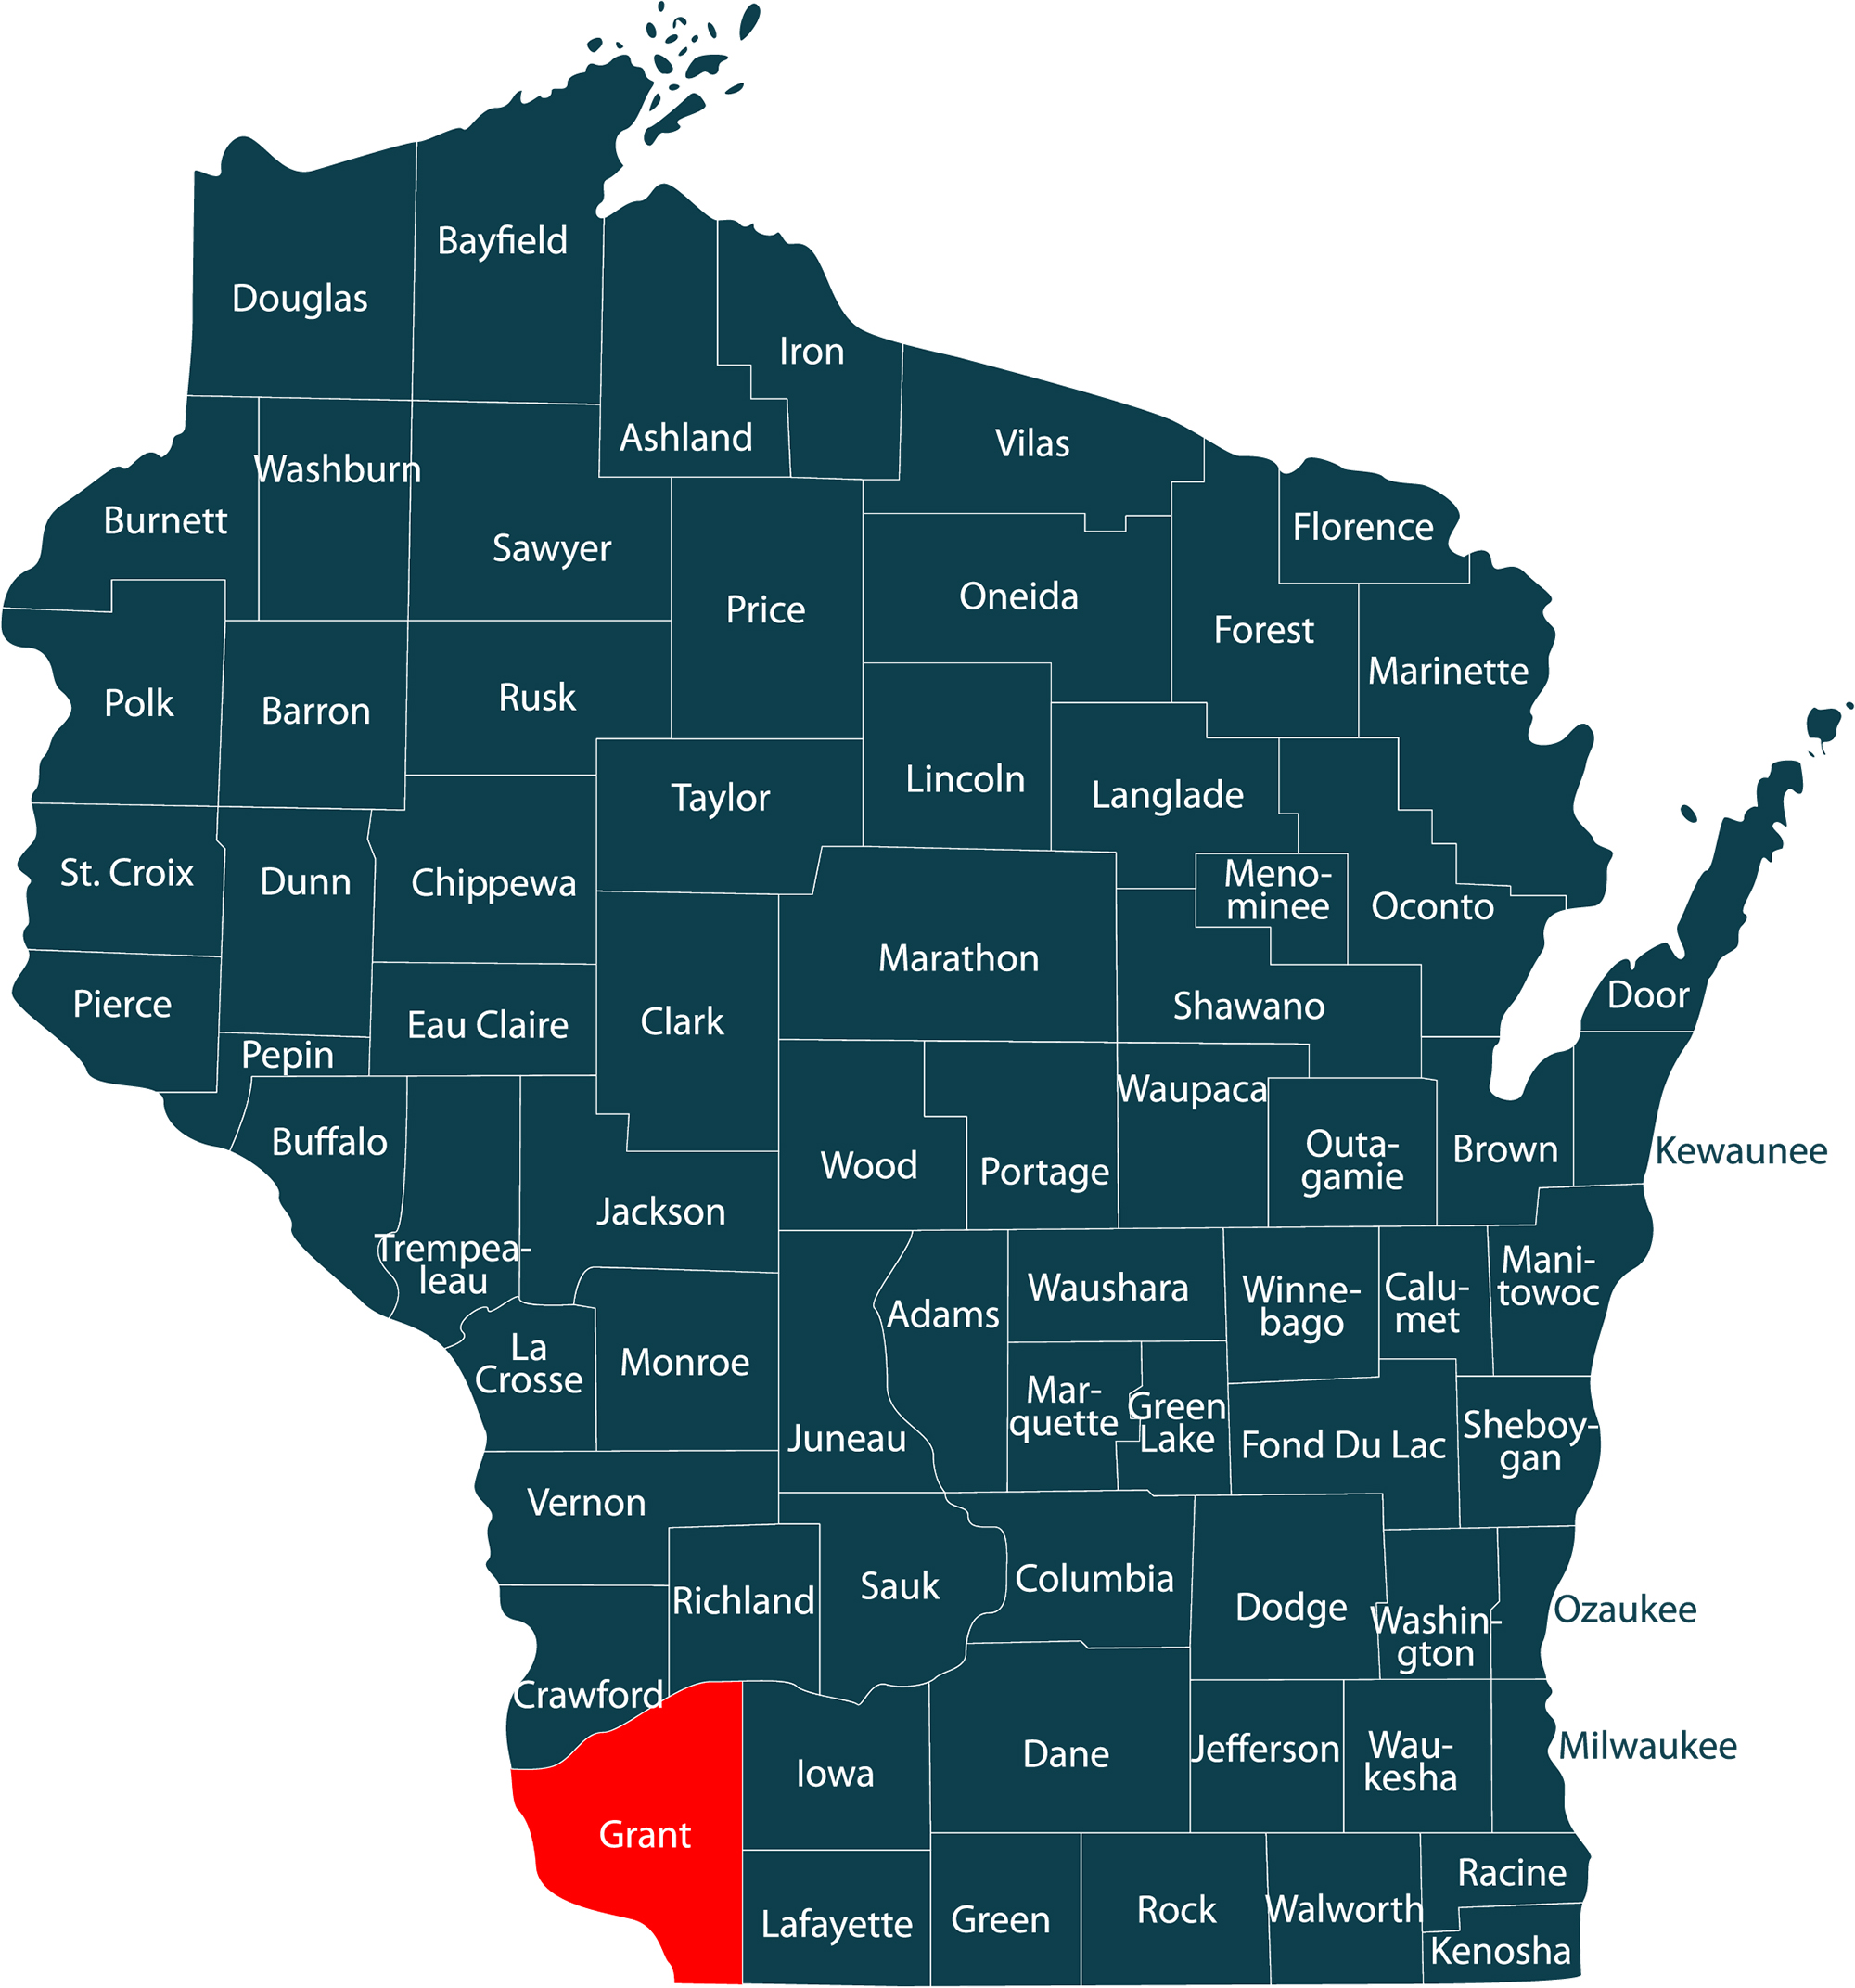
If you have ever sat through a Grant County Board meeting about municipal debt, you already know most of the story. The numbers are ugly, the options are worse, and the public is tired of being told it will get better in five years. I spent too many late nights last winter pulling bond documents and debt service schedules for towns around Lancaster and referred to them as smaller communities because that is how the county classifies them. What follows is a practical guide to understanding the situation, finding the records, and figuring out what is actually happening with the debt. The county has roughly two dozen municipalities dealing with some form of bonded debt or installment purchase obligation. That includes water and sewer systems, road improvements, and a few downtown redevelopment projects that still have outstanding principal. The county clerk publishes annual debt schedules, but they are not easy to read if you are new to municipal finance. The data is buried in meeting attachments that run forty pages or more. The best place to start is the Grant County Fiscal Analysis report, which appears every spring. It summarizes total indebtedness by municipality, shows debt per capita, and lists the largest individual obligations. You can find it on the county website under finance documents. I usually download the PDF, search for the specific municipality I am looking at, and cross reference with the auditor's annual report for the same fiscal year. The auditor's report breaks down current liabilities more granularly. Between the two documents, you can reconstruct almost everything you need.
One thing that catches people off guard. The debt numbers in these reports do not include state-repayable stormwater infrastructure debt. A handful of Grant County municipalities carried that separate obligation for years after the 2018 flooding event. It does not show up in standard general obligation bond tables. I learned this the hard way when I prepared a comparison of debt ratios for two neighboring towns and the numbers did not add up. The discrepancy was about $340,000 in unreported stormwater debt for one of them. Once I pulled the watershed district records from the DNR, everything reconciled. If you are working with debt figures and they seem too low, check the environmental infrastructure fund notes in the comprehensive annual financial report. For raw bond data, the county treasurer's office maintains a public ledger of all outstanding municipal bonds. It is updated quarterly. The format is clunky. It is a spreadsheet with merged cells and inconsistent date formatting. I wrote a small Python script that cleans it into a usable table. The script reads the quarterly files, normalizes the dates, and exports to CSV. If you want the script, I can share it. It takes about ten minutes to process a year's worth of updates once you point it at the right folder. Debt ratio analysis for these smaller municipalities requires a different lens than you would use for a big city. A debt service coverage ratio below 1.5 looks shaky in most contexts. In Grant County, a ratio around 1.2 is common and not necessarily alarming. These municipalities have very narrow revenue bases. Water and sewer fees make up the bulk of their debt service capacity. When agricultural runoff hits, those fees dip. When crop prices drop, property tax growth stalls. The debt load does not change. The revenue does.
The most useful metric here is not the debt ratio. It is the ratio of annual debt service to operating revenue. I calculate that for each town I look at. If debt service exceeds 30 percent of operating revenue, the municipality has very little room to maneuver. Several Grant County communities sit above 40 percent. One is near 55 percent. That last one is the real problem. They are paying down old debt while simultaneously trying to replace aging water mains. The refinancing market offered them nothing reasonable last fall. Rates were too high for the risk profile, and the project timeline did not allow for a long bond sale process. What that community ended up doing was structuring a payment plan through the state revolving fund. It is slower than a traditional bond sale but avoids the premium costs. The trade off is a longer maturity and less flexibility in how the money can be deployed. I have recommended this approach for two other municipalities in the county with similar situations. It worked for both of them, though neither group was happy about it. They accepted it because there was no better option available at the time. If you are researching this yourself, I suggest starting with the municipality rather than the county. The county does not guarantee municipal debt. Each town issues its own obligations. The county's role is mostly oversight and reporting. Reading county-level summaries gives you a map. Reading individual municipal financial statements gives you the territory.
Get the Full Details

The Grant County assessor's office can provide property value trends by municipality. Pair those with the debt schedules and you can see how declining or stagnant valuation affects debt sustainability. Some towns have lost five to eight percent in assessed value over the past decade. Others held steady. The ones that declined are the ones where debt service conversations at public meetings get tense. There is a second data source that most people miss. The Wisconsin State Tax Commission publishes property valuation data by municipality annually. It is free and accessible. The data goes back decades. I use it to normalize debt per thousand dollars of evaluated property. That gives you a sense of whether a municipality is actually carrying more debt than it should relative to its tax base. It reveals things that total debt numbers hide. A town might look like it has moderate debt in absolute terms. Per evaluated property, it could be one of the heaviest borrowers in the state.
Where the Data Gets Messy
Municipal financial reporting in Wisconsin is not standardized the way corporate reporting is. Different towns use different fiscal years. Some report under GASB 34. Others use cash basis for internal purposes. This inconsistency makes side by side comparison annoying. I build a conversion layer in my spreadsheet that aligns all fiscal years to calendar year for the purpose of analysis. It adds about fifteen minutes to the process but saves hours of frustration later. Another quirk. Grant County municipalities sometimes refinance debt through special assessment districts rather than general obligation bonds. These show up in different sections of financial reports. They are technically municipal debt but are often discussed separately in board meetings. If you only look at general obligation tables, you will underestimate total debt burden by a meaningful margin in several communities. The county does publish a consolidated debt report each November. It includes special assessment obligations. The problem is that the report is formatted for presentation, not analysis. It rounds numbers, omits certain footnotes, and separates data across multiple tabs. I use it as a starting point and then drill into individual municipal statements for the precise figures.
A Few Practical Tips
If you are preparing a report or presentation on this topic, start with the most recent comprehensive annual financial report for each municipality you cover. Those documents contain the footnotes that explain what the headline numbers actually mean. I once spent an afternoon trying to figure out why one town's debt service appeared to spike dramatically. The footnotes revealed that the spike was due to a change in accounting treatment for lease obligations, not actual new borrowing. Without reading the notes, you would have drawn the wrong conclusion entirely. When you find a number that seems off, check the audit opinion. A qualified or adverse opinion changes how much weight you should give to the financial data. Grant County has not had a qualified opinion on municipal audits in recent years, but it is worth verifying for each municipality individually. Audit quality varies. The county budget commission holds public hearings on municipal budget proposals. Those hearing transcripts are available online. They contain the discussions where officials explain debt decisions in plain language. Reading them gives you context that financial statements alone cannot provide. I read the transcripts for any municipality I am analyzing closely. They reveal which issues are driving debt choices and which are just accounting artifacts.
For anyone who wants to dig deeper, the Wisconsin Department of Administration maintains a database of local government debt. It is not as current as county records, but it covers historical trends and allows comparison across counties. If you are studying how Grant County's municipal debt compares to similar rural counties in the state, this database is useful. The coverage for smaller municipalities is incomplete, so treat it as a supplementary source rather than a primary one. I have been working with this data for several years now. The patterns are consistent. Revenue volatility, aging infrastructure, and limited refinancing options create a cycle that is difficult to break without external intervention. The state revolving fund programs help, but they are not fast enough for municipalities facing immediate debt service pressure. There is no easy solution that fits all the towns in Grant County equally. Each one has a different mix of revenue base, debt maturity profile, and infrastructure needs. Any analysis that treats them as a single group will miss important differences.