The Reality of Making Filipino Chips at Home
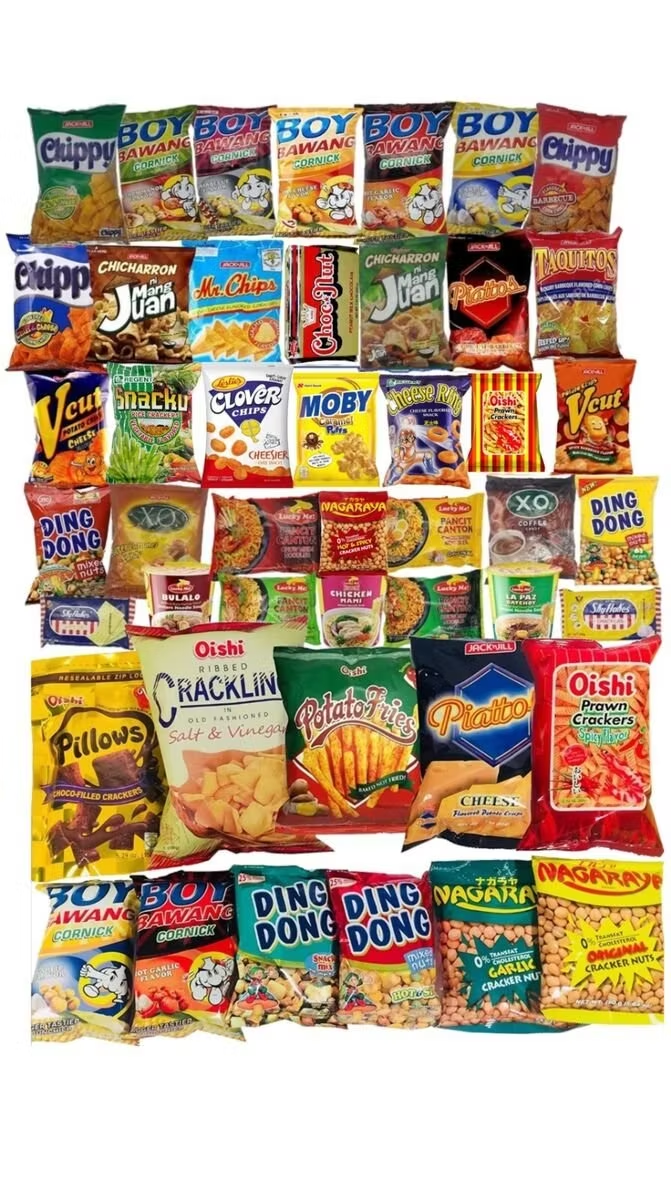
Chips in the Philippines are not the same as potato chips. They span two entirely different food categories that share one word. One is the thin, sliced potato snack you buy in a bag at the supermarket. The other is chicharon, made from pork skin or balut, deep-fried until puffy and light. Both are everywhere in the country. Both have complicated supply chains and a long road to going global. I spent years working in food production before moving into distribution, and I have seen both sides of this industry fail and succeed for completely different reasons. To understand why these products did not simply scale up overnight, you need to look at the raw material first. For potato chips, the Philippines has never been a major producer of the right variety. Most of the country's potatoes come from Benguet and the highlands around Itogon, and those are mostly waxy varieties suited for cooking, not slicing thin and frying. When manufacturers tried to standardize chip production in the 1990s and 2000s, they ran into moisture content issues almost immediately. Potatoes harvested at different times of the year had wildly different sugar levels, which meant batch after batch of chips came out with inconsistent color. Some batches were pale and bland. Others burnt at the edges because the reducing sugars were too high. I dealt with this firsthand at a processing plant in Baguio around 2014. We were trying to produce a uniform product for export, and every new harvest cycle ruined our quality control for at least three weeks. The workaround was not elegant. We started blending potatoes from multiple harvest windows and ran them through a prolonged soaking tank to leach out excess sugars before frying. That added about forty-five minutes to the process per batch, but it stabilized the color enough for us to pass buyer inspections. It was tedious, but it worked. Most smaller producers do not have the infrastructure for this kind of controlled blending, which is why many of them never make it past the local market.
The chicharon side of the story is different but equally complicated. Traditional chicharon making is labor-intensive and heavily dependent on fresh pork skin supply. The skin needs to be cleaned, boiled, dried, and then fried at precisely the right temperature. If the oil is too hot, the outside chars before the interior puffs. If it is too cool, the product comes out greasy and tough. I remember visiting a small producer in Pampanga who had been making chicharon for over twenty years, and he could tell you the oil temperature by watching how the skin bubbled. There was no thermometer on the wall. That kind of expertise does not transfer well to factory settings. When chicharon producers tried to scale up for broader distribution, they hit another wall: shelf life. Freshly fried chicharon goes rancid quickly because of the residual fat content. Without proper packaging and nitrogen flushing, you are looking at maybe two to three weeks before the product develops off-flavors that even regular consumers can detect. Major brands solved this with modified atmosphere packaging, but that requires capital investment that most small and medium producers simply do not have. I saw several regional brands disappear because they could not afford the packaging line upgrade, even though their product quality was solid. Both categories share a logistics problem that nobody talks about enough. The Philippines is an archipelago of over seven thousand islands, and getting a consistent product to every region costs more than the product itself in some cases. A bag of potato chips shipped from a factory in Luzon to Mindanao retailers eats into margins before it even reaches the shelf. Chicharon, being more fragile, suffers even more from breakage during transit. This is why you see so many local chip brands that never expand beyond their home province. It is not a quality issue. It is a distribution math problem.
The global angle is where things get interesting, and also where most people have wrong assumptions. There is a real international appetite for Filipino snacks, but not in the way most producers expect. Western markets are not lining up for mass-market potato chips. They are interested in the unique Filipino varieties, particularly the smaller-batch chicharon products with distinct flavor profiles like sinangag or garlic chili. These niche products have found buyers in specialty stores across the United States, Japan, and parts of Europe, but the volume is tiny. A single shipment might contain only two hundred to three hundred kilograms, and it moves through specialty importers rather than mainstream retail channels. If you are looking at entering this space or understanding how it works, here is what you need to know without any sugarcoating. The biggest mistake producers make is assuming that scaling up is the same as going global. Scaling up requires different equipment, different quality control systems, and different supply chain contracts. Going global requires certification compliance, export documentation, and relationships with international distributors who understand food import regulations. These are two separate skill sets, and very few producers have both. For potato chip production specifically, the counter-intuitive part is that starting with imported potato flakes instead of fresh potatoes can actually give you better consistency at small scale. Yes, it costs more per kilogram on the raw material, but you eliminate the variability of agricultural sourcing entirely. Several successful local brands actually started this way before eventually building their own farming partnerships. The reverse is also true for chicharon producers who find that working with established pork processors as suppliers is more reliable than trying to source skin directly from individual butchers. The margins are thinner, but the quality is far more predictable.
Get the Full Details

There is also a misconception that the Filipino market is saturated. It is large, yes, but it is not saturated at the premium end. Consumers in urban areas are willing to pay more for artisanal varieties, organic certifications, or novel flavors that do not exist in the major brand catalog. I have seen small producers charge twice the price of mainstream brands and still sell out every week in select supermarkets. The constraint is not demand. The constraint is usually production capacity and the ability to maintain quality while ramping up. One practical detail that most guides skip: the difference between open-kitchen chicharon production and certified facility production. If you plan to sell through major retail chains, you need FDA registration and Good Manufacturing Practice certification. This means everything from flooring to ventilation to employee hygiene protocols gets inspected. Many producers I know spent anywhere from six months to over a year getting their facilities up to code. The cost ranged from half a million to over two million pesos depending on how far behind they were. This is not something you work around. It is a hard gate before you can meaningfully distribute beyond your immediate area. The export route has its own gate. You need to comply with the importing country's food safety standards. The United States requires FDA registration and compliance with FSMA rules. Japan has its own Positive List System for food additives and contaminants. These are not trivial hurdles, and they require documentation that most small producers have never prepared before. I once helped a producer navigate the Japanese export process, and the sheer volume of paperwork alone took three months before we even submitted the first application. The product testing alone ran about eighty thousand pesos across multiple laboratories.
Despite all of this, the trajectory is positive. Both the potato chip and chicharon sectors in the Philippines have grown steadily over the last decade, with local brands capturing market share from imported competitors. Consumer preference has shifted toward domestic brands that understand local taste preferences. The infrastructure is improving. Logistics costs are slowly coming down as ports and warehousing improve in key regions. The global interest in Filipino cuisine has created a tailwind that did not exist fifteen years ago. What it means in practice for someone looking to enter either segment is that the opportunity is real but the path is narrow and specific. The generic mass-market route is dominated by well-capitalized players with existing distribution networks. The niche artisanal route is viable but requires patience, certification work, and a willingness to operate at small volume for a long time before things start to move. There is no shortcut around the technical and regulatory requirements, and anyone telling you otherwise is probably selling something.