Setting Up Meta Pay Without Losing Your Mind
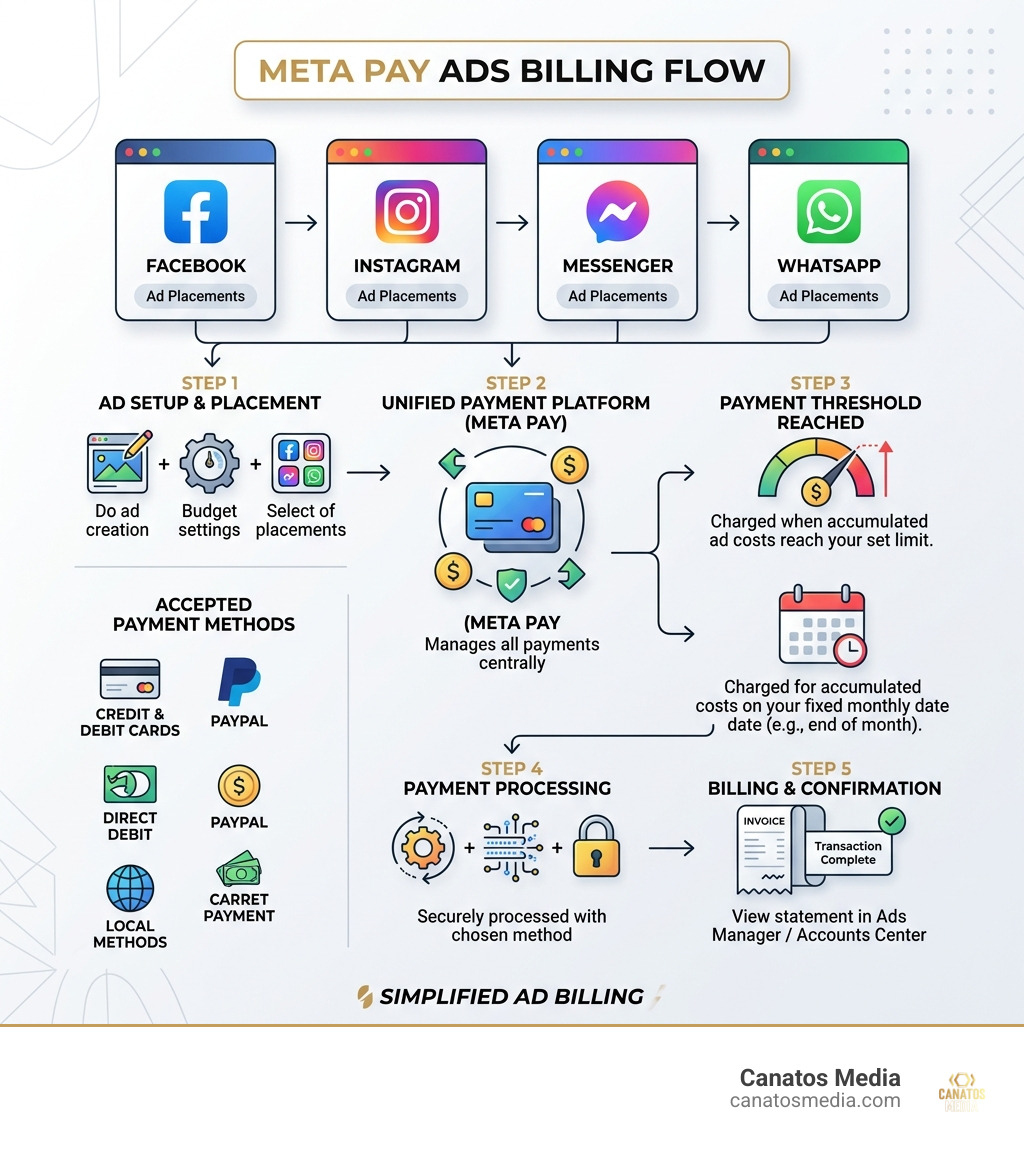
Meta Pay is how Facebook and Instagram handle transactions now. It replaced all the old payment systems Meta ran separately. When you want to buy something in Facebook Marketplace, send money to a creator, or check out from an in-app store, Meta Pay is what processes it. It lives under Settings > Meta Pay in the app. That's it. The interface hasn't changed much since they unified everything. Here's what you actually do when setting it up. Open Facebook. Tap the menu (three lines). Scroll to Settings & Privacy, then Settings. Under Payments, you'll see Meta Pay. Tap it. You add a payment method — credit card, debit card, or PayPal. That's the basic flow. From there you can enable Quick Checkout so you don't re-enter info every time you buy something. It's faster than I expected the first time I went through it. Maybe ten seconds to set up and get past the identity verification step, which is the part most people complain about. Meta asks for your full name, date of birth, and the last four digits of your Social Security number (or equivalent ID for non-US accounts). This is a standard KYC requirement, nothing unusual. I've seen people abandon the setup because they think this is sketchy. It's not. It's the same requirement any legit financial service has.
Once verified, you can start using it immediately. There's no waiting period. I was able to buy a shirt through Facebook's shop within minutes of finishing the verification. The purchase went through without any extra friction.
What Most People Get Wrong About Meta Pay
The biggest confusion is assuming Meta Pay works the same way as Facebook Pay. They're related but not identical. Facebook Pay was the original system that let you share payment info across Meta apps. Meta Pay is the consumer-facing wallet that actually processes transactions. You set up Meta Pay using your Facebook Pay information, but they serve different purposes. If you're trying to send money to a friend on Messenger, that goes through Meta Pay. If you're checking out from a retailer's app that's integrated with Meta's checkout, that also goes through Meta Pay but pulls from the payment methods you've stored there. Another thing nobody tells you: Meta Pay doesn't support all payment methods in all countries. I ran into this when trying to add a prepaid Visa card to my account. It was rejected. The card worked fine everywhere else. Meta simply doesn't accept prepaid cards. Only standard credit and debit cards from major issuers, plus PayPal. If you're in a region where bank integration is limited, your options shrink further. In India, for example, UPI is supported but the experience is more limited than it is in the US or UK. There's also a spending limit you'll hit if you're doing anything beyond casual purchasing. New accounts start with a $500 monthly limit. After you verify your identity fully and have a transaction history, it goes up. I hit the limit on my second month and had to wait three business days for it to reset partially. Not a huge deal if you're buying occasionally, but if you're running a small shop and relying on Meta Pay for customer transactions, this becomes a real bottleneck.
Get the Full Details
Common Problems and What Actually Fixes Them
The most frequent issue I see people dealing with is the identity verification getting stuck. You submit your info and it just sits there. Sometimes it takes a few hours. Sometimes it takes days. There's no way to speed it up, and Meta's support doesn't help much with this. The workaround that actually works is making sure the name on your Facebook account exactly matches the name on your government ID. I had an account where my Facebook profile said "John M. Smith" but my driver's license said "John Michael Smith." Verification failed twice until I updated the profile name to match exactly. Minor detail, huge difference. Another problem is merchants not accepting Meta Pay even when it seems like they should. If you're trying to buy from a business page and the checkout option doesn't appear, it's usually because the merchant hasn't enabled Meta Pay on their end. It's not a setting on your side. You can sometimes work around this by contacting the merchant directly through Messenger and asking them to enable it. I did this once for a small clothing store and they had no idea they could accept payments through Meta Pay. After they enabled it, everything worked normally. Security-wise, Meta Pay uses the same encryption standards as major banks. That's not marketing language, it's factual. They're PCI DSS compliant. The risk level is about the same as entering your card details on any other e-commerce site. The main thing you should do is enable two-factor authentication on your Facebook account. If someone gets into your Facebook, they get into your Meta Pay. I've seen this happen to people who reused passwords across sites. It's not a Meta Pay problem, it's a password hygiene problem, but it's the most common way people lose money through these platforms.
One edge case that caught me off guard: if you share a device with family members, Meta Pay doesn't support multiple profiles on the same account. I tried to set up a separate payment method for my wife's purchases while we were sharing my phone. It wouldn't let me. Each Meta Pay wallet is tied to one person's identity. If multiple people on a household need to use it separately, they each need their own Facebook account and their own verified wallet. There's no family account feature or anything like that. I wasted about twenty minutes trying to figure out if I was just missing a setting before realizing it doesn't exist.
When Meta Pay Isn't the Right Tool
It's worth being honest about where this falls short. If you're a business doing high-volume sales, Meta Pay's transaction limits and lack of robust analytics make it a poor primary payment processor. You'd be better off using Shopify Payments, Stripe, or PayPal Business. Meta Pay is designed for casual consumers and small-scale sellers, not serious ecommerce operations. If you're sending money internationally, the fees add up quickly. Meta charges a fee for cross-border transactions that varies by card type and country pair. I compared it to PayPal's rates and Meta was slightly cheaper on some routes and worse on others. Nothing dramatic, but if you're moving money regularly, it's worth checking both. There's also the issue of dispute resolution. If you have a problem with a purchase, Meta's dispute process is slower than what you'd get through a credit card company. I had to dispute a charge for an item that never arrived. Meta resolved it in about two weeks after I submitted documentation. My credit card issuer would have handled it in three days and given me provisional credit immediately. Meta Pay is convenient until you need it to work hard.

The setup itself is genuinely straightforward. Five minutes if nothing goes wrong. The verification is the only real hurdle, and it almost always succeeds if your information is consistent. Once it's working, it's fast and unobtrusive. Just don't expect it to solve problems it wasn't designed for, and don't rely on it for anything that involves significant money or multiple users.