What The Comenity Sephora Visa Actually Is
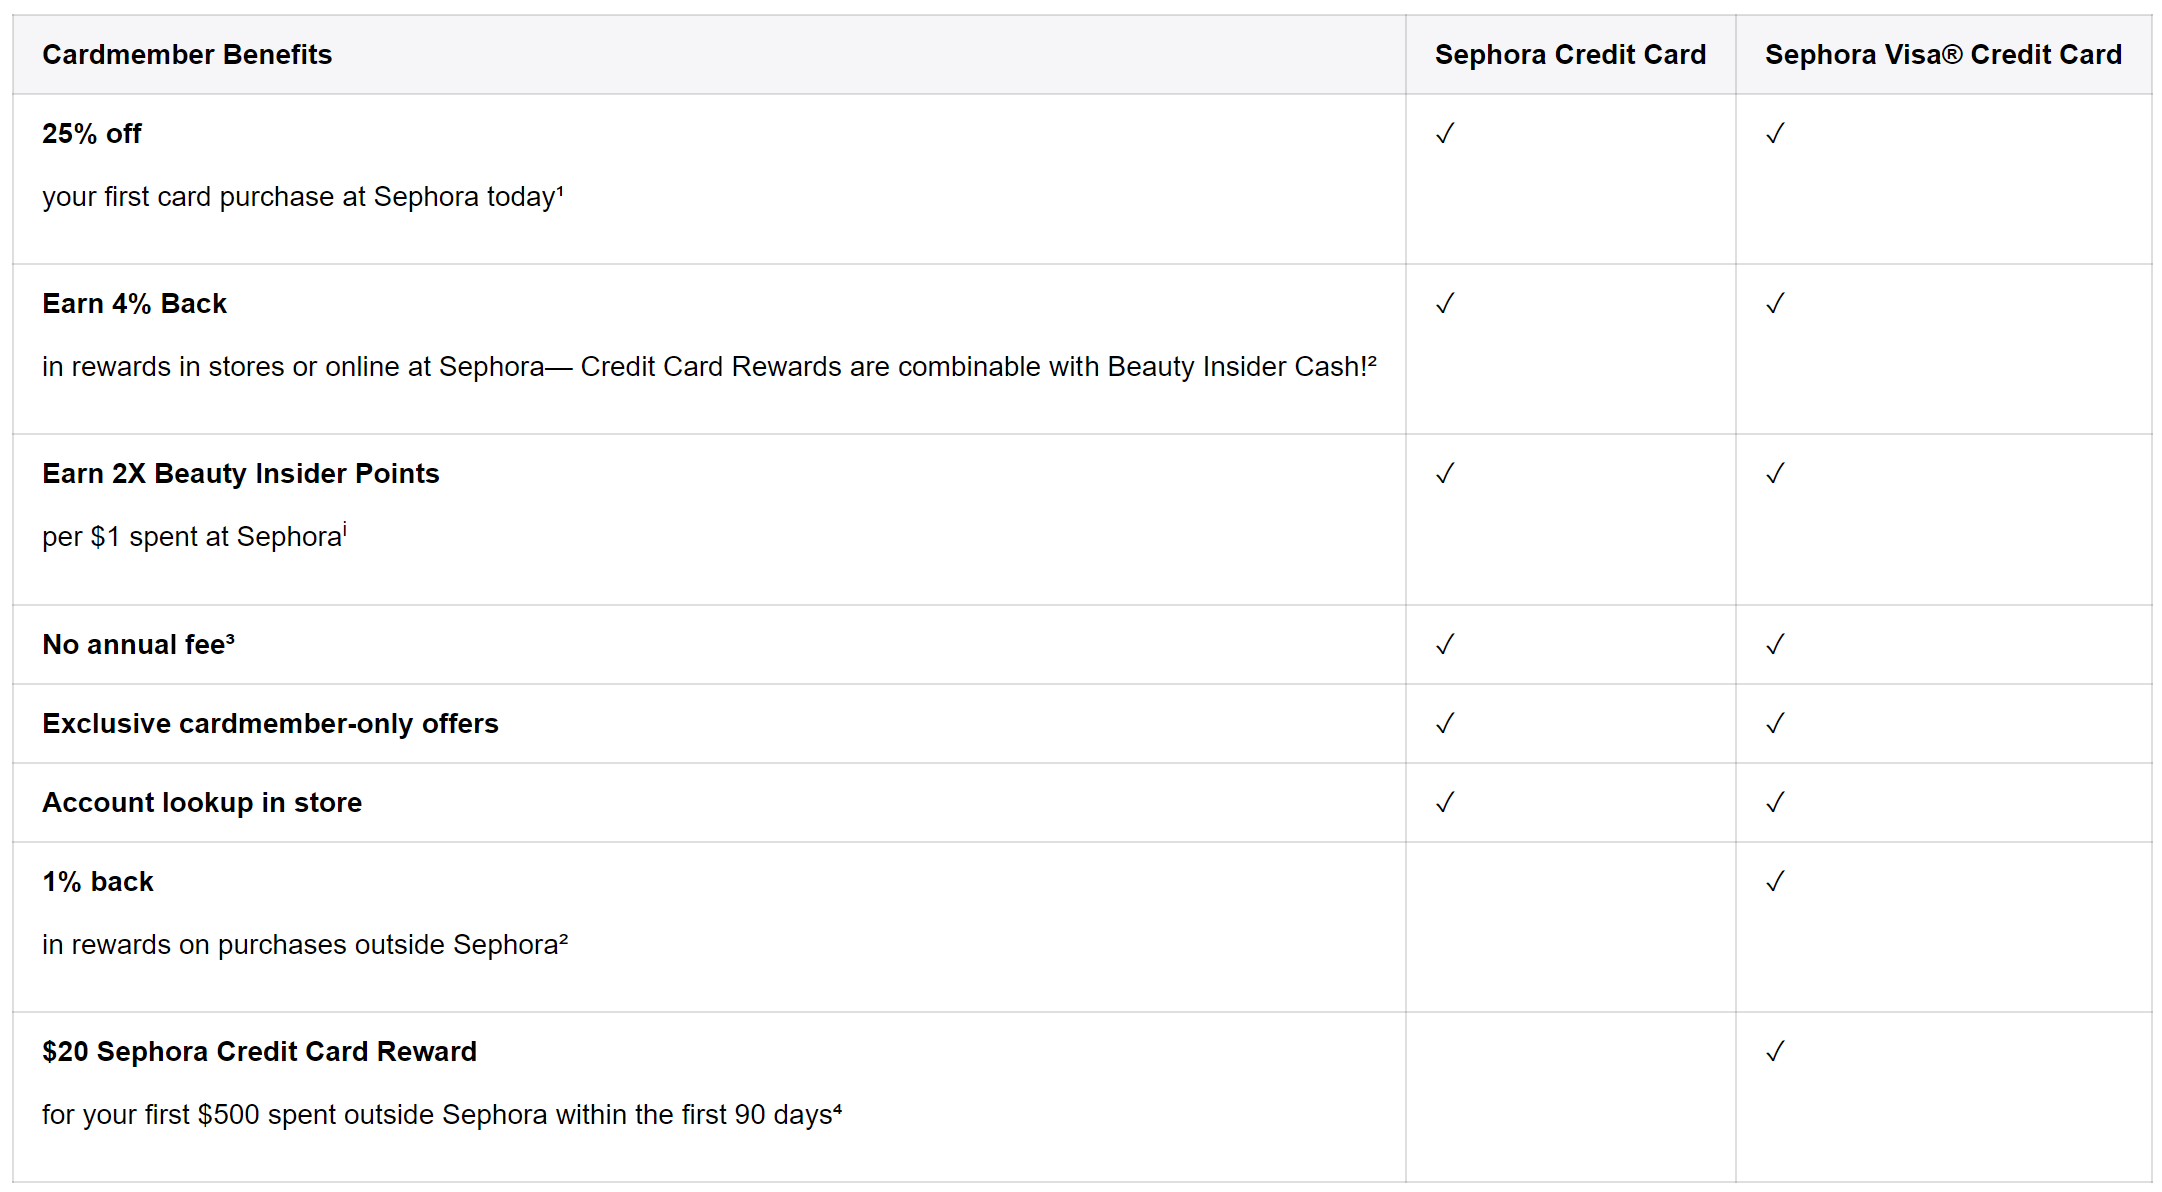
The Comenity Sephora Visa is a store-branded credit card issued by Comenity Bank specifically for Sephora shoppers. It falls into the category of retail co-branded cards, which means it is not some universal travel rewards product. You are getting a card designed for one purpose: to make you spend more at Sephora. The rewards structure is straightforward. You earn 2 points per dollar on Sephora purchases and 1 point per dollar everywhere else. Points are redeemable for rewards certificates that drop into increments like $6 off $30, $15 off $75, and so on. There is no annual fee. That is the first thing most people find appealing.
The Shocking Truth About Comenity Sephora Visa What You Need To Know
Here is the practical reality that nobody puts on the application page. The card's APR is around 28.99% variable, which is among the highest you will find in the retail card space. Comenity Bank cards are notorious for this. If you carry a balance even for a single billing cycle after a promotional period ends, the interest charges will obliterate any reward value you accumulated. I learned this the hard way during a promotion where they offered deferred interest on purchases over a certain amount. I financed a holiday shopping spree and assumed I would pay it off before the window closed. I missed it by three days because Comenity's payment processing timeline does not always align with your bank's posted cutoff times. You can end up owing interest on the entire original balance, not just what you didn't pay down. That is not a rumor. That is how deferred interest programs work and Comenity has been sued over this exact mechanism. The approval odds are another thing worth addressing. This is a subprime-friendly card. People with credit scores in the fair range, sometimes even low 600s, get approved. Comenity uses a soft pull during their pre-qualification tool, then a hard inquiry when you actually apply. The card tends to factor in recent credit activity heavily. Applying for multiple retail cards within a short window will likely tank your chances across the board, not just with Sephora.
How To Maximize the Rewards Without Getting Burned
The card works best when you treat it like a loyalty tool, not a financial instrument. Use it only for Sephora purchases you were already planning to make. Stack it with Sephora's Beauty Insider program. Cardholders often get bonus point multipliers during promotional windows, sometimes 5x or 10x points on specific items. Check the cardholder offers page before you check out. Those multipliers can push the effective return well above the standard 2x. There is a specific edge case that catches people off guard. Sephora occasionally runs promotions where buying a higher-tier set unlocks bonus points that exceed the value of the items themselves. I once purchased a fragrance gift set during a 10x points promotion and ended up with enough points for a reward certificate that was worth more than the set's price difference compared to buying the individual items separately. The math only works if you factor in the reward certificate value, not just the raw discount. Do the calculation out loud before you add anything to your cart. Another nuance people miss: Sephora's return policy interacts with rewards in ways that are not immediately obvious. If you return an item, the points you earned are clawed back. If you already redeemed those points toward a reward certificate and then return the purchase, you will lose the certificate value unless you replace the points first. I once returned a skincare bundle three weeks after redemption and had to repurchase just to get my points back. The customer service team could not override the system on that one. It took about ten minutes on chat to sort out, but it is a friction point worth knowing about before you redeem aggressively.
Get the Full Details

Who Should Actually Get This Card
If you spend under $200 a month at Sephora, this card is marginally useful at best. The rewards accumulate slowly and a simple cashback card on groceries or gas will outperform it outside of promotional periods. If you are a frequent Sephora shopper, meaning monthly spend above $300, the 2x base rate plus periodic promotions make it worthwhile as a secondary card, not a primary one. The real limitation is that this card offers no travel insurance, no purchase protection beyond what Sephora already provides, and no global acceptance advantages. It is a Sephora card, period. If you want a card with broader utility, the Wells Fargo Active Cash card or a similar no-annual-fee cashback option will serve you better for general spending. Keep the Sephora card locked away for store purchases only. Treat it like a discount mechanism, not a lifestyle credit product. One more thing that comes up regularly: the card's credit limit tends to start low, usually in the $500 to $1,000 range for most applicants. Limits do increase over time with responsible use, but it is not automatic. Comenity reviews accounts periodically and most people do not get a meaningful bump until they have carried the card for at least a year. If you need a higher limit for a big Sephora purchase, you will likely hit the wall quickly.
Apply through the Sephora website if you can. Their pre-qualification tool uses a soft pull and will tell you your odds before you commit to a hard inquiry. If you get declined, do not reapply immediately. Each inquiry stays on your report for two years and lenders will see the recent retail card applications and treat you as a credit risk. Wait at least six months, ideally longer, before trying again. The card is not going anywhere.