What SPAXX Actually Is (And What It Isn't)
SPAXX is the ticker symbol for Fidelity's Government Money Fund. It is a money market fund, which means it is a type of mutual fund, but calling it just a "mutual fund" without qualification is misleading because the mechanics are completely different from what most people picture when they hear that word. It invests in U.S. Treasury securities, agency debt, repurchase agreements, and other short-term cash equivalents. The goal is stability, not growth. It targets a constant net asset value of one dollar per share. I learned this the hard way in 2022 when I moved about eighty thousand dollars into SPAXX from a checking account, assuming it was functionally equivalent to a high-yield savings account. It wasn't. There was no FDIC insurance. No deposit limits. If the fund had broken the buck, I would have been out money with no government backstop. The yield was good at the time because the Fed funds rate was hovering near zero but climbing, and SPAXX tracks that closely. But the structural difference matters more than the rate differential.
The Shocking Story Of Fidelity Spaxx Is It A Mutual Fund Your Guide
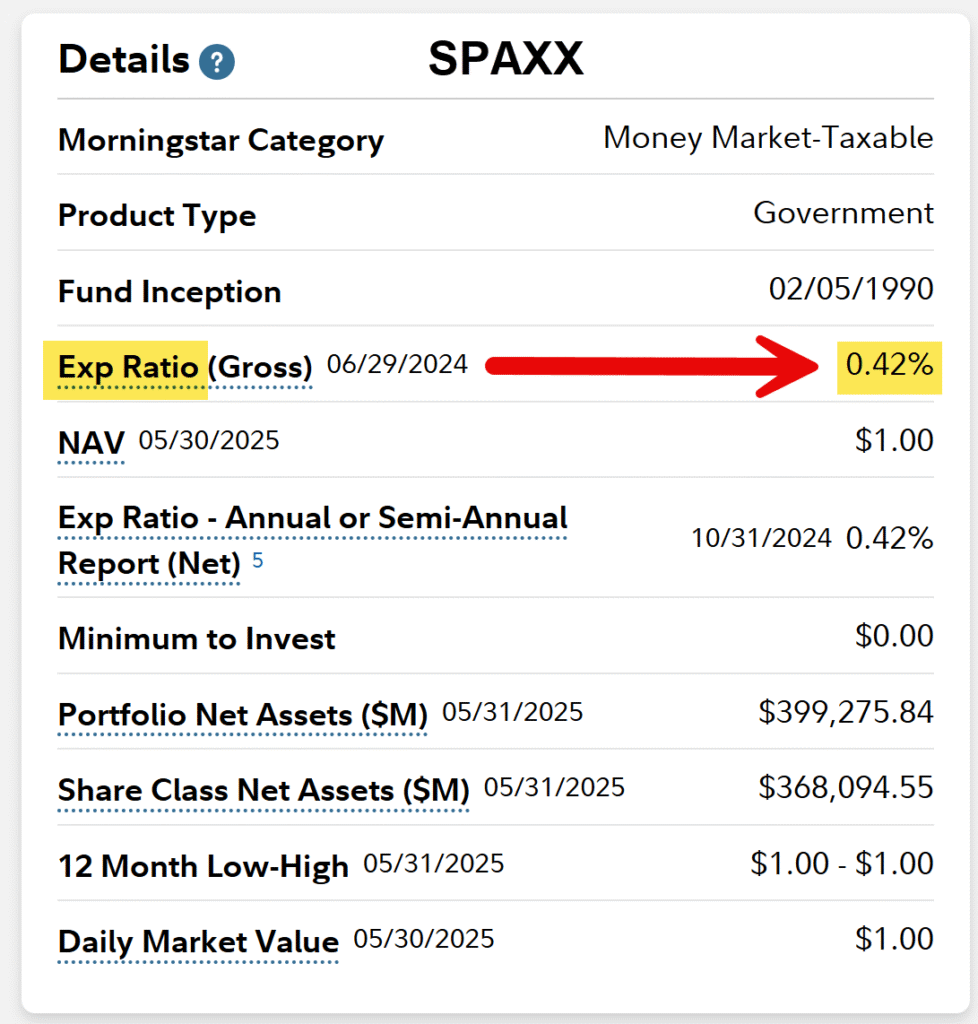
Yes, SPAXX is technically a mutual fund. It is registered under the Investment Company Act of 1940. It files N-PORT and N-CEN forms with the SEC. It has a board of trustees. All of that checks the box. But the operational reality is closer to a cash management vehicle than an investment you analyze for portfolio allocation. The expense ratio is roughly point zero four percent, which sounds trivial until you realize that translates to about four dollars a year per ten thousand invested. On a five hundred thousand balance, that is two hundred dollars annually. Not much, but it is not nothing if you are comparing it to a treasury bill ladder you could construct yourself at similar cost. The dividend distributions are monthly. They are reported as ordinary income on your tax return, not qualified dividends. This is important because it means there is no preferential tax treatment. In a taxable account, that yield gets taxed at your marginal bracket. In a Roth IRA or traditional IRA, it grows tax-advantaged, which is arguably the best use case for this fund. I moved my IRA cash reserves into SPAXX specifically for this reason. The alternative is leaving money in a settlement fund with lower yields or trying to manage a laddered T-bill portfolio through Fidelity's interface, which is possible but takes actual time and attention. One thing nobody tells you about SPAXX is the yield calculation lag. The current yield you see on Fidelity's website or in your account dashboard is a seven-day annualized yield based on trailing data. It does not reflect today's rate environment in real time. When the Fed cut rates in 2023 and 2024, SPAXX yield dropped gradually over weeks, not overnight. If you are timing your cash placement around rate moves, you need to understand this delay. I got caught holding a larger position than necessary during a brief rate hike cycle because I assumed the yield would adjust immediately. It did not. The distribution was based on the prior month's income.
Another nuance is the minimum investment. For direct purchase through Fidelity, the initial minimum is two thousand dollars. The additional investment minimum is one dollar. This is unusually low compared to other money market funds, which often require ten or twenty five thousand. That is probably why SPAXX has over one hundred billion in assets. It is the default sweep option for Fidelity brokerage accounts, which means virtually every Fidelity customer who does not actively manage their cash ends up in SPAXX whether they know it or not. You can opt out, but the default enrollment is automatic unless you change it in your account settings. Here is the edge case that tripped me up. If you have a Fidelity brokerage account and you do not actively place your cash, the system sweeps uninvested money into SPAXX automatically. I discovered this after receiving a tax document that included SPAXX income alongside my taxable interest from bonds and CDs. I had not consciously placed anything there. The sweep was automatic. If you are trying to manage cash across multiple vehicles for liquidity reasons, you need to either disable the sweep or monitor it carefully, because it can quietly move money between accounts and change your tax reporting in ways that are easy to miss. Is SPAXX a good place to park cash? Yes, if you value convenience and do not want to manage individual short-term instruments. The liquidity is essentially immediate. You can sell shares and have the proceeds available for withdrawal or transfer within one business day, sometimes same day depending on your bank's processing. The risk profile is extremely low, though not zero. In March 2023, when Silicon Valley Bank failed and there was brief concern about money market fund stability, SPAXX did not experience a run. Its holdings are in government securities, which are considered safer than the commercial paper exposure that plagued some prime money market funds during that period.
Get the Full Details

The main limitation is opportunity cost. You will never beat a T-bill ladder by more than a few basis points, and you will rarely match it after expenses. But constructing and maintaining a laddered T-bill portfolio requires monitoring maturity dates, reinvesting as bills roll off, and dealing with the auction process or secondary market purchases. For most people, the time spent is not worth the marginal yield improvement. SPAXX is the lazy person's money market fund, and that is not an insult. It is an accurate description of its value proposition. If you want a direct comparison, look at VMFXX, Vanguard's Federal Money Market Fund. It is structurally similar, with a comparable expense ratio and nearly identical yield. The choice between them usually comes down to which platform you already use. If you are a Fidelity customer, staying with SPAXX avoids transfer friction. If you are at Vanguard, VMFXX is the equivalent default. The yield difference between them is typically less than one basis point and fluctuates daily. The practical takeaway is that SPAXX is a legitimate mutual fund product, not a savings account substitute, and it should be treated as a cash management tool rather than an investment. It has its place, particularly for IRA cash reserves and short-term operational buffers. It does not belong in a long-term growth allocation or a portfolio designed to outpace inflation. Understand the tax treatment, monitor the yield lag, and watch the automatic sweep settings if you care about where your uninvested cash actually lives.