How Media Consolidation Reshaped America's Most Famous Network
The 1995 deal that brought Westinghouse Electric into CBS was supposed to save the network from irrelevance. Instead it triggered a chain of acquisitions that would last thirty years and fundamentally change what American television looked like. I spent several years tracking broadcast ownership filings at the FCC while researching media mergers, and the paperwork alone tells a story more interesting than any network drama ever produced. William S. Paley built CBS into the dominant radio network during the 1920s and 1930s by acquiring affiliate stations and producing content that actually reached people. The Columbia Phonograph Company connection gave him access to recording technology that radio stations needed. When television arrived, he transferred that same strategy to the new medium, building a network that competed directly with NBC and eventually surpassed it in ratings by the late 1940s. The Paley era ended in 1958 when he stepped down as chairman. The network struggled through the early 1960s with programming that couldn't compete with NBC's variety shows or ABC's news coverage. It wasn't until William S. Paley returned to the board in 1962 that CBS began producing content that would define the next two decades, including The Twilight Zone and I Love Lucy reruns that still generated revenue decades later.
The real ownership revolution started in 1995 when Westinghouse acquired CBS for $5.4 billion. Westinghouse was already a major television group owner through its CBS Television Stations group, and the acquisition gave them control of the CBS network itself. This was before the Telecommunications Act of 1996 changed everything, so the deal required extensive FCC review and conditions that limited how Westinghouse could operate its stations. When Time Inc. merged with Warner Communications in 1989 to form Time Warner, they didn't include CBS because CBS was owned by different shareholders. But the media consolidation trend that created Time Warner inevitably turned attention toward CBS, which was trading at historically low valuations compared to its content library and affiliate revenue. Westinghouse understood this better than anyone and made the acquisition work financially even though the market didn't immediately reward it. I remember sitting in a conference room in 1998 reviewing the revised ownership charts after the Westinghouse rebranding to CBS Corporation. The organizational structure was more complex than it appeared on the surface because Westinghouse had acquired multiple television station groups throughout the 1990s, including stations in New York, Los Angeles, Chicago, and Philadelphia. These owned-and-operated stations generated advertising revenue that subsidized network programming costs, which meant the acquisition had both strategic and financial importance beyond just the CBS network name.
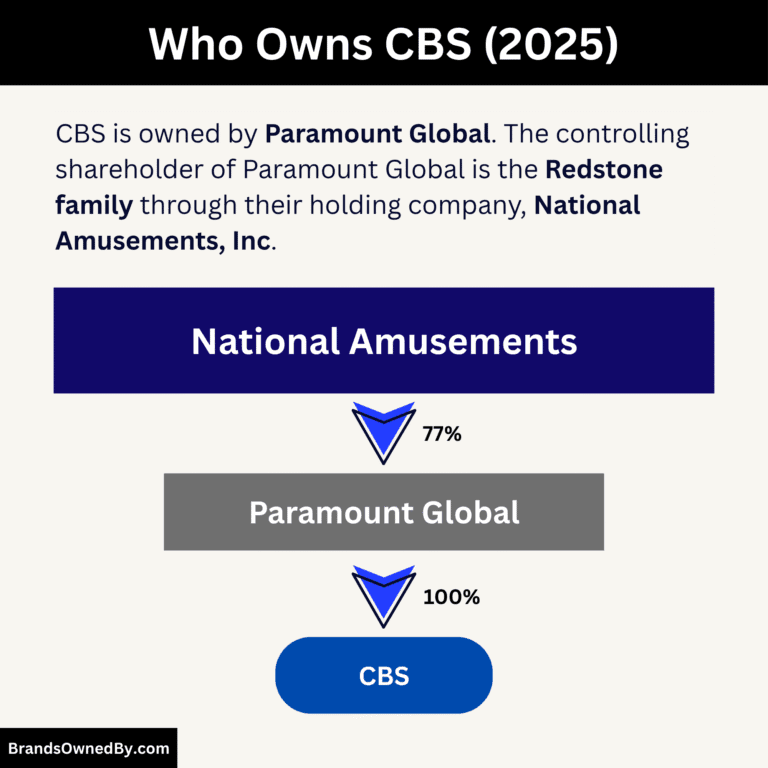
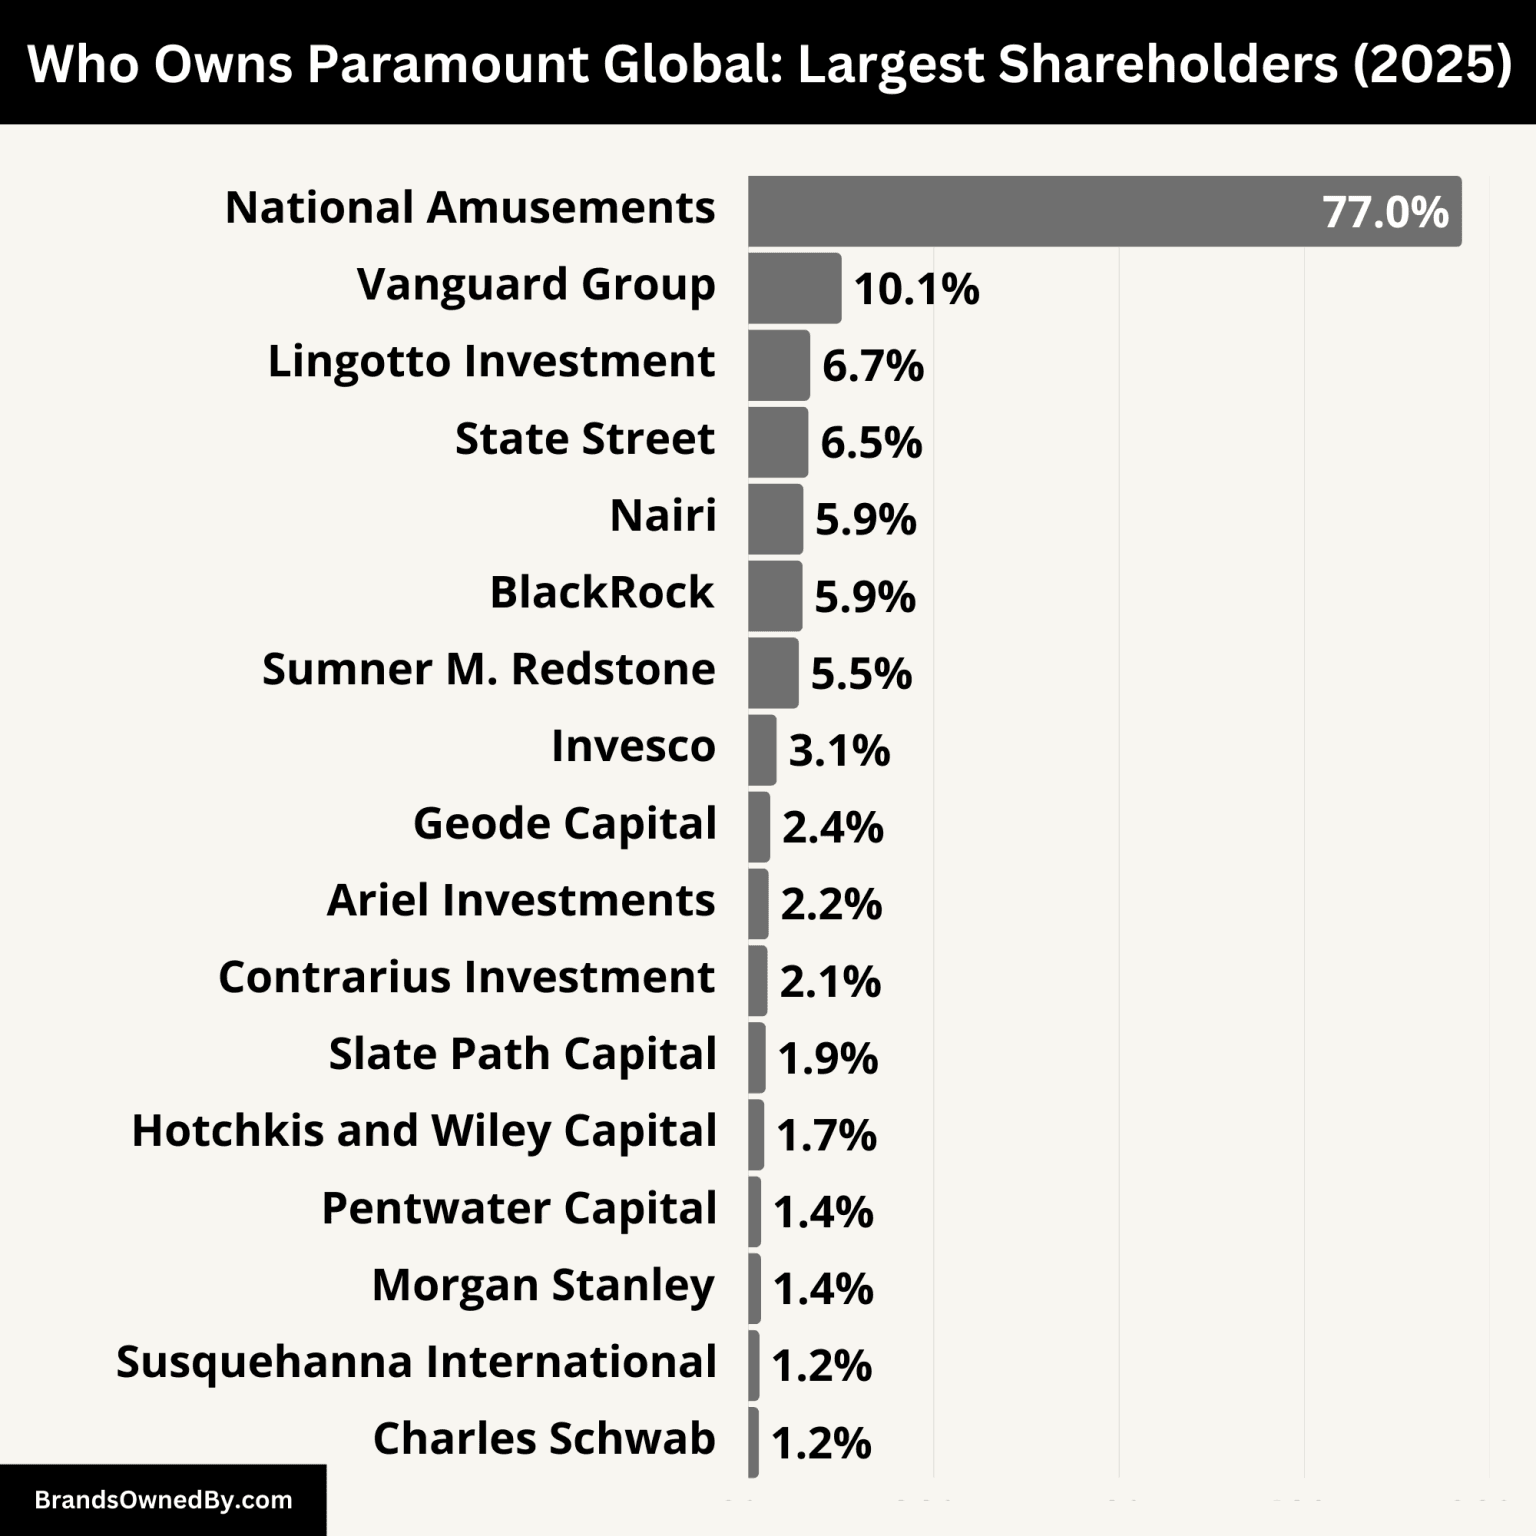
The Viacom split happened in 2005 when CBS Corporation and Viacom separated after being merged together in 2000. This was one of those corporate reversals that looked bizarre at the time but made sense in retrospect. Sumner Redstone controlled both entities through National Amusements, the theatrical chain that owned the distribution rights to most major studio films, and he used that controlling interest to force the merge in 2000 and then force the split in 2005 when shareholders complained about the combined company's performance. During the 2006 to 2019 period, CBS Corporation operated as a standalone entity focused on broadcasting, cable networks like Comedy Central and MTV, and digital assets. The network maintained its position as one of the major three broadcasters alongside NBC and ABC, though its ratings shifted depending on the programming cycle. The Super Bowl broadcasts, Survivor, and NCIS generated consistent revenue that made CBS the highest-rated broadcast network for much of that period. The 2019 merger with Viacom created ViacomCBS, later rebranded as Paramount Global in 2022. This time the consolidation was driven by the need to compete with Disney+, HBO Max, and Netflix in the streaming market. CBS's linear television business was declining in viewership but still generated substantial cash flow, which could subsidize streaming investments that the pure-play streamers couldn't afford to match. The combined company had Paramount Pictures, MTV, Nickelodeon, Comedy Central, and the CBS network under one roof.
Get the Full Details
The downside of this structure became apparent during the 2023 to 2024 period when Paramount Global faced significant debt from the merger and declining cable affiliate fees. Streaming losses continued despite subscriber growth on Paramount+, and the linear business couldn't generate enough surplus to fund both operations comfortably. This is where the ownership structure matters practically, not just historically, because the debt covenants and segment reporting requirements created constraints that affected programming decisions, talent contracts, and strategic partnerships. I encountered a specific problem when trying to trace accurate ownership percentages through the various corporate restructuring documents between 2005 and 2019. The SEC filings showed different ownership figures depending on whether you looked at common stock outstanding, voting power through Redstone's controlling shares, or the economic interests held by National Amusements. The workaround was to cross-reference the proxy statements with the annual 10-K filings and then verify against the FCC's ownership database, which tracks broadcast station control separately from corporate ownership structure. The current situation involves exploration of strategic alternatives, including potential sale or merger discussions that have been reported but not finalized. Whether Paramount Global remains independent, gets acquired by a larger media company, or splits back into separate broadcasting and streaming entities will determine the next chapter in CBS ownership history. The pattern from the previous thirty years suggests that consolidation and separation will continue to be the primary organizational moves rather than stable long-term independent operation.
What most people miss when studying CBS ownership history is that the network's value has always been disproportionate to its market capitalization during acquisition periods. The CBS name, the affiliate relationships, the sports broadcasting rights, and the library content created intrinsic value that buyers were willing to pay premiums for, even when the surrounding business showed declining metrics. This pattern repeated in 1995, 2000, and 2019, and it will likely repeat again if another acquisition occurs. The counter-intuitive insight is that smaller ownership changes often matter more than the headline-grabbing mergers. When Westinghouse rebranded to CBS Corporation in 2000, the legal entity survived but the corporate culture changed completely. When Viacom and CBS merged in 2000 and split in 2005, the operational independence returned but the financial constraints of being separate entities created pressures that eventually forced the 2019 reunification. These micro-shifts in control and strategy had more impact on daily operations than the major transaction values suggested.
Practical Takeaways for Understanding Media Ownership
Tracking broadcast ownership requires looking beyond the obvious corporate names because control can be exercised through voting shares, board seats, or contractual agreements that don't appear in simple ownership charts. The FCC's database shows station-level control, while SEC filings show corporate ownership, and these two perspectives often diverge in ways that confuse casual observers. The CBS story demonstrates that media ownership follows a cycle of consolidation followed by separation, typically every fifteen to twenty years. This pattern reflects the tension between scale advantages in content production and distribution versus the flexibility needed to adapt to changing technology and consumer behavior. Both approaches have worked at different times, and neither approach has provided permanent stability for the companies involved. If you're researching CBS ownership for academic or professional purposes, start with the FCC's online facility search tool for station-level data, then move to SEC EDGAR for corporate filings, and finally check the Court Scrip database for litigation history that might reveal ownership disputes or control battles that official filings don't always capture clearly.