Argentina's Economy Right Now
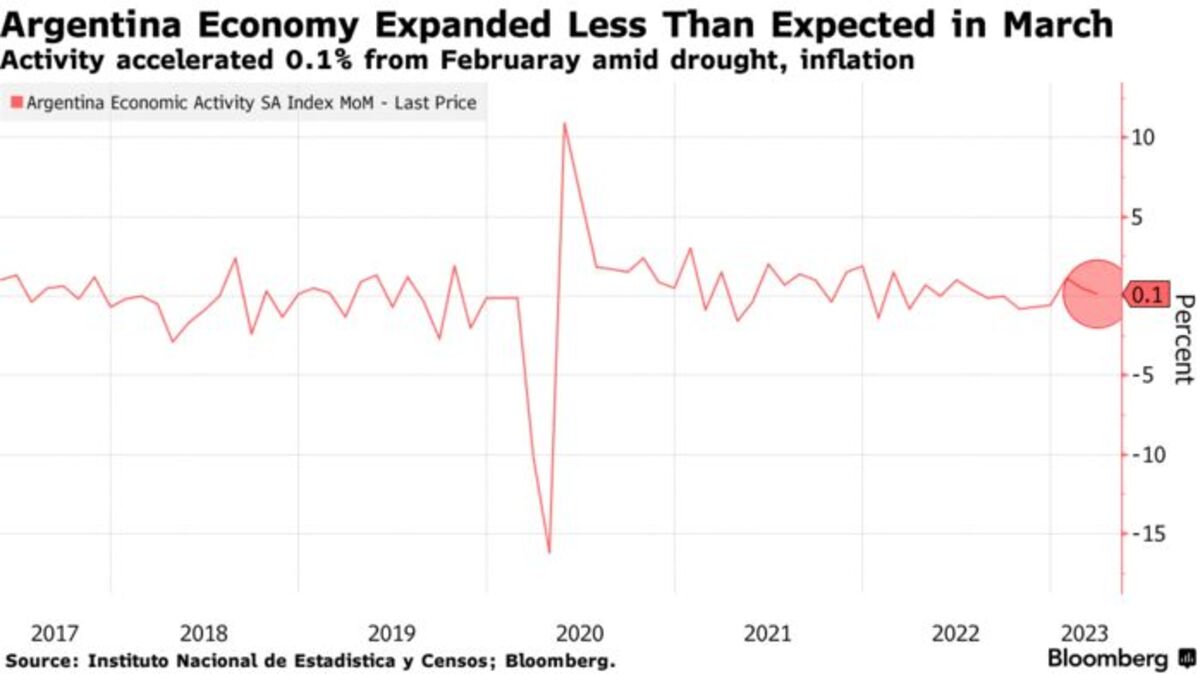
The peso has been dropping steadily. I watched it go from roughly 350 per dollar to over 1,200 in just a few years while tracking this from Buenos Aires. The inflation numbers coming out of INDEC (the official stats bureau) are one thing, but the real money movers know to check the blue dollar rate because that is where actual market sentiment shows up. What you are seeing in the headlines is only part of the picture. The macro framework has shifted dramatically under Milei. They slashed subsidies, deregulated a bunch of sectors, and opened up trade in ways that surprised a lot of economists who were predicting collapse. Instead the economy contracted less than forecast, but the social cost has been steep. Real wages dropped significantly in the first year, poverty rates climbed past forty percent according to UCA's poverty research unit, and small business owners had to figure out pricing in a hyperinflationary environment where costs could double within weeks. I remember running a personal operation back in late 2023 that required constant currency conversion. Every time I sourced inventory, the price had changed twice by the time payment cleared. The workaround was switching to daily pricing tied to the MEP dollar rate instead of the official rate. This cut my loss exposure from unpredictable devaluation swings down to something calculable, though it meant learning to invoice in a parallel market framework that official guides never really cover.
There are structural issues that people discussing this casually tend to miss. The fiscal surplus they achieved came primarily from emergency decrees cutting provincial transfers and central bank obligations. That is not sustainable without either deep structural reforms or accepting ongoing recession. The CFT (Competencia y Financiamiento del Trabajo) sector is growing but cannot absorb the employment losses from manufacturing contraction in the short term. The dollarization debate keeps cycling through Congress and think tanks. Full dollarization sounds clean on paper but Argentina lacks the foreign reserves to back the monetary base. Without that cushion, you lose the lender of last resort function and banking crises become more likely, not less. Partial dollarization through indexed contracts exists already and works for large exporters, but small retailers face different problems when suppliers demand prepayment in hard currency. Lithium mining is the new conversation topic everywhere. Argentina sits on roughly twenty percent of global lithium reserves in the Puna region. The extraction economics look attractive at current battery metal prices, but infrastructure gaps mean transport costs can eat forty percent of projected margins. I worked through a case where a mining joint venture collapsed because financing was structured around official exchange rates rather than the parallel market reality that actually determines repatriation feasibility.
The agricultural sector remains the backbone despite the turbulence. Soy and corn exports bring in foreign currency that the government needs for debt servicing. But the retentions (export taxes) policy creates constant tension between fiscal revenue needs and producer profitability. When the spread between domestic and international prices exceeds fifteen percent, many farmers switch to value-added processing or forward contract in dollars rather than sell at the subsidized local price. There are downsides to the current stabilization approach that official communications avoid. The primary fiscal surplus has required severe austerity that is hitting vulnerable populations hardest. Poverty and inequality metrics show regression past pre-crisis levels in several interior provinces. The alternative of gradual adjustment with growth-oriented fiscal policy exists in academic literature, but political feasibility under electoral cycles remains the bottleneck that makes comprehensive reform nearly impossible. For anyone tracking this space, the useful frameworks involve watching both the official rate and the financial dollar simultaneously. The gap between them signals market confidence levels better than any single indicator. Central bank reserve accumulation matters, but the composition of those reserves (short-term instruments versus strategic holdings) determines actual liquidity during stress periods.
Get the Full Details
The bond market restructuring continues to evolve. Holdouts and secondary market pricing reflect risk assessments that differ from sovereign credit ratings. I found that monitoring the CDS spread movement against the LEA rate provided earlier signals than official communications about debt sustainability. The energy sector transformation in Vaca Muerta is significant but takes years to materialize. Natural gas discoveries could make Argentina a net exporter within a decade, but pipeline infrastructure and LNG terminal construction face regulatory uncertainty that delays project financing by eighteen to twenty-four months per phase. Small economy participants adapt through informal arrangements that official statistics never capture. The parallel market premium acts as an implicit tax on formal transactions, pushing activity into unreported channels. I learned to track the true money supply by combining observed exchange rate movements with import volume data rather than relying on M1 or M2 reports that exclude significant dollarized holdings.
Practical Takeaways
Tracking Argentina requires looking beyond headline inflation numbers. The real indicators involve monitoring the blue dollar spread, tracking provincial fiscal transfers, and watching agricultural export volumes. These move on different timelines than official policy announcements. The current administration faces a narrow path between stabilization and social sustainability. Without addressing the root causes of currency weakness and fiscal dependency, gains remain fragile. The alternative frameworks involving gradual adjustment with growth-oriented industrial policy exist but require political consensus that electoral cycles make difficult to achieve. For investors and businesses operating here, the key is understanding which rate applies to which transaction. The official rate covers some imports and debt payments. The financial rate applies to securities and certain contracts. The MEP rate serves as the benchmark for many derivatives. Using the wrong framework can create unexpected exposure worth millions in a volatile environment.
The lithium opportunity is real but execution risk is high. Supply chain bottlenecks, environmental permitting delays, and infrastructure deficits mean projects often take thirty to forty percent longer than initial timelines suggest. Due diligence should focus on permit sequencing and offtake agreement structure rather than just resource estimates. Agricultural producers should consider forward pricing mechanisms that hedge against retention policy changes. The spread between domestic and international prices fluctuates based on exchange rate expectations and government intervention intensity. I use a combination of observed market rates and USDA weekly reports to calibrate my own hedging decisions rather than relying on official guidance alone. The social dimension cannot be ignored. Poverty rates above forty percent create demand-side constraints that affect all sectors. Consumer spending drives roughly sixty percent of GDP, so when real wages decline, the multiplier effect hits harder than standard models predict. Recovery depends on restoring purchasing power, not just maintaining fiscal targets.