Target Red Card and automatic bill payments
I was cleaning out my garage last March and found a stack of paper statements I hadn't bothered with for months. That's when I actually did the math on what the Red Card had been doing for me over the previous year. Not the discount at checkout, which people talk about constantly. The bill pay angle. My monthly recurring expenses — phone, internet, streaming subscriptions, even my car insurance — were sitting around four hundred dollars a month in automatic charges. I set up half of them through the Red Card dashboard and the rest I started paying with it when I remembered. The difference showed up in my cash flow within thirty days. Here is how it actually works, without the marketing spin. You get the Target Red Card at checkout or through the app. Two versions exist: the standard store card and the Target RedCard debit card linked to your checking account. The bill pay feature lives inside the Target Circle section of the app for most users, though it migrates around depending on your account status and state. You add a recurring payment — say, your $89 monthly phone bill or your $145 internet charge — and schedule it to hit on a specific date. The system pulls from the Red Card balance or your linked debit account. During the promotional period for a new card, that discount sometimes applies to online bill payments too, though the terms change every few months and the fine print explicitly limits where it applies. The part nobody mentions upfront is the timing mismatch. If your bills are spread across the 3rd, the 12th, and the 28th of the month, but your paycheck comes in on the 1st and 15th, you are running a tight positive float for maybe eight days between payments. The Red Card gives you a built-in grace period if you use the store card version, which matters more than the 5 percent discount for actual cash flow management. I learned this the hard way in 2022 when I scheduled three utilities on the same Tuesday and the overdraft fee hit before I caught it. Now I stagger them manually — one on the 2nd, one on the 8th, one on the 20th — even though the app would let me batch them.
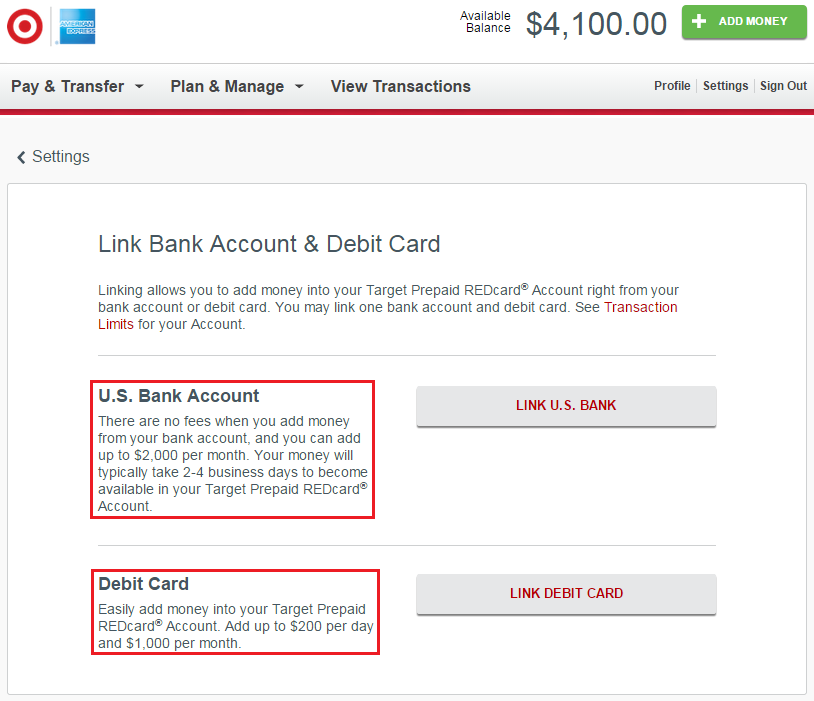
Counterintuitive insight: the 5 percent discount does not apply to all bill pay transactions. Target explicitly excludes certain merchant categories from the discount in their terms of service, and those categories shift. Insurance premiums have been excluded more often than not in recent years. Grocery purchases qualify, which most people already know. But cable companies, telecom providers, and utility firms — those get treated differently depending on the merchant category code they report to Target. I spent two weeks testing this by paying the same internet bill through the app and watching whether the 5 percent posted or not. It did not. Phone carriers are the same way. You have to check each payee individually before you rely on the discount for anything larger than twenty dollars a month. Another thing people miss: the Red Card debit version and the store card version handle bill pay scheduling differently. The debit card processes immediately against your checking balance, so there is no float benefit and no credit impact. The store card builds a minimum payment obligation each month, which means you are carrying a balance unless you pay it off in full. Some users think they are getting a free discount on bill pay when they are actually just accruing interest at 26 to 29 percent APR on a card that should already be paid. I see this on forums constantly. The sweet spot is using the store card for the 5 percent discount on Target purchases only, and using the debit card for bill pay where the discount may or may not apply anyway.
Setting it up without losing money
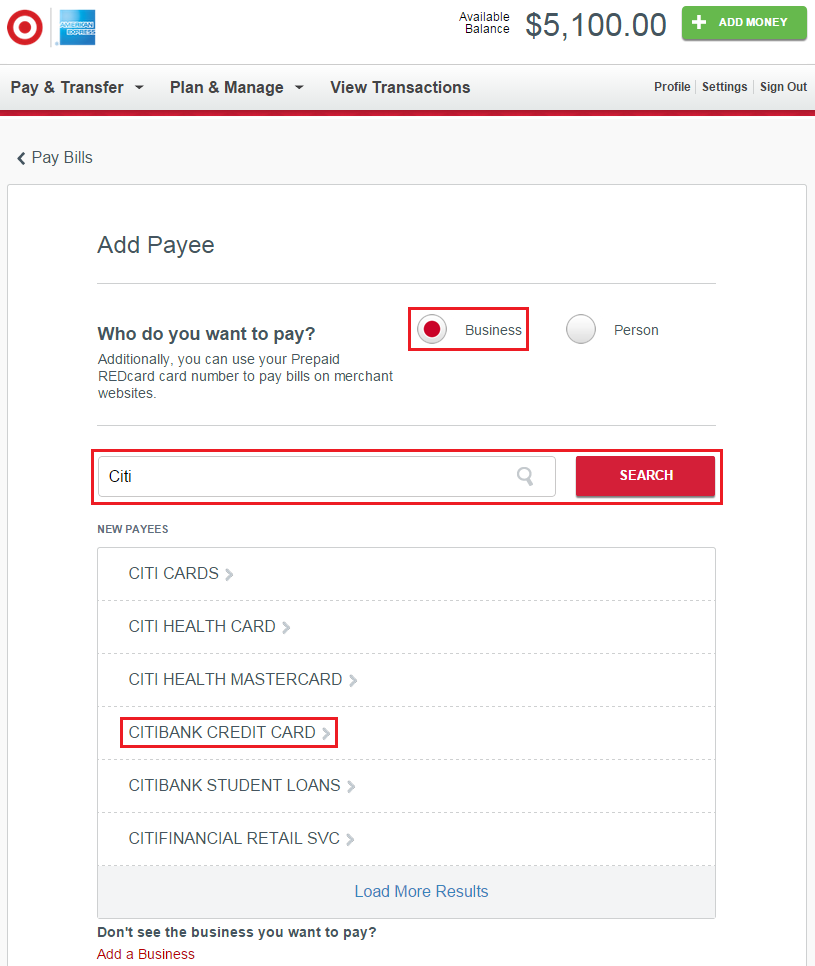
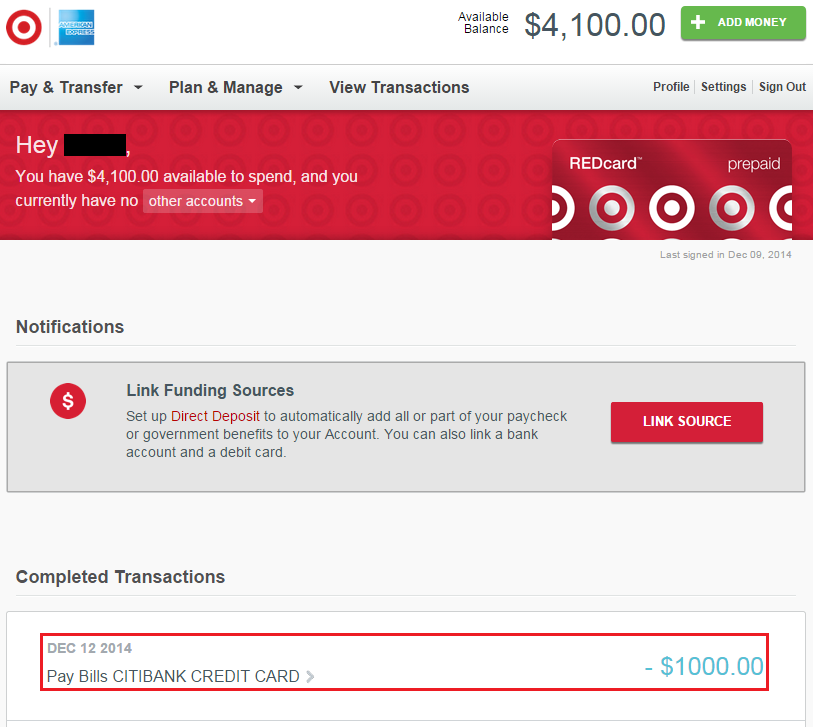
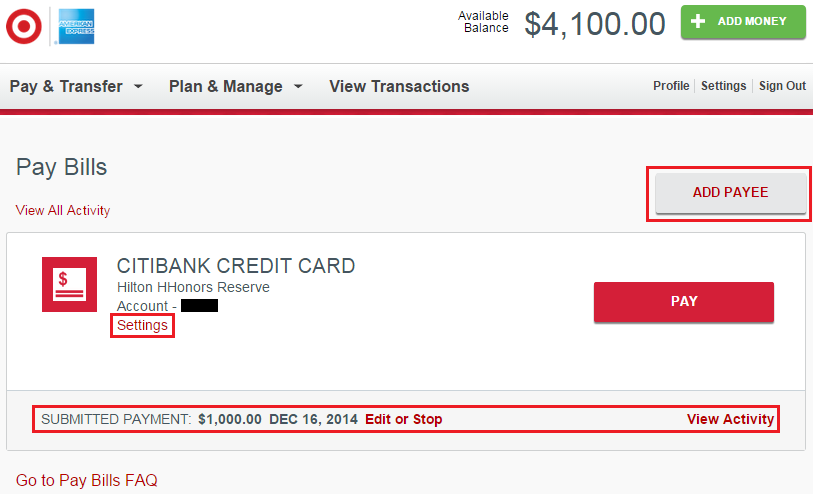
I walk through my current process. First, open the Target app and navigate to Payments under the Target Circle section. Add your recurring bills one at a time. Each one requires the payee name, account number, payment amount, and frequency. The app validates the account number against the payee's format in real time, which catches typos before they become problems. Some payees return errors that look permanent but are actually just wrong formatting — my cable company rejected my account number twice because the system wanted the billing ID, not the service contract number. Called customer service, got the right format, third attempt worked. For cash flow specifically, here is the practical move that matters. Set all automatic bills to pay three days before the actual due date. Most utilities and service providers charge a late fee after the due date, but they do not report to credit bureaus until thirty days past due. The three-day buffer catches any processing delays, failed ACH pulls, or bank holidays that push the payment through late. I once had a payment stuck in pending for eleven hours because my bank was doing end-of-day reconciliation on a Friday, and the system marked it as received Saturday morning. By then the grace window was already tight. Since switching to the three-day advance schedule, I have had zero late fees in fourteen months. The edge case that almost ruined this for me: auto-pay reconciliation errors. In August 2023, my internet provider posted a payment adjustment that conflicted with an automatic Red Card payment I had scheduled for the same month. Instead of paying my bill, the system applied the Red Card transaction as a refund, which reversed the charge and left my account in a weird intermediate state. I had to call two different support lines and fill out a dispute form to get it corrected. The workaround I use now is to confirm every automatic payment has posted to the payee's account before the due date, not just to see it go out from Target. A screenshot of the paid balance in your provider's portal is worth more than any app notification.
Get the Full Details
When it does not work
Be honest about the limitations. The Red Card bill pay feature does not support one-time emergency payments well. If your water bill spikes because of a leak and you need to pay extra that month, the app forces you through the recurring payment flow or the manual single-payment flow, and neither is fast. I have watched people sit on hold for forty minutes trying to override an automatic payment that already processed. If you need flexibility for variable bills, keep a separate payment method outside the Red Card system for those. The app also does not integrate with budgeting tools like Mint or YNAB for bill pay tracking, so you are manually recording everything if you want a complete picture. That is a real friction point for anyone doing serious cash flow analysis. The discount itself has a ceiling and exclusions that matter at scale. The 5 percent applies to eligible Target purchases only, not bill payments from most merchants. For someone with four hundred dollars in monthly recurring bills, that means you are relying on the float and scheduling benefits, not the discount, to improve your cash flow. If you misread the terms and expect a twenty dollar monthly saving on bills, you will be disappointed. The actual cash flow improvement comes from the predictability — knowing exactly when money leaves your account, staggering payments to avoid clustering, and using the grace period on the store card if you carry a balance strategically.
Alternatives worth considering
If your main goal is bill pay optimization rather than Target shopping discounts, a dedicated bill pay service or your bank's built-in scheduler usually handles variable amounts better. Chase, Bank of America, and Wells Fargo all offer free bill pay with scheduling controls, payment history tracking, and easier override processes for one-time adjustments. The Red Card makes sense as a secondary tool, not a primary one, unless you are already a heavy Target shopper and want to consolidate. I use both. The bank handles my mortgage and variable utilities. The Red Card handles my fixed monthly subscriptions and phone plan, because the scheduling interface is acceptable and the app notification system is decent enough for tracking. The bottom line without dressing it up: the Red Card bill pay feature is a functional tool for predictable recurring expenses, it gives you scheduling control that most people ignore, and it can prevent late fees if you set it up with a buffer. It is not a magic savings device. The discount is real but narrow in scope. The real value is structural — knowing your outflows in advance, spacing them across the month, and avoiding the accidental late fee that costs more than any 5 percent you would save on eligible purchases. I stopped treating it as a shortcut and started treating it as a scheduler, and that shift made the difference in my actual cash flow.