Understanding American Express Card Tiers
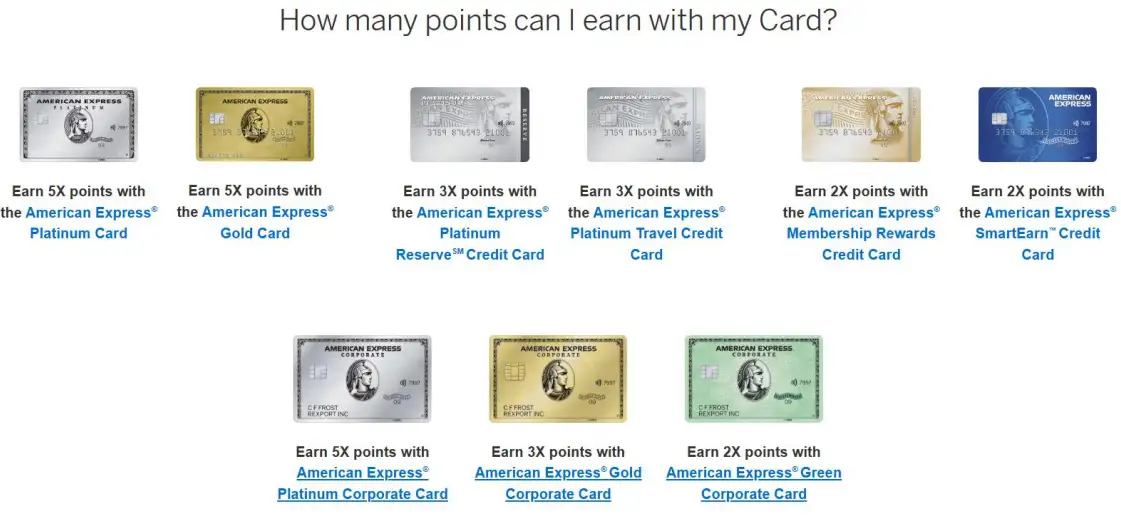
Most people have no idea how different the benefits actually are between Amex cards. They see the metal and assume they're basically the same. They're not. I've been dealing with credit card benefits and routing clients through various card stacks for about twelve years now, and the hierarchy here is actually pretty clean once you know what to look for.The American Express card lineup breaks into roughly five tiers, and each one gates access to a different set of perks. The gap between a Blue Card and a Platinum Card isn't incremental. It's generational. Let's start from the bottom. The Amex Blue Card is the no-fee entry point. It earns 1 point per dollar on everything except travel and groceries at 2 points. You get basic purchase protection, return protection on eligible items within 90 days, and some cell phone insurance up to $800 with a $50 deductible. That's it. The benefits are functional but thin. People keep this card around for the no annual fee and use it as a backup payment method. Nothing more. The Green Card replaced the old Simple Cash card and sits one level up. Still no annual fee. It earns 3x points on transit, including trains, buses, and ride shares, plus groceries at select US supermarkets and 1x everywhere else. You get the same purchase protections as Blue, plus extended warranty coverage that adds a year to eligible warranties. It's a solid everyday card but the earning rate on most purchases is underwhelming.
The Gold Card is where things start to matter. $250 annual fee, but it includes $120 in annual dining credits through the American Express Dining Collection and a $120 Uber Cash split across twelve months. You earn 4x points at restaurants worldwide and at US supermarkets up to $25,000 per year, then 1x after that. The 4x dining rate is genuinely useful if you eat out regularly. You also get trip delay insurance, purchase protection, and return protection. The card is targeted. It rewards a specific lifestyle pattern of dining and groceries. If you don't eat out much, you're paying $250 for modest benefits. The Platinum Card is the flagship. $695 annual fee. This is where lounge access enters the conversation, along with hotel elite status, airline fee credits, and a significant upgrade to travel protections. You get 5x points on flights booked directly with airlines or through Amex Travel, 5x on prepaid hotels, and 1x on everything else. The $200 airline fee credit covers incidental charges like checked bags and seat selection. There's also a $200 Hotel Credit through the Fine Hotels + Resorts program and a $189 CLEAR credit. The real value here depends on whether you actually use the travel benefits. If you fly domestically twice a year and never touch lounges, you're torching money. The Centurion Card is invitation-only. The annual fee starts around $5,000 and goes up from there. You need to spend somewhere in the range of $250,000 to $500,000 in a single year to be considered. The benefits are aggressive: unlimited Centurion Lounge access for you and two guests, Priority Pass membership, fine dining reservations, dedicated concierge, trip cancellation and interruption insurance up to $10,000 per trip, and a substantially higher credit limit than any other card. Most Centurion holders don't use half of what they're paying for. They carry it for the signal value and the occasional lounge visit.
Where The Real Differences Live
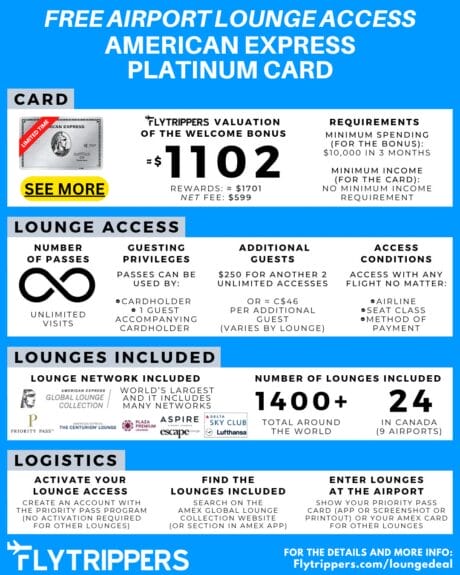
There are three benefit categories that separate these cards in ways most people overlook. Lounge access is the first and the most obvious gate. The Gold Card does not give you lounge access. Period. The Platinum Card gets you Centurion Lounge access, Priority Pass Select membership, and Delta Sky Club access when you're flying Delta on the same day. The Centurion Card gives you the same lounges plus a higher guest allowance and access to Partner Lounges that Platinum doesn't reach. If you've ever been stuck in a 6-hour layover at JFK with a Gold Card in your wallet, you understand the practical impact of this distinction. The second category is purchase and trip protections. These are not marketing fluff. I had a client who filed a $3,200 claim for a trip interrupted by a family emergency using his Platinum Card's trip cancellation insurance. The process took eleven business days from submission to reimbursement. The Gold Card's trip delay benefit kicks in after only a 6-hour delay and covers meals and lodging, but the coverage caps are significantly lower. The Platinum also includes Upgraded Car Rental Loss Damage Insurance, which is primary coverage up to the actual cash value of most vehicles in the US and Canada. This alone can save you from buying collision damage waiver at the rental counter. The third category is the concierge and experience access. Platinum and Centurion both offer concierge services, but the quality diverges sharply. Platinum concierge handles flight changes, restaurant bookings, and event tickets. Centurion concierge will arrange private museum tours, secure hard-to-get reservations at fully booked restaurants, and coordinate complex multi-city itineraries. I once needed to move a client's international shipment that had been delayed by customs. The Platinum concierge emailed me back saying they could not assist with logistics. The Centurion line got a call from someone who found an alternative shipping route within two hours. That's the difference between a call center script and an actual service.
Get the Full Details
A Specific Problem I Ran Into
Here's a concrete edge case. A few years ago, I was booking a trip for a group of four where one person held a Platinum Card and another held a Gold Card. We needed to use the Fine Hotels + Resorts benefit to get late checkout and a room upgrade. The Platinum benefit is well documented. The Gold Card does not include Fine Hotels + Resorts access. I spent about twenty minutes on the phone trying to figure out if there was any way to apply the benefit to both reservations since they were on the same booking reference. The agent was firm. The benefit ties to the card used for booking, and the Gold Card has no equivalent program. The workaround was simple but not obvious: book the Platinum reservation under the Platinum card, then book a separate room under the Gold card and accept that the second room would not include the benefit. It cost us one extra hour of planning and we lost the upgrade on the second room, but we avoided a potentially much larger issue at check-in. The most counter-intuitive thing about Amex card tiers is that carrying a higher-tier card does not automatically improve your experience on lower-tier purchases. The Amex system does not tier benefits within a single card. Your Gold Card does not get better purchase protection because you also own a Platinum. Each card operates independently. This means stacking them is the real strategy, not assuming the Platinum does everything for you. Another thing most people miss: the annual fee credits on Platinum and Gold expire at the end of each billing cycle. They do not roll over. I've seen people forget to use their Uber Cash or dining credits and then complain the card isn't worth the fee. The credits are structured as usage incentives, not rebates. If you don't use them within the year, they vanish. This is by design. The card is pricing you for behavior, not for ownership.
When Amex Card Tiers Fail You
The system has real limitations. The Platinum Card's $200 airline fee credit only applies to fees charged by the airline you select as your primary carrier. If you fly a budget carrier that doesn't charge for checked bags or seat selection, the credit goes unused. The $200 Hotel Credit only works on eligible bookings through Fine Hotels + Resorts or The Hotel Collection, and it applies only to incidentals, not the room rate itself. Some people misread this and expect a $200 discount off the nightly rate. It doesn't work that way. The Centurion Card's concierge is excellent but not infallible. I tried to use it to secure a last-minute table at a restaurant in London during a food festival where every venue was booked solid. The concierge called three establishments and returned with two rejections and one offer that was a completely different restaurant than what I wanted. The Platinum concierge would have given the same answer. The difference is scale and speed, not capability. For rare, high-difficulty requests, Centurion has a better hit rate, but it's not magic. If you're spending under $30,000 annually and you don't fly more than a couple times a year, the Platinum Card is almost certainly not worth it. The math doesn't work. You'd need to use roughly $400 worth of the annual credits to break even on the $695 fee, and that assumes you actually use every credit. Most people don't. A Gold or Green card paired with a no-fee Amex for everyday purchases covers the same ground for a fraction of the cost.
For most people, the optimal stack is a Green or Gold card for daily spending plus a Platinum card if you fly commercially more than four times a year and actually use lounge access. Everything below Gold is a utility card. Everything above Platinum is a lifestyle signal with some genuine travel benefits attached. Know which bucket you're in before you apply.