Understanding commission structures on the lot
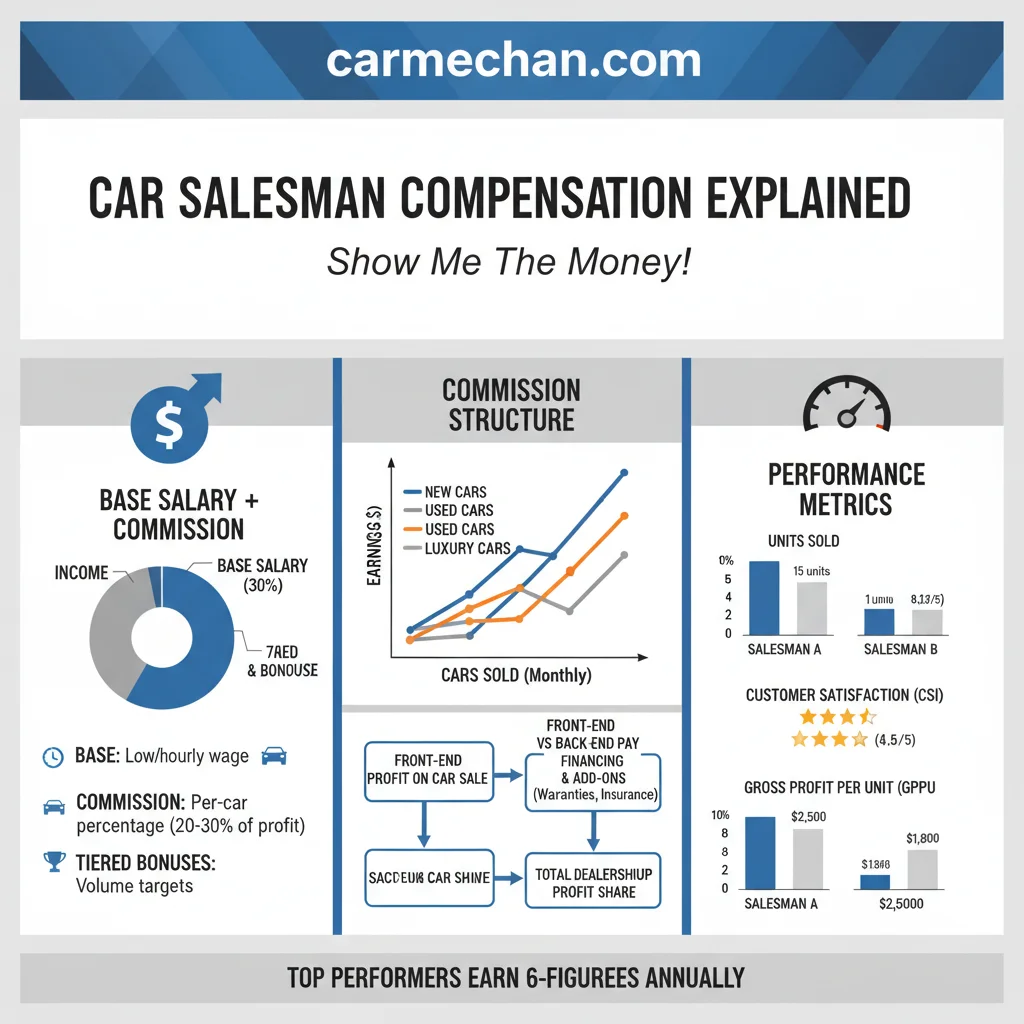
Most people think car salespeople make money the same way, and that's because they're mostly right. The paycheck comes from commission, not salary, and it's calculated as a percentage of the gross profit on each vehicle you sell. That gross profit is the difference between what the dealer paid for the car and what they sold it for, including any add-ons attached to the deal. Here's how it actually works in practice. You walk into a used car lot and pick up a trade-in or pull a unit from auction. Let's say that car cost the dealership $18,500 after reconditioning. You sell it for $22,000. That's $3,500 in gross profit. Your commission rate might be somewhere between 20 and 27 percent of that gross profit, depending on the dealership and your seniority tier. So on that one sale, you're looking at roughly $700 to $945 before taxes and deductions. Multiply that by however many cars you close in a month and you've got your paycheck. There's a layer most buyers never see, and it's where experienced salespeople either thrive or get burned. The gross profit number isn't just the difference between the wholesale acquisition price and the retail sale price. It includes the margin on every add-on product you stack on top of the deal. Extended warranties, paint protection, tire and wheel packages, dealer-installed accessories, GAP insurance coordination, those all feed into the gross profit calculation, which then feeds into your commission check. A lot of rookie salespeople leave money on the table because they treat add-ons as separate from the commission math. They're not. They directly increase the gross profit base your percentage is applied to.
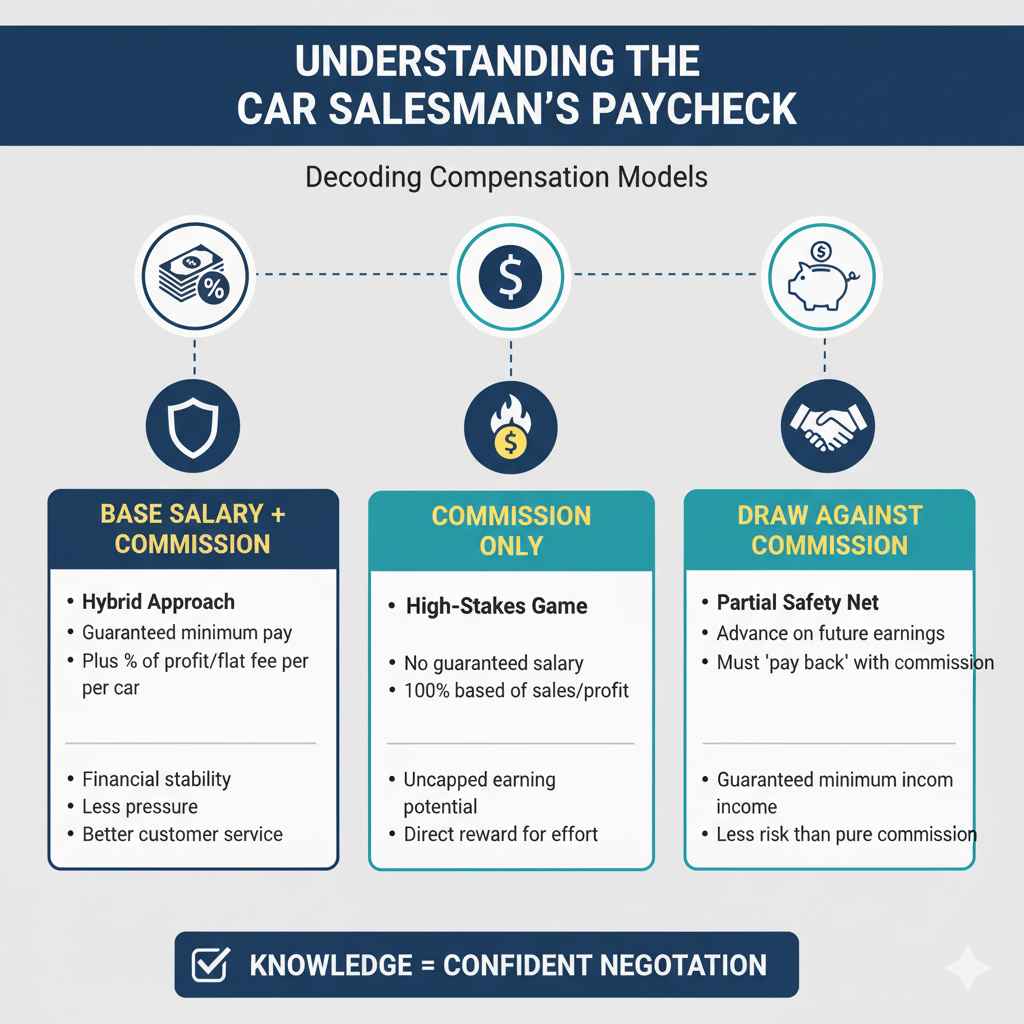
I learned this the hard way in my second year. I was working a place that used what they called a tiered gross profit pool. Your commission rate climbed the higher your average gross profit per deal went. At 400 bucks per deal average you were on one rate, at 600 you jumped to a higher bracket, at 800 you were in the top tier. I was closing numbers fine but my gross profit per deal sat around 350 because I kept leaving four figures on the table in documentation fees and processing charges instead of factoring them into the overall deal structure. My manager showed me how tracking that metric in real time could push me from the middle bracket into the top one, and the difference was maybe $400 to $600 a month just from adjusting how I presented fees rather than from selling more cars. I started using a simple running spreadsheet to log every deal's components as I worked it, and that visibility alone improved my close ratio because I stopped giving away concessions I didn't need to give. Now let's talk about the parts people misunderstand. Commission is usually paid on the day you close, but the actual payout often gets held back 30 to 45 days. That's because the dealer needs to confirm the title transfers cleanly, the finance company funds without a last-minute cancellation, and there's no repossessing or buyback issue coming down the pipeline. If a customer returns a car within the state's return window or the lender has a problem with the paperwork, your commission gets clawed back. I had a deal fall apart three weeks later because the buyer's credit profile changed between approval and funding. The finance company pulled the plug, the car came back into inventory, and my commission disappeared with it. That's just how it works. You learn to budget around it. Some dealerships run a flat percentage model where you get a set rate on every sale regardless of volume. Others use a graduated scale that rewards higher performers with steeper percentages after certain thresholds. A few places still use hourly wage plus a small per-sale bonus, which is more common at volume-focused dealerships that move metal on thin margins. The hourly-plus-model pays less per car but gives you income stability during slow months. The commission-only route is higher ceiling but you eat harder when the lot is empty.
There's also the matter of new versus used. New car commissions tend to be lower percentage-wise because the gross profit per unit is smaller. You're moving higher volume on thinner margins. Used cars pay more per deal because the gross profit spread is wider, but the volume is slower and the reconditioning risk falls partly on your side of the desk when things go wrong after the sale. One thing nobody tells you about this job is how much your actual take-home depends on the floor plan interest structure the dealership carries. If the dealer is carrying a heavy loan against their inventory and they're paying significant floor plan interest, they'll tighten the numbers on your commission to protect their bottom line. You might see your rate drop a point or two during tough inventory financing periods. It happens quietly. You don't get a memo. You just notice your checks are smaller than they were six months ago even though you're selling the same number of cars at the same prices. The other nuance is group deals. When two salespeople work a single transaction, the commission gets split, usually evenly unless the dealership has a documented split agreement on file. I've seen this cause problems when the second person's name was on the paperwork but they contributed nothing to the actual sale. The commission still goes to whoever is listed on the deal sheet. It's worth clarifying who's carrying what before you agree to co-sell with someone.
Get the Full Details
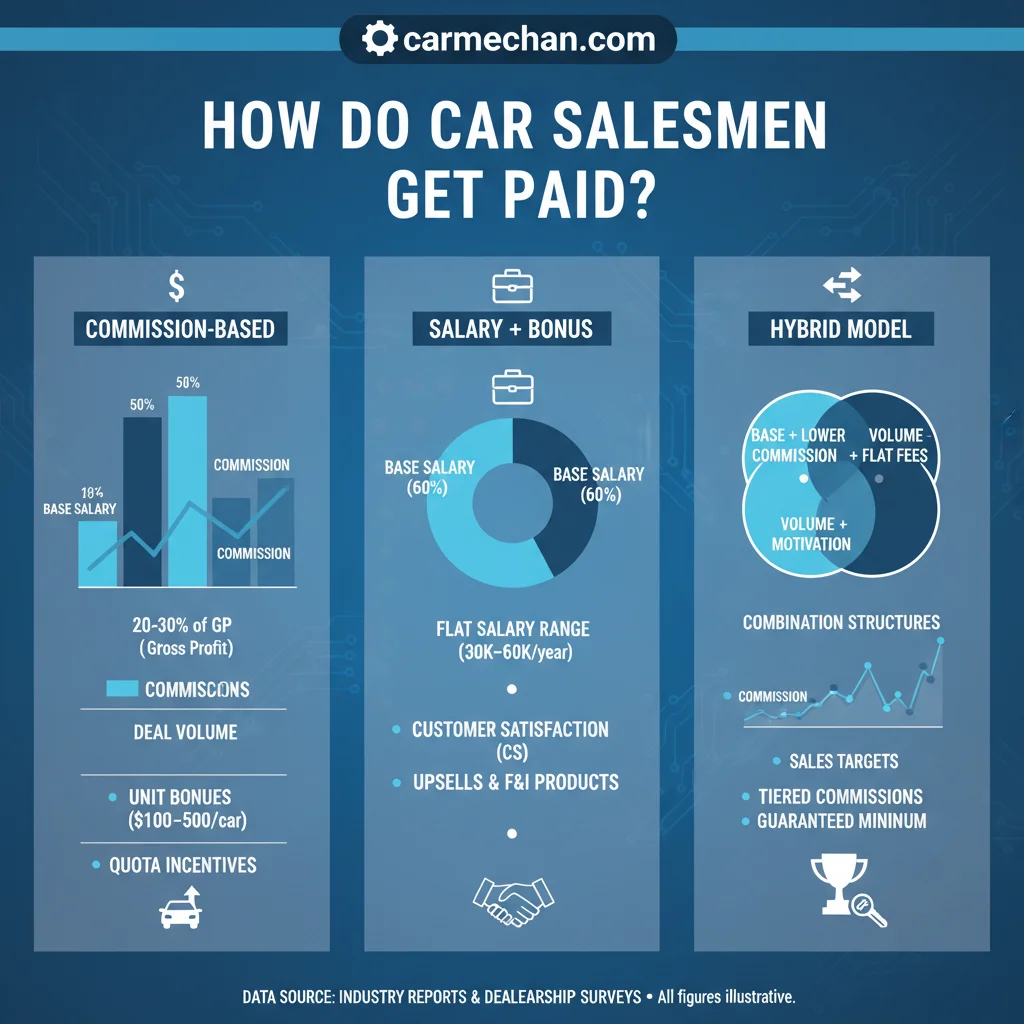
If you're looking at getting into this, the practical advice is straightforward. Ask about the commission structure during the interview. Get it in writing. Find out whether it's gross profit based or a flat percentage of the sale price, what the tier thresholds are, how add-on products factor in, when commissions actually pay out, and what the clawback policy is. Don't assume everything is standard across lots. It isn't. Two dealerships three miles apart can have completely different compensation models that produce wildly different yearly incomes for the same level of performance. I've seen salespeople make under 30k in a year and I've seen others clear well over 100k. The gap isn't usually talent. It's understanding how the commission engine works and optimizing every variable they can control. Fee structures, add-on attachment rates, gross profit tracking, knowing when to walk away from a deal that looks good on the surface but destroys your margin, reading the finance product stack before you present numbers to a customer. Those are the skills that separate consistent earners from people who are busy but broke at the end of the month.