What Wakid Actually Is
Wakid is a mobile superapp built for Southeast and South Asian markets that bundles payment, delivery, ride-hailing, bill payments, and a handful of other daily services into one package. It started as a digital wallet and grew into something that tries to handle every transaction you'd normally split across five different apps. The model is similar to Grab, Gojek, or WeChat, just targeting a slightly different regional corridor where penetration rates for formal banking are still climbing. I first encountered Wakid about two years ago when I was coordinating logistics for a small project team in Kuala Lumpur. Everyone had a different app for food, a different one for transport, another for transit fare. A coworker handed me his phone to show me the Wakid dashboard and I spent maybe ten minutes figuring out that I could pay for a ride, order lunch, and top up my phone plan without switching contexts once. That was the pitch and it mostly holds up. The core architecture runs on a unified identity layer. One account, one KYC profile, and a closed-loop wallet that can move money between services without hitting a traditional bank transfer. That's where the speed comes from. When you pay a merchant through Wakid, the settlement happens internally at the app level instead of waiting on interbank clearing. For small-value transactions, which make up the bulk of daily use, that difference is noticeable. Payments that would normally take 24 hours for bank-to-bank settle in under a minute inside the app.
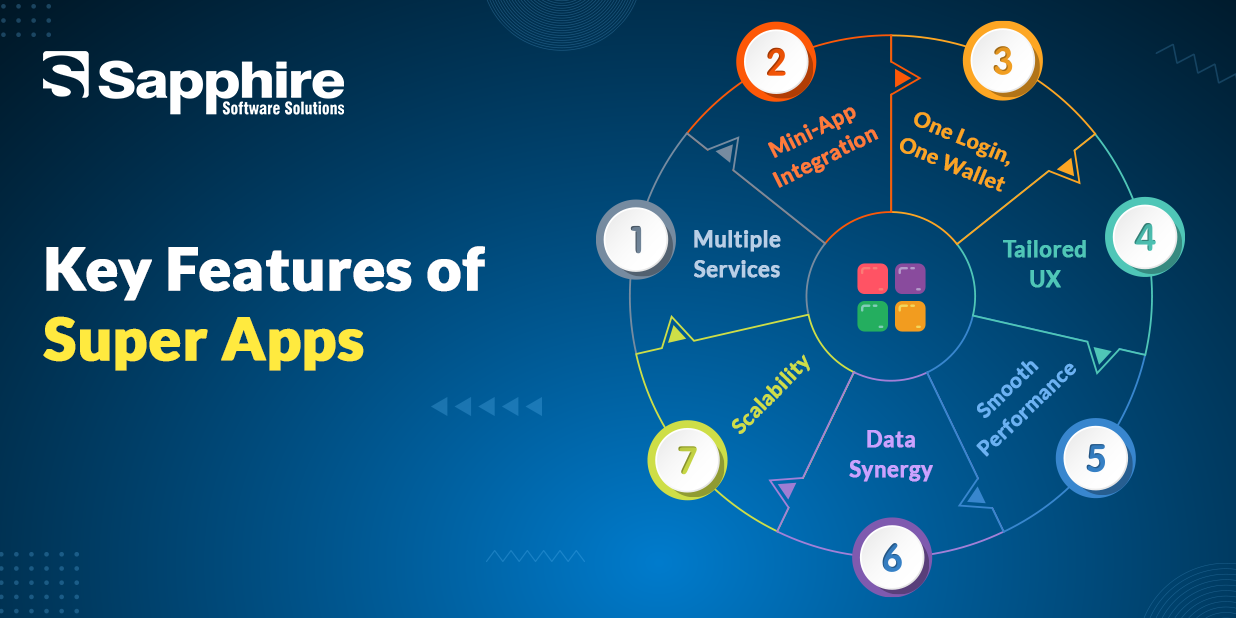
The service mesh is where it gets interesting. Wakid treats each vertical ride-hailing, food delivery, grocery, pharmacy, bill payment as a separate business unit but routes them through the same authentication and payment pipeline. That means your rider rating, your payment history, and your loyalty points all feed into a single reputation score. The app uses that composite score to decide things like priority support queue placement, loan eligibility, and even pricing tier for certain services. It's not a rating system you can see directly. You just feel it when one account gets you faster responses than another.
Getting Started And Installing It
Download the app from the official store for your region. The link on their website redirects to the appropriate app store based on your IP location. Once installed, you register with a mobile number and complete KYC by uploading a government ID and taking a selfie for facial matching. The verification usually completes within an hour during business hours but can drag to two or three days if the ID image quality is poor or if there's a name mismatch with your bank records. Fund the wallet using a linked bank account, debit card, or one of the accepted e-wallet partners in your country. Minimum initial funding tends to be around 10 to 20 units of local currency depending on the region. I'd recommend starting with a small amount just to test the payment flow before linking anything substantial. The interface organizes services into a grid on the home screen. The top row always shows your most-used services based on your usage history. You can reorder these by long-pressing an icon and dragging it. The settings menu lives in the profile tab and contains everything from payment preferences to notification controls to the privacy dashboard where you can export your data.
Get the Full Details

Practical Use Cases
The most common workflow I use is ride-hailing combined with food ordering. Book a ride to a restaurant, then order food for pickup while the driver is en route. The app handles the timing reasonably well. It won't match exact minutes but it will alert the merchant when your ride is five minutes out so your food is ready when you arrive. This saves maybe ten to fifteen minutes compared to doing each task separately. Bill payments through Wakid cover utilities, telecommunications, education fees, and government fines in most supported countries. The processing time for a bill payment varies by provider. Telecom top-ups are instant. Electricity bills can take anywhere from a few minutes to several hours depending on the utility company's integration status with Wakid's API layer. Wakid also offers a micro-lending product called Wakid Pay Later. It extends a credit line based on your transaction history and repayment behavior inside the app. The approval is automated and decisions come within seconds. Interest rates run higher than conventional personal loans but the convenience factor is real for emergency expenses where a bank application would take weeks.
A Specific Problem I Ran Into And The Workaround
Last year I was trying to use Wakid Pay Later to cover a hotel booking in Jakarta. The transaction went through on the app side but the hotel's property management system never received the confirmation. I had the receipt, the reference number, everything. The hotel claimed no record of the booking. This turned into a three-day email chain with Wakid support and the hotel's reservations desk. The issue traced back to a mismatch between Wakid's payment settlement cycle and the hotel's offline booking cutoff times. Wakid settles Pay Later transactions in batches rather than instantly, and the batch I triggered missed the hotel's end-of-day processing window. My workaround was simple enough but not obvious from the help articles. I switched to using my direct wallet balance instead of Pay Later for any booking that required same-day confirmation. The wallet funds settle immediately and the merchant receives the authorization in real time. It's a minor inconvenience to keep a funded balance but it avoids the batch processing trap entirely.
Things People Miss About How It Works
Most users don't realize that their behavior inside Wakid is feeding a proprietary risk model that affects more than just loan eligibility. The app tracks things like your typical transaction amounts, your geolocation patterns, your device change frequency, and even the time of day you make purchases. This behavioral biometric data gets used for fraud detection but it also quietly adjusts your service availability. If the model flags unusual activity, you might find certain features temporarily restricted without any explicit warning. The only way to resolve it is through the in-app support chat, which can take several hours to a full business day to respond depending on volume. Another overlooked detail is how the loyalty program, Wakid Coins, actually compounds. Coins earn a small discount on your next transaction but they expire 180 days after issuance. Most people accumulate coins slowly and forget about them until they expire. I started tracking my coin balance monthly and batching my purchases to maximize the discount window. It saves maybe three to five percent on recurring expenses, which adds up over a year.
Where Wakid Falls Short
Customer support is the weakest point. The in-app chat is the primary channel and response times vary wildly. During peak hours, which in Southeast Asia often means between 7 PM and 10 PM local time, you can wait forty-five minutes or more for a human agent. The AI chatbot handles about sixty percent of routine queries but it frequently fails on edge cases involving payment disputes or account verification issues. Geographic coverage remains uneven. Wakid works well in its core markets but international transactions and cross-border remittances are either unavailable or subject to high fees. If you need to send money to family in a neighboring country, check the fee schedule first. Some routes cost eight to twelve percent in combined transfer and FX fees, which makes traditional remittance channels like Wise or Payoneer significantly cheaper for the same transfer. Data privacy is a legitimate concern. Wakid collects more personal data than most utility apps because it serves as a financial identity anchor. Your transaction history, location data, contact list imports, and device information are all stored on their servers. The privacy policy is lengthy and not particularly transparent about third-party data sharing with partner merchants. I'd recommend reviewing the permissions you grant during setup and disabling contact list access if you don't need the contact-matching feature for peer-to-peer payments.
Who Should Use It And Who Shouldn't
Wakid makes sense if you live in or frequently travel to its core markets and want a single app for daily transactions. The convenience of consolidated payments and the speed of internal settlement are real advantages. If you're comfortable with the data trade-offs and you keep a funded wallet balance to avoid the Pay Later batch processing issue, it works well for routine use. It does not make sense if you prioritize data minimization, need reliable cross-border remittance, or require guaranteed same-day customer support resolution. For those needs, sticking with specialized apps for each function or using a traditional bank's digital platform would serve you better. Wakid is a convenience play, not a comprehensive financial solution. I've been using it daily for about two years now. The app has improved steadily but it still has rough edges, particularly around dispute resolution and cross-service consistency. The fundamental idea is sound and the execution is good enough that I haven't bothered switching to a different superapp despite the alternatives on the market.