The Rise Of Sustainable Aviation How Biofuels Are Revolutionizing The Industry
Samantha
2025-08-26
Understanding Sustainable Aviation Fuel
Most people think biofuels for airplanes are some futuristic concept still decades away. They are not. Commercial flights have been burning biofuel blends for years now. The fuel comes from things like used cooking oil, animal fat, and certain plant crops. It gets refined into jet fuel through processes that chemistry engineers have been refining since the 2000s.
The actual blend ratio matters more than most public discussions acknowledge. Boeing and Airbus certify their aircraft to burn up to 50 percent biofuel mix. Anything above that requires additional testing and usually stays in the experimental or military space. When you see a flight marketing itself as "carbon neutral," what they usually mean is they burned a 50-50 SAF blend and bought offsets somewhere.
The Rise Of Sustainable Aviation How Biofuels Are Revolutionizing The Industry
How The Fuel Actually Gets Produced
There are several production pathways, and they matter because they determine the carbon footprint of the end product. HEFA, or Hydroprocessed Esters and Fatty Acids, is by far the dominant method right now. It turns waste oils and fats into hydrocarbon chains that meet Jet A-1 specifications. This pathway accounts for roughly 85 percent of current SAF production globally.
The other methods are more interesting technically but face scale problems. ATJ, or Alcohol-to-Jet, converts ethanol or methanol into jet fuel. It requires dedicated alcohol supply chains that simply do not exist at aviation scale yet. Power-to-Liquid uses captured CO2 and green hydrogen to synthesize hydrocarbons. It works in a lab. Scaling it to move commercial airlines forward is another question entirely.
I worked on a project evaluating SAF for a mid-sized regional carrier a few years back. The specific edge case we hit was cold-weather certification. Some biofuel blends derived from certain feedstocks had poorer low-temperature flow properties than conventional Jet A-1. At altitudes above 35,000 feet where fuel temperature drops below minus 40 degrees Celsius, certain blends started precipitating wax crystals that could clog filters. The workaround involved modifying the hydrotreating process to increase iso-paraffin content, which depressed the pour point without sacrificing energy density. It added about 8 percent to the per-gallon cost of that particular batch.
Carbon Accounting And Actual Emissions Impact
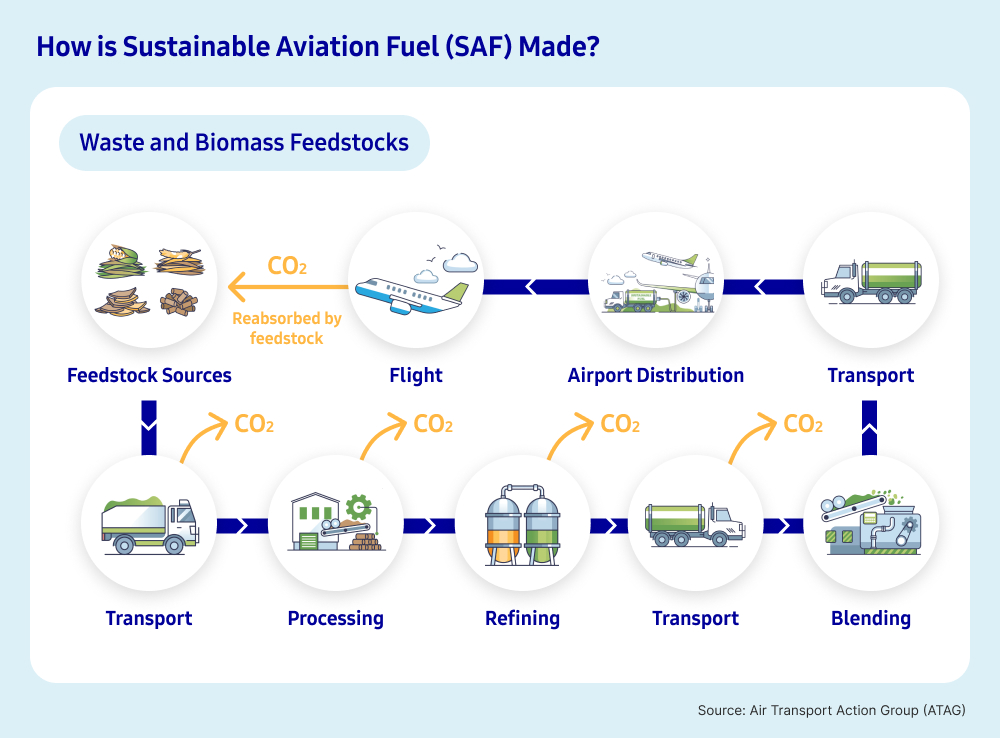
Lifecycle emissions reductions for SAF vary dramatically depending on the feedstock and pathway. HEFA from used cooking oil typically delivers around 65 to 80 percent lifecycle emissions reduction compared to conventional jet fuel. This number comes from the full chain: feedstock production, collection, transport, refining, and combustion. The feedstock sourcing is where things get messy and where greenwashing tends to happen.
Certain crop-derived biofuels, especially those from palm oil or soy, can actually have worse lifecycle emissions than fossil jet fuel when you factor in land-use change and agricultural inputs. I ran into this directly when a client wanted to tout a 90 percent emissions reduction claim. The underlying fuel was HEFA from virgin vegetable oil, not waste oil. The difference between waste feedstock and virgin feedstock in HEFA can shift the lifecycle number by 20 to 30 percentage points. That single feedstock detail changes whether the fuel qualifies for certain regulatory credits or incentive programs.
The European Union revised its Renewable Energy Directive accounting methodology recently to reflect these discrepancies more accurately. Feedstocks that cause indirect land-use change now receive penalized credit values. Airlines operating into EU airports need to track not just the volume of SAF they purchase but the specific pathway and feedstock certification behind each batch.
Cost And Supply Constraints
SAF costs between two and four times conventional jet fuel depending on pathway, region, and volume commitments. HEFA from waste oils is at the cheaper end of that range because the feedstock is essentially a waste product with existing collection infrastructure. Pathways requiring dedicated agricultural production or electrofuels sit at the expensive end.
Global SAF production in 2023 was roughly 500 million liters. Commercial aviation consumes about 3.5 million barrels per day, which translates to roughly 175 billion liters annually. The gap is enormous. Even under aggressive growth scenarios projected by the International Air Transport Association, SAF is not expected to meet more than 10 to 15 percent of total aviation fuel demand by 2030.
The bottleneck is not technology. It is feedstock availability and refining capacity. Waste oils and fats are finite resources with competing demands from the food, chemical, and biodiesel industries. Expanding production of drop-in SAF faster than current projections require means either directing more agricultural land toward fuel crops, which carries its own environmental trade-offs, or accelerating development of synthetic pathways that remain significantly more expensive.
Operational Considerations For Airlines
SAF is a drop-in fuel. It meets the same specifications as conventional jet fuel and can be blended at any ratio up to the certified maximum without modifying aircraft engines or ground handling infrastructure. This simplicity is why the industry has adopted it faster than alternative propulsion concepts like hydrogen or battery electric.
The operational reality is less clean than the specification sheet suggests. SAF supply is inconsistent geographically. Major hubs like Amsterdam, Oslo, and San Francisco have relatively reliable access. Most other airports worldwide have little to no SAF availability. Airlines need to either commit to blending at specific hub airports and loading non-blended fuel elsewhere, or invest in certified on-site blending equipment at multiple stations, which carries significant capital expenditure.
Fuel density differences between SAF batches can also affect payload-range calculations. Some SAF variants have slightly lower energy content by volume than standard Jet A-1. For long-haul operations where fuel weight is already a dominant constraint, even a 1 to 2 percent reduction in energy density can shave meaningful payload off the manifest. Airlines typically absorb this through minor schedule adjustments or reduced cargo capacity rather than accepting the fuel as-is.
What The Future Actually Looks Like
The next five years will likely see continued dominance of HEFA pathway SAF with modest cost improvements as refining capacity expands. Policy mandates in the EU and California are driving demand regardless of price, which creates a stable but limited market. Beyond HEFA, the industry is watching ATJ and PtL pathways develop, but neither is anywhere near cost-competitive with current options.
Hydrogen and battery electric propulsion remain important research directions but are constrained by fundamental energy density physics. Liquid hydrogen has excellent energy per kilogram but terrible energy per liter and requires cryogenic storage systems that add significant weight and complexity. Batteries are even more constrained by their current energy density limits. For the foreseeable future, most of aviation's decarbonization will come from SAF, and the rate of that transition is primarily a function of feedstock logistics and policy, not engineering breakthroughs.
Airlines that treat SAF procurement as a simple purchasing decision rather than a strategic supply-chain operation will find themselves consistently displaced by competitors who locked in longer-term offtake agreements and diversified their sourcing across pathways and geographies. The technical side of the fuel itself is well understood. The operational and economic side is where the actual competitive advantage gets determined.
Gallery The Rise Of Sustainable Aviation How Biofuels Are Revolutionizing The Industry
Sustainable Aviation Fuel Initiative | Department of Energy
Sustainable Aviation Fuel: The Key to Decarbonizing Air Travel ...
SAF, sustainable aviation fuel: what is the biofuel produced from ...
How Sustainable Aviation Will Make Our Skies Green
KBR launches sustainable aviation fuel technology in alliance with ...