Section 8 isn't what most landlords think it is
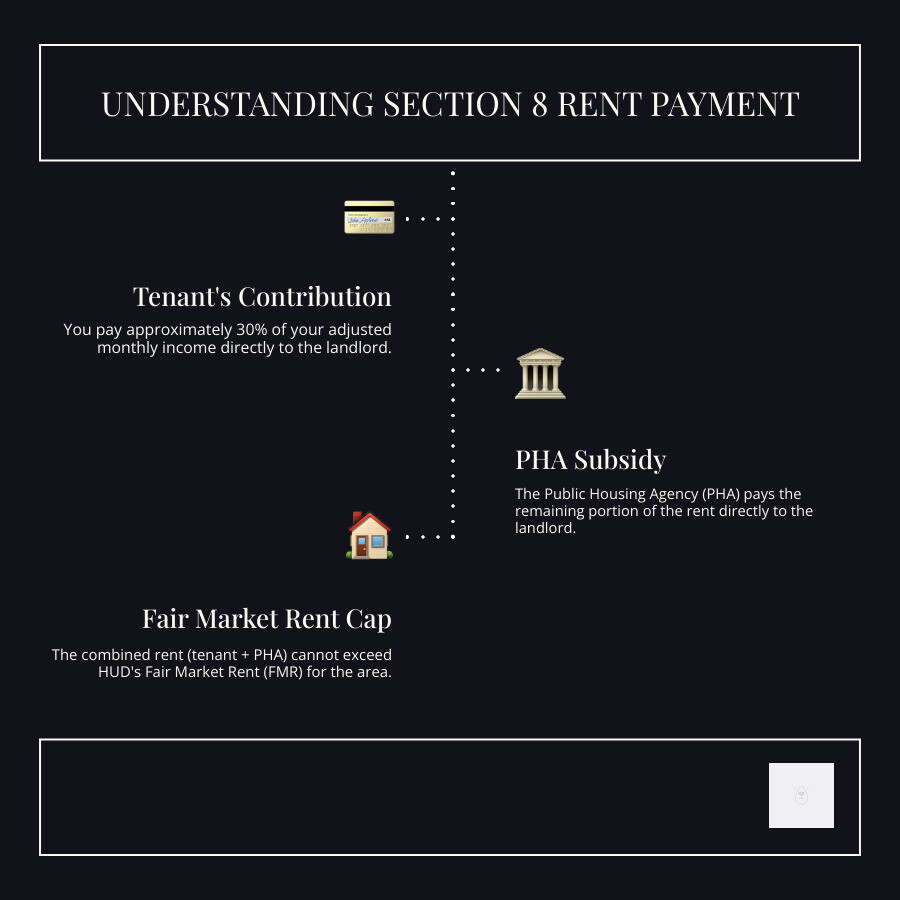
The voucher program has grown substantially over the past decade, and the conversation around it has gotten louder on investment forums. A lot of people approach this assuming it's straightforward passive income. It's not, and the gap between expectation and reality is where most landlords lose money before the first tenant even moves in. Section 8, officially called the Housing Choice Voucher Program, works through a three-way agreement. The tenant applies for a voucher through their local public housing authority. Once approved, they find a unit they can afford. The landlord signs a contract with the PHA and the tenant, agreeing to rent the unit at a price the PHA determines is reasonable. The government portion of the rent goes directly to you from the agency. The tenant pays the remainder, which is calculated as 30% of their adjusted monthly income. That's the basic structure. The part nobody emphasizes enough is that the PHA sets an upper limit called the Fair Market Rent for your zip code, and you generally can't charge above that number for a voucher unit. I learned the hard way that inspection requirements vary significantly between jurisdictions even within the same county. One PHA in central Texas required deadbolts on every exterior door and CO detectors on each floor. Another agency forty miles away had none of those requirements. The paperwork alone usually takes me about an hour per application if everything is in order. If the tenant needs to provide additional income documentation or the property fails initial inspection, that stretches to three to four hours of back-and-forth.
Here's a practical issue that doesn't show up in any overview article: the HAP contract payment timing. The government portion of your rent arrives on a set date, but tenants frequently pay their portion late. A tenant who earns minimum wage might consistently be short by $50 to $120 each month. You collect late fees, sure, but the administrative cost of chasing that and processing partial payments adds up. I stopped offering late fees on voucher tenants because the collection process takes longer than the fee is worth and most PHAs won't garnish the government portion to cover a tenant debt anyway. You absorb the late payment or you start the eviction process, which is where it gets expensive fast. The re-inspection cycle is another detail that matters more than people realize. Properties get inspected annually, sometimes twice a year depending on the PHA. A crack in a window screen or a missing cover on an electrical outlet can flag a violation. I started doing a walkthrough using a checklist based on the local PHA's HQS standards before scheduling the official inspection. It cuts the fail rate down to almost zero and saves roughly two weeks of delays per inspection cycle. One edge case I ran into involved a unit with an unfinished basement. The tenant had already moved in and I hadn't considered the basement during initial screening. The inspector marked it as an issue because the stairs didn't meet code for a habitable space. I couldn't just close it off with a curtain—the PHA requires proper separation. I ended up installing a half-door and latching gate on the stairway, which cost about $180 and took an afternoon. A cheaper approach would have been to exclude the basement entirely from the unit description on the lease, but the tenant was already living in it and had stored belongings down there, so that wasn't really an option.
The geographic limitation is real and often overlooked. Each PHA has its own service area, and vouchers are only portable between jurisdictions if both agencies agree. A tenant with a voucher from one city can move to another, but the receiving PHA has to confirm they have the capacity to manage the case. In practice this means you're limited to tenants in your local market or someone willing to deal with the portability paperwork, which takes an additional three to six weeks. There's also the matter of turnover. Section 8 tenants tend to stay longer than market-rate tenants because finding a new voucher-accepting landlord is difficult. The average tenancy runs two to four years in my experience. That's a genuine advantage, but it's not guaranteed. A tenant can terminate the lease with thirty days' written notice at any point, and the voucher doesn't transfer to a new unit unless the tenant finds another landlord willing to accept it before the voucher expires. Vouchers have a ten-day window after the tenant finds a new place to complete the lease-up, or the voucher goes back to the PHA and you're starting over. The screening process itself is simpler than traditional rentals in some ways because the PHA already runs criminal background checks and verifies income. But you still have to do your own screening. The PHA won't block a tenant for a past eviction or a poor credit score—those decisions are yours. I've seen landlords skip this step and regret it. A tenant with a clean voucher history can still damage a property or fail to maintain it to HHS standards, and you're the one who responds to the inspection failure, not the tenant.
Get the Full Details

The biggest bottleneck by far is the waiting list. Many PHAs have waitlists that are years long and occasionally close entirely. If you're hoping to fill a vacancy with a voucher holder, you should contact the local PHA first and confirm they're actively issuing vouchers in your area. Some agencies haven't issued a new voucher in over a year due to funding constraints or backlog. Approaching a landlord with a voucher from a closed agency is a waste of time for everyone involved. Another counter-intuitive point: the rent reasonableness test. The PHA compares your asking rent to comparable units in the area that don't accept vouchers. If your unit is newly renovated and you're charging $1,500 but similar unrenovated units nearby rent for $1,200, the PHA will likely cap your approved rent at $1,200 or slightly above. You can't inflate the rent to make up for a lower tenant contribution. This is the single most common misunderstanding among new Section 8 landlords. The program protects the tenant from overpaying, not the landlord from underpricing. If you decide to pursue this, the practical first step is calling your local PHA and asking for their landlord orientation packet. Most have one, and it lists the exact documents you need, the inspection criteria, and the current payment processing timeline. Websites like hud.gov have a locator tool, but the information on those pages is generic. The actual requirements come from the local agency, and they differ enough that relying on federal summaries will leave you unprepared.