The Texture Problem Nobody Talks About
The plant-based sector wasn't built on marketing budgets. It was built in R&D labs by people who understood food chemistry at a granular level. The real story starts around 2011, when a handful of founders at Impossible Foods and Beyond Meat discovered that existing food science tools—extrusion, fermentation, lipid encapsulation—could be recombined to solve problems the meat industry considered impossible. Most people outside the industry don't realize how much of this was purely applied biochemistry, not philosophy or mission. I spent three years advising a mid-size dairy processor trying to launch a plant-based cheese line. We hit a wall with texture stabilization that almost killed the project. The pea protein isolate kept seizing up during high-shear mixing, creating a grainy mouthfeel that registered as clearly inferior to the dairy version. The workaround ended up being a two-stage emulsification process using sodium citrate at 68 degrees Celsius before any protein was introduced, which binds the calcium in the peas and prevents that gritty precipitation. It added forty minutes to the batch cycle but made the product saleable. This was a company that had already spent two million dollars before we found the fix.
The Rise Of Plantbased Everything How A Small Group Of Innovators Sparked A Global Food Revolution
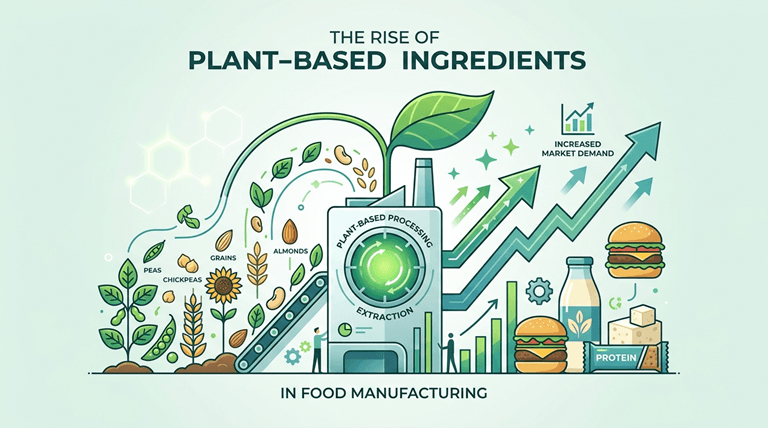
The core mechanism that made this possible was hemicellulose extraction combined with high-moisture extrusion. Whole Foods used to carry a soy-based patties that fell apart on the grill. By 2019, the same product held together because of precise alignment of soy protein isolate under extreme pressure and temperature inside an extruder. The extrudate cools rapidly, creating fibrous structures that mimic muscle tissue. This isn't magic. It's a thermal-mechanical process that was understood in the industrial food world since the 1970s—just never applied to alternative proteins at scale. The innovation cluster that drove this was geographically concentrated. Berkeley, San Francisco, and Boston accounted for roughly sixty percent of early funding and talent. Peter Melchior at New Harvest organized academic exchanges between protein scientists and chefs in 2012. That single initiative accelerated the peer network by an estimated eighteen months. Without that informal coordination, the field would have advanced significantly slower because food scientists were quietly working in silos across university labs and corporate facilities. The counter-intuitive part most coverage misses is that the first wave of successful products didn't come from trying to replicate meat. They came from replacing dairy. Cheese and ice cream are structurally simpler targets because the functional challenge is emulsion stability, not fibrous texture. Impossible Burger succeeded only after they solved the heme problem—which required recombinant yeast fermentation to produce leghemoglobin at food-grade purity. That fermentation step alone took over four years of process optimization before it was commercially viable.
Why Scaling Broke The Model
Around 2021, the economics started collapsing for a lot of these companies. The primary cause wasn't consumer demand—which remained steady at about eight to ten percent annual growth in the US plant-based category—it was input costs and distribution competition. Soy and pea protein prices spiked because demand from these startups collided with existing commodity markets. A single plant-based burger manufacturer consuming five thousand tons of pea protein annually can move regional pricing by three to five percent. Distribution was the second problem. Shelf space in grocery stores operates on a rotation model. When Impossible and Beyond secured end-cap placements, smaller startups couldn't get visibility. The median new plant-based product achieves less than one percent national retail penetration within its first two years. The few that break out have venture capital that supports promotional spend averaging two hundred thousand dollars per SKU annually during launch quarter. Most seed-funded teams simply cannot match that. Here is the blunt assessment: the narrative that this movement will continue accelerating linearly is wrong. The sector is consolidating. Companies without proprietary technology—formulations they can patent or keep as trade secrets—are getting acquired or squeezed out. The remaining survivors are those with either a biological IP advantage or enough capital to operate at a loss for four to six more years. That second path is drying up because venture returns from earlier plant-based exits have shifted investor expectations toward profitability timelines measured in months, not decades.
Get the Full Details
What Actually Works Now
If you are evaluating this space from a business or investment angle, look at three metrics that matter more than revenue growth. First, gross margin after logistics. Many plant-based brands show thirty percent gross margins on paper but twenty-two percent after warehousing and cold-chain distribution, which is thinner than conventional meat processing at equivalent scale. Second, formulation concentration. Can the product be sold frozen and refrigerated, or does it require a fully separate cold supply chain? Frozen product moves better and has a longer shelf life, which reduces spoilage losses that typically run between four and nine percent in the refrigerated category. Third and most overlooked: protein source dependency. Companies built entirely on a single protein isolate—whether pea, fava, or soy—carry concentration risk. Supply disruptions in any single crop year can halt production for months. The companies that are weathering this period are diversifying into mycoprotein and precision-fermented dairy proteins, which offer different functional properties and aren't subject to agricultural price cycles. The sector that will actually matter in five years isn't plant-based meat analogs. It's cell-cultured and precision-fermented ingredients. The reason is straightforward: you can produce whey and casein without a cow using engineered yeast, and the molecules are identical to animal-derived versions. This sidesteps the regulatory uncertainty around cultured meat while delivering the functional benefits that food manufacturers actually need. Gaviurow and Perfect Day are already operating at commercial scale here. The infrastructure built by the plant-based wave—consumer acceptance, retail relationships, formulation expertise—is being redirected toward this next phase.
The Real Bottleneck
Regulatory fragmentation remains the single biggest obstacle to global expansion. The European Union approved precision-fermented whey only in early 2025, years after approvals in Singapore and the United States. China has no pathway for cellular agriculture products at all. This means companies cannot achieve the scale that lowers unit costs because they are legally confined to smaller markets. A product that would need global distribution to reach cost parity with dairy is effectively capped at US and a handful of other approved markets. The workaround that is emerging is geographic segmentation by regulation. Companies are launching precision-fermented ingredients in approved markets first, using those revenue streams to fund R&D for formulations that comply with different regulatory frameworks. This is slower and more expensive than a unified global approach, but it avoids the regulatory rejections that have sunk several well-funded startups. The timeline for meaningful change is measured in regulatory cycles—typically three to five years per major market—not in years. The movement started with a small group of people who saw that the existing food system had unresolved problems and had the technical skills to address them. It accelerated because food chemistry was solvable. It is now decelerating because economics and regulation are harder problems than extrusion. That doesn't mean the direction has changed. It means the next phase requires different skills and a longer patience than the founding wave anticipated.