Why Your Bank App Still Sucks and How Fintech Actually Fixed Parts Of It
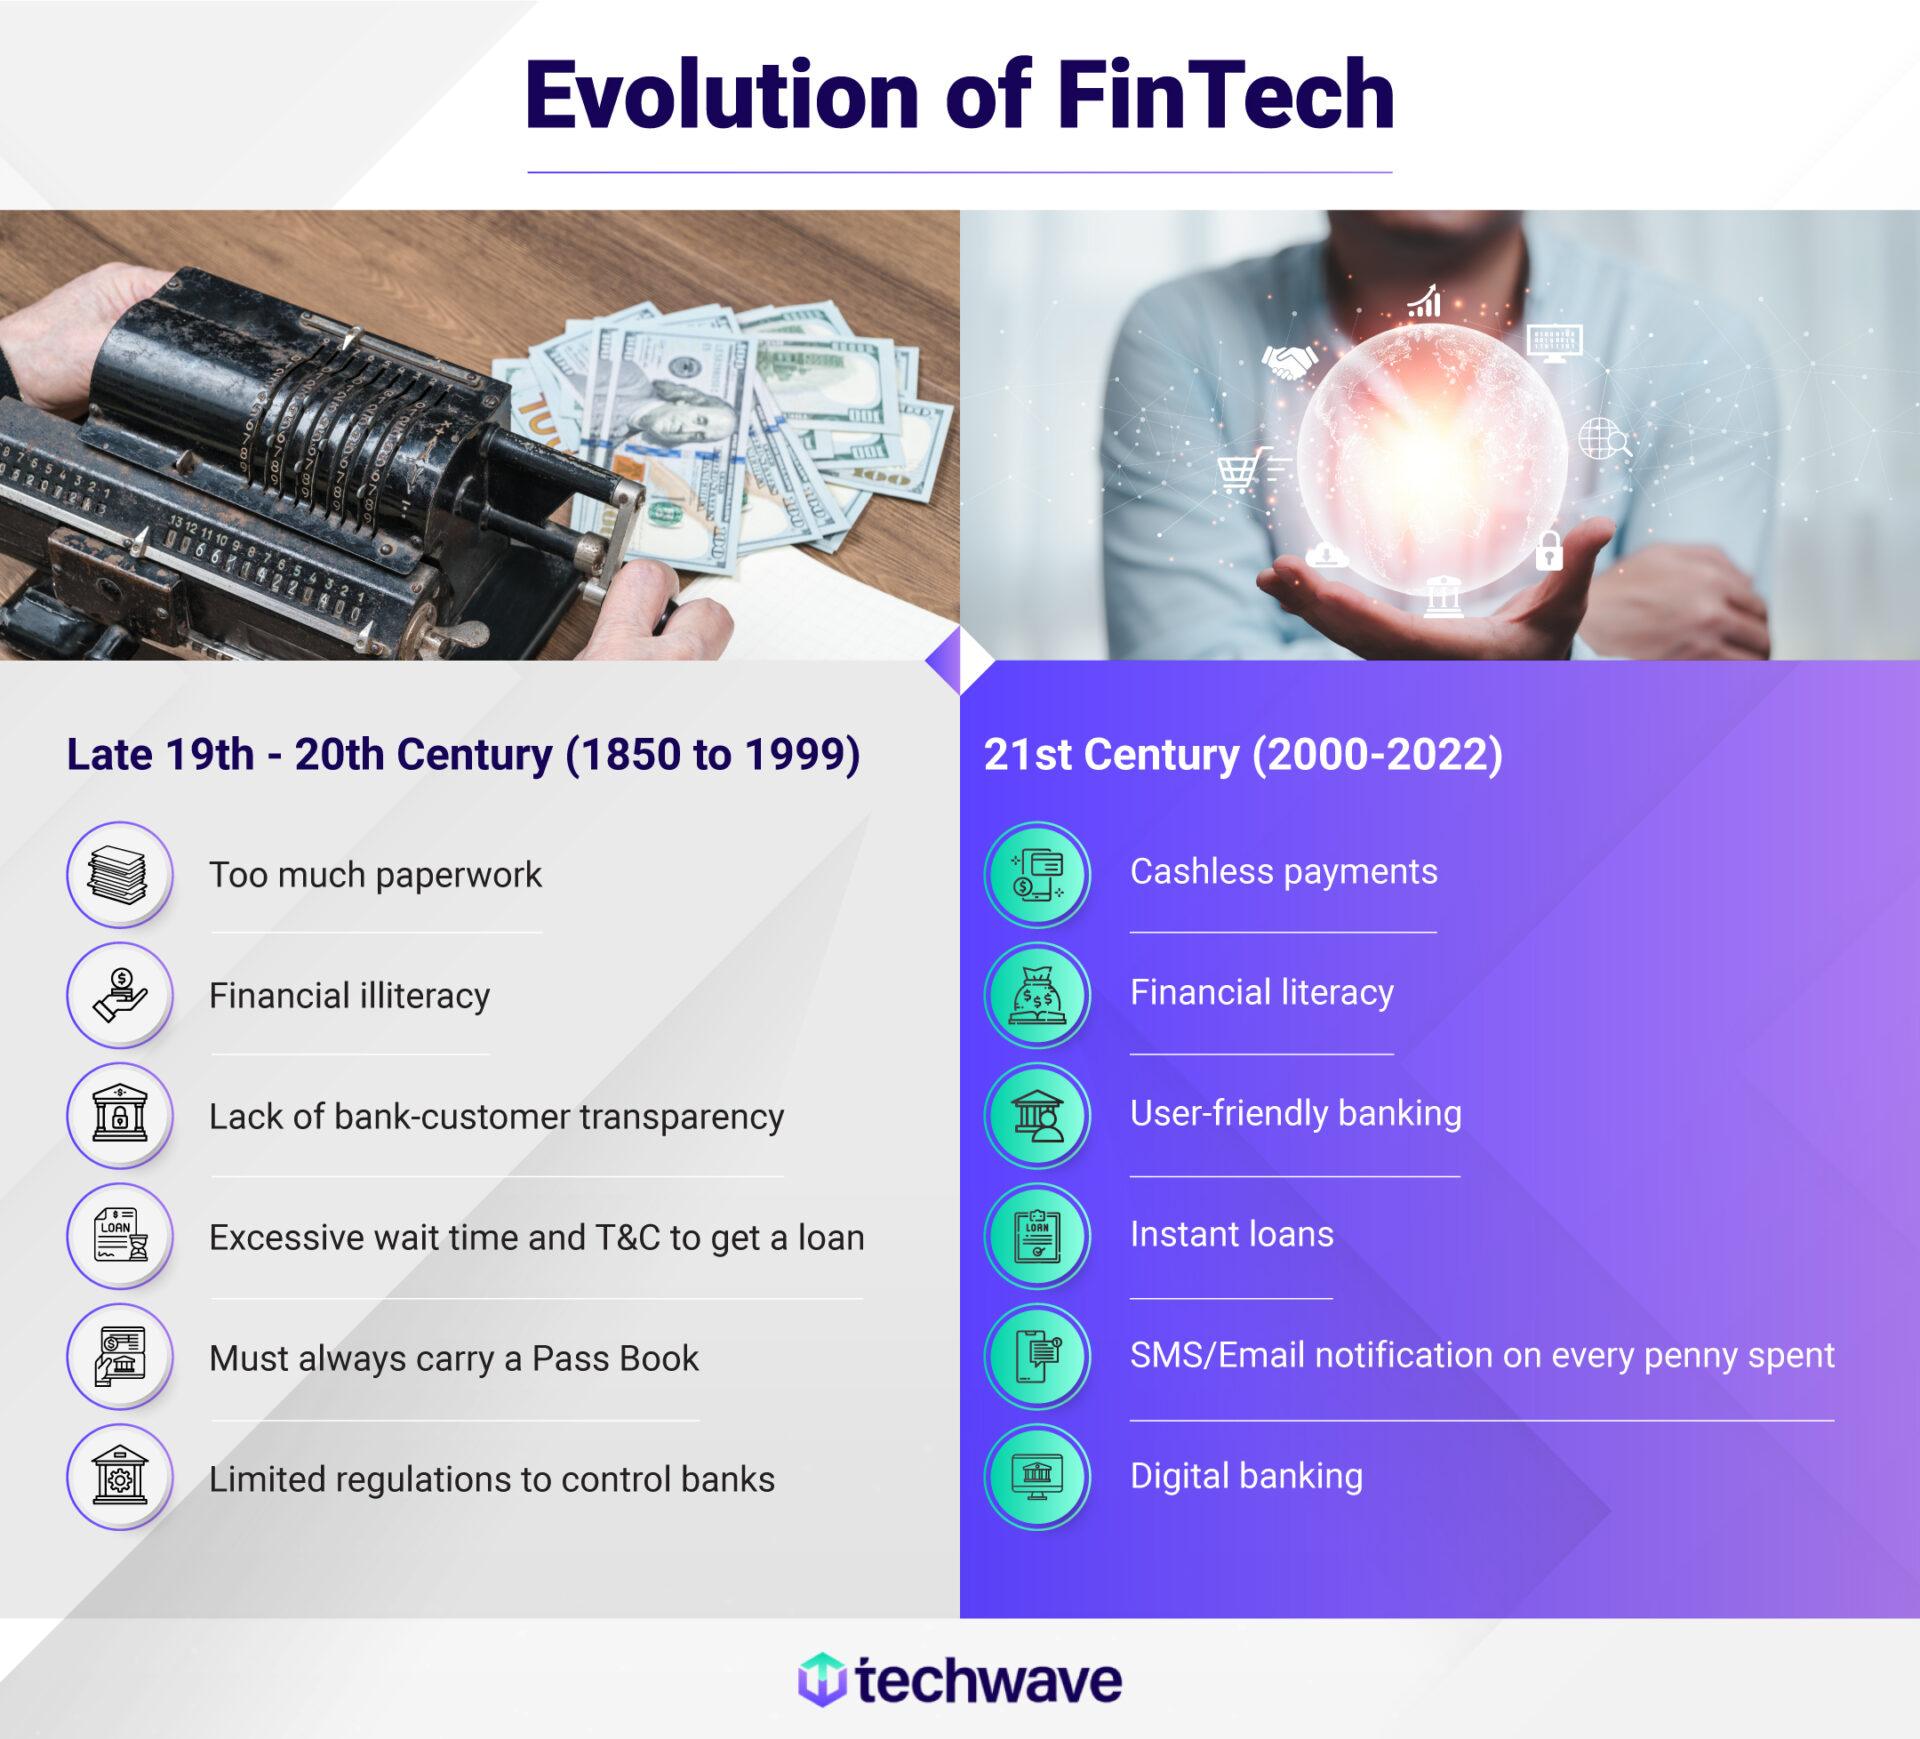
I spent seven years working in payments infrastructure before moving into product. I have watched the industry go from "we process transactions via mainframe at midnight" to "your phone can split a dinner bill across four currencies in three taps." The change didn't happen because of vision. It happened because legacy banks were too slow to respond to regulatory pressure and customer complaints, and a bunch of engineers with better APIs figured out how to slip between the cracks. Fintech isn't a single thing. It is a set of approaches that took established financial functions and rebuilt them on modern stacks. Open banking gave developers access to account data through regulated APIs. Neobanks replaced branches with apps. Payment processors like Stripe and Plaid handled the boring plumbing so startups could focus on the user interface. That separation of infrastructure from experience is what actually changed things. If you want to understand how this works under the hood, start with the data flow. A consumer connects their bank account to a fintech app using a provider like Plaid or TrueLayer. The provider makes a secure OAuth exchange, retrieves an access token, and then polls transaction data in near real-time. The fintech app receives structured JSON and uses it for budgeting, lending decisions, or automated transfers. The consumer's bank never shares passwords. This architecture exists because regulators in the EU, UK, and increasingly in other markets mandated it.
I ran into a specific edge case once while integrating a budgeting tool for a client. The institution they used supported Open Banking on paper but returned transaction metadata in a completely non-standard format. Descriptions came back as raw merchant codes instead of readable names, and dates were stored as Unix timestamps in one field and ISO strings in another within the same response. Most budgeting apps would have just displayed garbage. The workaround was to build a mapping layer that cross-referenced merchant codes against a local database of 40,000 entries and normalized the date fields based on which format appeared most consistently across a rolling 30-day sample. It added about two weeks of dev time but prevented the app from showing users nonsense like "Transaction date: 1748923200." Here is something most guides don't tell you. Open banking data is not the same thing as financial truth. The data comes from the consumer's bank statement, which means it is already an abstraction. Recurring subscriptions that auto-renew might be lumped together. Refunds appear as separate negative transactions. Currency conversions show the rate the bank used, not the market rate. If you are building anything that makes lending or investment decisions on top of this data, you need to account for noise. I learned this the hard way when a client's automated credit scoring model started approving borderline applicants because subscription payments were being misclassified as discretionary spending due to a merchant category mismatch. The counter-intuitive part about fintech adoption is that the real barrier isn't technology anymore. It is regulatory fragmentation. An app that works smoothly in the UK under FCA rules needs a completely different compliance setup for Australia, another for Brazil, and basically a rebuild for the US where there is no federal open banking mandate yet. States like New York and California have their own rules, which means even domestic expansion is messy. Most people don't realize that the reason their favorite fintech app isn't available in their country isn't because the tech doesn't scale. It is because legal costs scale worse than the tech.
On the consumer side, the practical impact is real. I use three fintech-powered tools daily. One handles multi-currency spending with mid-market exchange rates, which normally saves me about 2.5 percent on international purchases compared to my traditional bank. Another automates savings by rounding up purchases to the nearest dollar and sweeping the difference into a linked investment account. A third aggregates all my accounts including old ones from banks I abandoned years ago and flags duplicate subscriptions I hadn't noticed. These aren't magic. They are just applications of APIs that didn't exist at usable scale ten years ago. There are downsides worth stating plainly. Fintech companies are still financial institutions in all the ways that matter when things go wrong. If a neobank loses your money, goes insolvent, or freezes your account over a suspicious activity flag, you are dealing with the same frictions as a traditional bank but with worse customer support. I have personally had an account frozen for eleven days while waiting for identity verification documents that the support team insisted were "insufficient" despite meeting every stated requirement. Traditional banks at least have branch locations. Fintech only has a chatbot and an email queue. Data privacy is another legitimate concern. When you connect your bank account to a fintech app, you are trusting a third party with your full transaction history. Most reputable companies encrypt this data and restrict access, but the risk profile is different. A traditional bank breach affects one institution. A fintech aggregator breach like the ones we saw with Plaid in 2019 and 2022 exposed millions of users across dozens of connected apps simultaneously. The fix was stronger tokenization and shorter token lifespans, but the structural risk remains.
Get the Full Details

For anyone looking to engage with this space practically, here is what I would suggest based on actual usage rather than marketing copy. First, only connect accounts you are comfortable sharing. Use apps with transparent privacy policies and read the sections about data retention and third-party sharing. Second, enable two-factor authentication everywhere, preferably with an authenticator app rather than SMS. Third, don't assume "fintech" means better. Some of the worst user experiences I have encountered come from companies that prioritized design over reliability. Check whether the company is regulated in your jurisdiction before depositing significant funds. A quick search of your national financial regulator's website will tell you if they are licensed or operating in a gray area. The technology behind these systems continues to evolve. AI-driven categorization is getting better at reading messy merchant descriptors. Real-time payment rails like FedNow in the US and UPI in India are replacing slower batch systems. Embedded finance means non-financial companies are building financial products directly into their platforms. None of this eliminates the core issues of trust, regulation, and the inherent risk in moving other people's money. But it does make the day-to-day experience of managing finances noticeably less painful than it was even five years ago. If you want to start experimenting, most of these services are free to sign up for. Download a budgeting app, connect one account, and see how the data flows. Try a multi-currency card for your next trip. Use an aggregation tool to audit your spending for a month. You don't need to switch everything at once. The fintech landscape is mature enough now that you can pick individual tools for specific problems without betting your entire financial life on a single platform.