Understanding How Comenity Built Its Retail Card Empire
Comenity Bank, which operated under the name Comenity Capital Bank for most of its history, has quietly become one of the largest issuers of retail store credit cards in the United States. They don't advertise like Chase or Citibank. You won't see their commercials. But their cards are swiped at checkout counters across the country every single day, often without shoppers realizing which bank is actually funding the account behind the plastic. The Victoria's Secret card is one of many store-branded offerings Comenity manages on behalf of major retailers. When you apply for a Victoria's Secret credit card, the application runs through Comenity's underwriting infrastructure, and the account gets reported to the three major credit bureaus under Comenity's name as the issuing bank. The brand does the marketing. Comenity does the banking. I learned this the hard way a few years ago when I was helping a client rebuild their credit profile after a rough patch. They had opened five different store cards over two years without understanding that almost all of them were issued by Comenity. Each application triggered a hard inquiry on their credit report, and while the inquiries showed up under different retailer names, they all pointed back to the same institution. My client thought they were diversifying their credit mix. They were just stacking Comenity pulls. I had them stop applying immediately and focus on payment history across those existing accounts instead. That alone removed the biggest roadblock in their recovery plan within four months.
What makes Comenity's model interesting from a technical standpoint is how they structure their underwriting thresholds. Unlike traditional banks that often use broad FICO score cutoffs, Comenity tends to evaluate applicants through a combination of score bands, debt-to-income ratios, and proprietary behavioral models. Their approval rates fluctuate significantly depending on the specific retailer partnership. A card branded for a luxury retailer like Victoria's Secret typically carries slightly higher minimum score expectations than a card tied to a discount warehouse store, even though both sit on the same bank's balance sheet. The difference comes down to the risk parameters each brand sets, not the bank itself changing its rules. Another thing people consistently miss: Comenity cards usually carry relatively low credit limits on approval. I've seen a lot of first-time applicants get approved for $200 to $500 limits on retail cards. The temptation is to max them out quickly because the limit feels small. That drives your utilization ratio through the roof and tanks your credit score faster than almost any other single action you can take. Keep utilization under thirty percent, ideally under ten percent, and the low limit actually works in your favor because it's easier to manage responsibly at that range. The annual fees on most Comenity-issued retail cards are nonexistent, which is one reason the model persists. The revenue comes from interchange fees when you swipe, interest charges on carried balances, and fees from the retailers themselves for customer acquisition. You're not the product. You're the revenue driver for a three-way transaction.
Practical Considerations If You're Dealing With a Comenity Card
Navigate the customer service side carefully. Comenity's support structure has been a frequent topic of complaint across consumer forums for years. Call wait times are unpredictable, and resolving disputes can require multiple contacts before something gets escalated properly. I keep a dedicated note for each account with the date, time, representative name, and case number from every call. It sounds excessive until you need to reference a specific conversation from six weeks ago during a billing disagreement, and the representative on the other end has no idea what you're talking about. That documentation gets you somewhere. Reporting is generally accurate but not always timely. There's a well-documented lag between payment posting and credit bureau update on some Comenity accounts. I've seen reports show payments as missing for up to two billing cycles after a payment was made and confirmed on the app. This isn't universal, but it happens often enough that I recommend always confirming payments went through on the account portal and following up with a screenshot saved locally if you ever need proof of payment for a dispute or lease application. If you're applying strategically, space your applications. Comenity performs soft pull pre-approvals on some cards, which doesn't affect your credit. Check for those first before going through a full application. Even if you don't get a pre-approved offer, the application process itself will show a hard inquiry, and Comenity checks your recent inquiry history during underwriting. Too many applications within a short window raises red flags regardless of your actual creditworthiness.
Get the Full Details

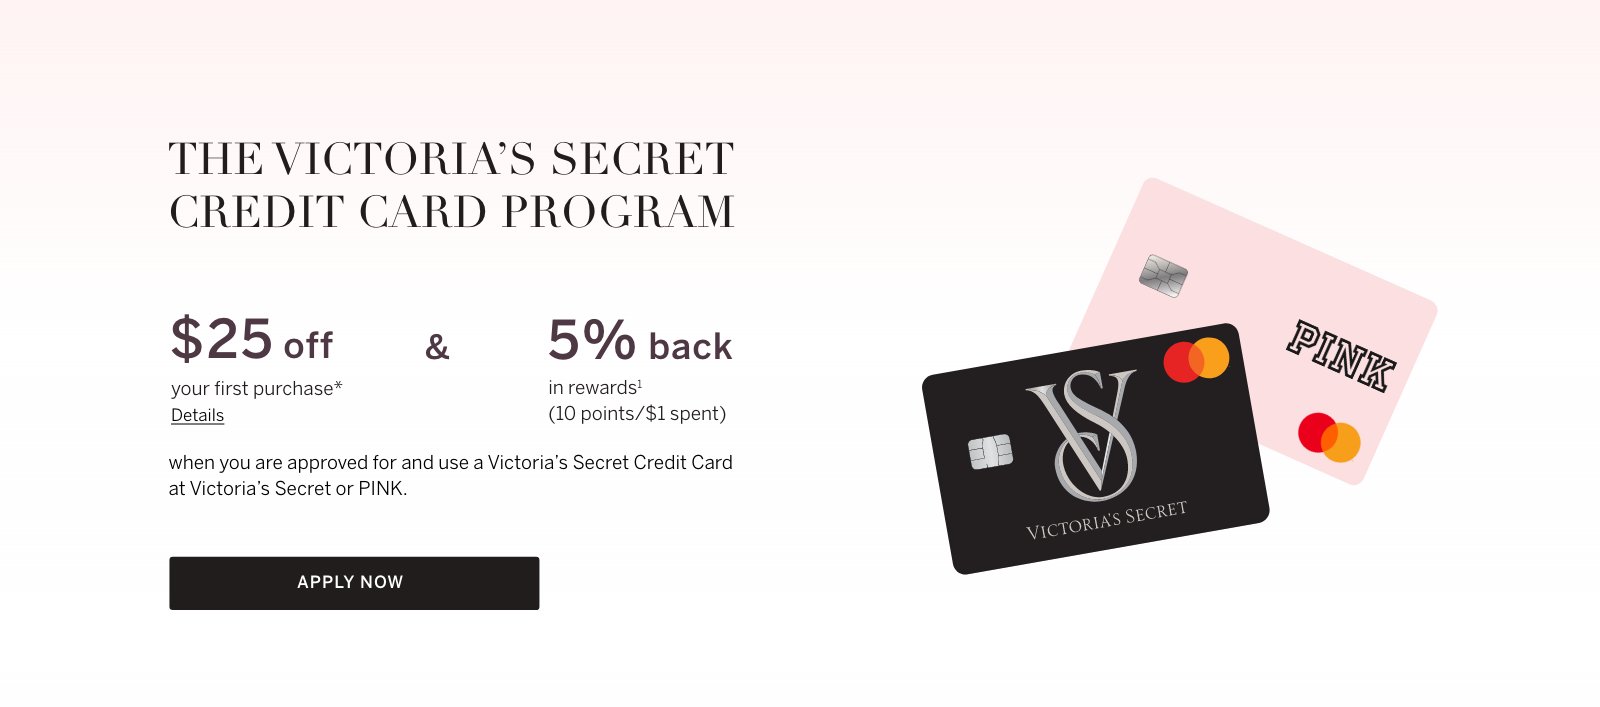
The rewards structure on Comenity retail cards is straightforward but not generous. You typically earn store credit or points redeemable only at the branded merchant. This limitation keeps costs low for the issuer but reduces the card's utility outside a specific shopping ecosystem. If you shop at that store regularly, the card makes sense. If you're chasing general cash-back options, these cards won't compete with broader rewards programs from major network partners. There's also the closure question. Closing a Comenity retail card after years of positive payment history can temporarily dip your credit score by lowering your average account age and reducing your total available credit. But carrying an unused card with a low limit contributes minimally to your utilization calculation while occupying space in your credit report. The math depends on your overall profile. I generally recommend keeping older retail accounts open unless the card is generating annual fees or Tempting you into spending you wouldn't otherwise do. Comenity continues to expand its retail partnerships, acquiring portfolios from other issuers and launching new branded cards regularly. The infrastructure that supports a Victoria's Secret card is essentially the same backbone that powers dozens of other retail relationships they manage simultaneously. That operational efficiency is part of why they've grown this large without mainstream visibility. They operate behind the scenes, processing applications, managing accounts, and reporting payment data while the brand names on the cards do the consumer-facing work.