How Postal Money Orders Actually Worked
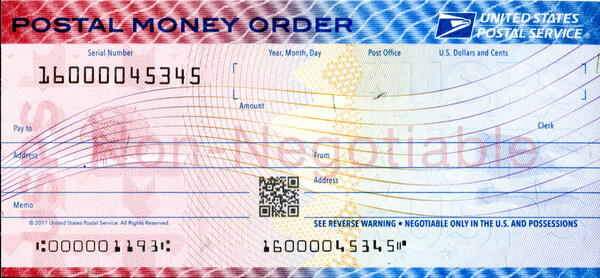
When I first started dealing with commercial payments back in the late 90s, money orders were everywhere. Every contractor, every small supplier, every family business in my network accepted them. The process was straightforward: you walked into a post office or a participating retailer, filled out a form with your name and the payee's information, handed over cash plus a fee, and got a printed instrument with a serial number and your receipt. The post office guaranteed it. That guarantee was the whole point. The fees varied but typically ran between sixty cents and two dollars depending on the amount and where you purchased it. Maximum denominations changed over the years, but for a long time you could get a single money order up to five hundred dollars. Need to send more? You bought multiple ones. I've seen people fill entire pages with them just to move a thousand dollars through the system.
The Rise And Fall Of Postal Money Orders A Look Into The Decline Of A Timeless Payment Method
The peak was somewhere around the early 2000s. USPS issued roughly eight hundred million money orders annually at that point. That number has dropped to somewhere under two hundred million in recent years. The decline didn't happen overnight, but it accelerated noticeably after 2013 when the USPS capped money orders at five hundred dollars and stopped selling them at many retail locations like grocery stores and pharmacies. That single decision fragmented the market. Western Union picked up the slack, then every bank started offering their own branded versions, and suddenly the postal money order wasn't the default anymore. The real killing blow came from digital payments. Zelle went mainstream around 2021. Venmo and Cash App had been around longer but didn't really penetrate the older demographics that had been the core money order user base until recently. Once your grandmother realized she could send money through her bank's app instead of driving to the post office, the trajectory was set. Here's something most people don't understand about money orders though. They aren't actually issued by the post office. The USPS purchases them in bulk from the Western Union Company under contract. What you're really holding is a Western Union instrument with a USPS guarantee on top of it. That arrangement existed for decades and it's why you can still cash a twenty-year-old postal money order at many banks even though the USPS itself barely promotes them anymore.
The Practical Problems Nobody Talks About
I spent about three years dealing with stale and rejected money orders as part of a collections job. The biggest headache was the one-year validity period. Money orders expire after twelve months at most financial institutions. Not all of them, but the vast majority. A vendor could receive a money order in March 2019, file it in April, get it rejected in May because it had expired, and then spend the next six months chasing someone who had already moved on. The original purchaser wasn't necessarily at fault. They'd paid for it, signed their name on it, and handed it over. But getting a replacement required tracking down that person, verifying the purchase receipt, and waiting another three to five business days for the new instrument to clear. The workaround I used was to build a simple spreadsheet that tracked issue date, payee, amount, and the one-year expiry for every incoming money order. When something approached the expiration window, I'd flag it and contact the payer before it actually lapsed. It cut our stale order resolution time from an average of four weeks down to about ten days. That spreadsheet became standard operating procedure for the entire department within six months.
Get the Full Details

Where Money Orders Still Matter
If you've written off money orders entirely, you're probably missing some legitimate use cases. Landlords still heavily favor them because they leave a paper trail that's easier to verify than a personal check. Government agencies accept them for fine payments and filing fees at the local level. Immigration filings, specifically USCIS forms, still require payment by money order. You cannot submit a personal check from a foreign bank account. A postal or cashier's money order is basically the only option. There's also the unbanked population. I know this from dealing with clients directly. A significant portion of the small business owners I work with don't have traditional banking relationships. They operate cash-heavy. Money orders are how they pay suppliers, how they move money between accounts, how they handle transactions they can't do in person. That demographic isn't shrinking fast enough to make money orders irrelevant.
The Fraud Angle
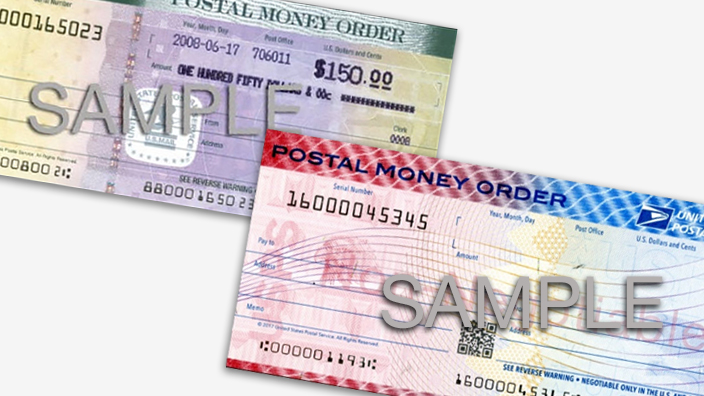
Money orders are fraud vectors and the people selling them know it. The classic scheme involves a scammer buying a large money order with stolen credit card information, then selling it to an innocent third party for less than face value. The third party deposits it, gets screwed when the underlying payment falls apart, and the fraudster disappears. The USPS and Western Union both have mechanisms to track and cancel fraudulent money orders, but recovering funds after they've been cashed is nearly impossible. If you're accepting a money order from someone you don't know personally, verify it at the issuing location before handing over any goods or services. It takes twenty minutes and saves you from a world of trouble. Counterfeits exist too. They're not sophisticated, but they're common enough that every business that accepts them regularly has had to deal with at least one. The telltale signs are usually the watermark and the microprinting. Hold it up to the light. Look for the faint USPS logo in the background. Check the serial number format. Postal money orders follow a specific numbering convention that starts with a two-digit series identifier followed by a nine-digit unique number. If the formatting looks off, don't deposit it.
The Bottom Line
Postal money orders aren't dead. They're just not the default payment method they were twenty years ago. The infrastructure still exists. The tracking systems still work. If you need to send money securely without a bank account, or if you're collecting payment from someone who doesn't trust checks, a money order is still a solid option. Just understand the limitations. The expiry dates. The fraud risk. The fact that you might need to visit a physical location to purchase one. For the right situation, it still does exactly what it was designed to do.