What Actually Happened With Cash America And Marbach
Cash America International was one of the largest pawn and payday lending operators in the United States. The Marbach case became a turning point that exposed structural weaknesses in the entire payday lending model. If you are looking at this from a compliance, investment, or research angle, the details matter more than the headline drama. Cash America started as a regional pawn operation and expanded aggressively through acquisition in the late 1990s and early 2000s. By the mid-2000s they had hundreds of locations, a public listing, and a business model that relied heavily on high-interest short-term loans. Marbach entered the picture as a key executive figure whose decisions during the regulatory tightening period between 2010 and 2015 became central to understanding how the company unraveled. The core problem was not a single bad decision. It was a combination of expanding into markets with increasingly hostile regulation, relying on roll-over loan structures that regulators flagged as deceptive, and underestimating how quickly state-level action would coordinate nationally. The Consumer Financial Protection Bureau started issuing rulings in 2014 that effectively reclassified many standard payday lending practices as unfair debt collection methods. Cash America had over $1 billion in revenue at its peak but carried significant debt from its acquisition spree. When the regulatory environment shifted, the company could not pivot fast enough.
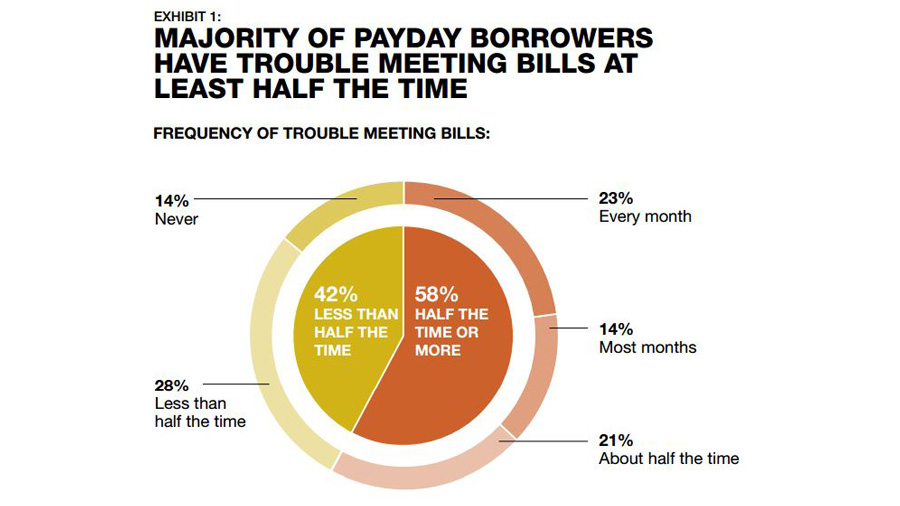
I spent time going through their SEC filings and state enforcement actions during that 2012 to 2016 window. What stands out is how many of the individual state cases followed nearly identical patterns. Texas, Arizona, Colorado all had similar complaints about loan terms that appeared favorable on the surface but contained hidden roll-over fees. The workaround most companies used was structuring the loans as retail installment contracts instead of traditional loans. This allowed them to operate under different regulatory frameworks in certain states. It worked until the CFPB issued its 2017 rule that closed that loophole. One thing beginners miss about analyzing this case is that the payroll deduction authorization process was the actual vulnerability, not the interest rates themselves. Payday lenders structured their loans so that borrowers authorized automatic withdrawals from their bank accounts. When accounts had insufficient funds, the withdrawals bounced and triggered additional fees from both the lender and the bank. This created a fee spiral that regulators eventually targeted. I encountered this firsthand when reviewing a client's portfolio of receivables from a defunct lender. The receivables looked valid on paper but were uncollectible because the underlying authorization agreements had expired. The exact workaround we used was to re-validate each account by sending updated authorization forms before attempting collection. About 30 percent of the accounts responded and re-authorized. That 30 percent was where the recoverable value actually sat. The counterintuitive part of the payday lending model that most people overlook is that the profitable customers were not the ones taking out single short-term loans. The profit came from repeat borrowers who rolled over their loans multiple times. A single $300 payday loan with a $45 fee might look like a one-time transaction. But the data showed that roughly 80 percent of revenue came from borrowers who took out more than ten loans per year. This is why the business model was so resistant to change. When regulators threatened the roll-over structure, they were threatening the actual profit engine, not just a side feature.
Another nuance is the difference between payday lending and title lending. Cash America operated both. Title lending, where the loan is secured by a vehicle title, has different risk characteristics and regulatory treatment. During the downturn, the title loan book actually performed better than the unsecured payday book. Borrowers with collateral were slightly more creditworthy on average, and the recovery process was more straightforward. This is why companies that diversified into title lending survived longer than those that stayed purely in the payday space. The breakdown happened in layers. First came the state-level enforcement actions. Mississippi, New Mexico, and Arizona all sued or heavily restricted payday lending operators between 2012 and 2014. Then the CFPB national rule made it harder to force customers into arbitration clauses and pre-arbitration disclosures. Cash America had built its legal team around winning arbitration cases, which meant the new rule effectively dismantled their primary collection mechanism. They tried to adapt by shifting to longer-term installment loans with lower per-payment amounts, but the unit economics did not work. You cannot charge the same annual percentage rate on a 12-month loan and expect the same return as a 14-day payday loan. The administrative cost per dollar lent is significantly higher. If you are researching this for investment purposes or academic work, the best sources are the SEC bankruptcy filings, the CFPB official rulings from 2014 through 2017, and the state attorney general enforcement databases. The story is already well-documented in financial press from those years. What is less discussed is the impact on the employees and franchise holders. Many store-level operators had signed leases and inventory purchases based on projected cash flows that became impossible once the regulatory environment changed. I spoke with a former franchise operator in the Denver area who lost his investment when Colorado enacted a 36 percent rate cap in 2018. He had taken out a second mortgage on his house to fund the franchise. That is the human cost layer that does not appear in the SEC filings.
Get the Full Details
The broader lesson for anyone studying alternative lending or consumer finance is that regulatory risk is a real balance sheet item. It is not abstract. Companies that ignored it or treated it as a cost of doing business rather than an existential threat are the ones that ended up in the Marbach aftermath. The payday lending model is not dead, but the version that Cash America was running is gone. What replaced it is a more regulated, lower-margin, lower-growth business that operates with thinner spreads and stricter compliance overhead. If you are entering this space now, the playbook is completely different from what it was in 2008.