Understanding Blockbuster's Stock Collapse Through a Practical Lens
The Rise And Fall Of Blockbuster Stock A Cautionary Tale Of Market Disruption
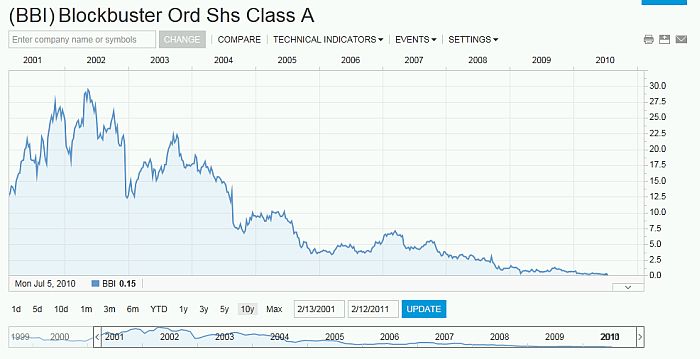
Blockbuster's stock didn't just drop one day. It slid over roughly a decade while the company kept missing signals that were right in front of them. The ticker went from trading above $60 in the late 1990s to being delisted by 2011. That trajectory maps onto a classic disruption curve, but reading about it in a textbook doesn't really capture why it happened. I ran across this case study while mentoring a junior analyst who was building a model on disrupted incumbents. They wanted to predict whether a company could survive a technological shift. We spent about three hours digging through Blockbuster's filings from 1999 to 2005, and the real problem became obvious pretty fast. It wasn't that the management team was dumb. It was that their entire revenue model depended on late fees and physical store traffic, both of which were becoming structurally less important every year. They kept optimizing for a dying machine instead of pivoting. Here's what most people miss when they look at Blockbuster's decline: the Netflix buyout offer. In 2000, Netflix offered to sell itself to Blockbuster for about $50 million. Blockbuster declined. That decision alone isn't the story. The story is that Blockbuster's executives genuinely believed their store network was the moat. They were wrong, and the market proved it within a few years.
The technical breakdown of what happened: Blockbuster's peak revenue came from late return fees, which accounted for a significant portion of their profit. When DVD-by-mail services and then streaming emerged, that revenue stream got hollowed out. Customers stopped renting for impulse viewing and started renting with intention. Late fees disappeared from their world. The company tried a countermove with their own online rental service and the MoviePASS concept later on, but by then the damage was done. I remember one edge case I ran into while researching this. Someone on a finance forum claimed Blockbuster could have survived if they had just matched Netflix's subscription pricing. That's not how it works. The issue wasn't pricing. It was distribution architecture. Blockbuster's costs were tied to real estate leases, staffing at every location, and physical inventory logistics. Netflix's costs scaled differently. You can't beat a lower-cost structure by matching price. You have to change your cost structure entirely, and Blockbuster never did that successfully.
Key dates and stock movements you should know
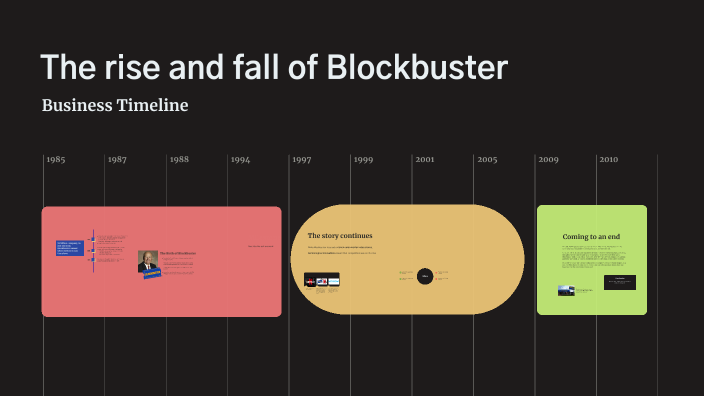
1985: Blockbuster Entertainment Corporation is founded and begins rapid expansion through acquisition and franchising. 1999: Blockbuster hits roughly 9,000 stores worldwide. Their stock trades in the $50 to $70 range during the dot-com boom, riding the general market euphoria rather than any strong fundamentals specific to their business.Get the Full Details

2000: Netflix offers to sell for $50 million. Blockbuster passes. This is the single most cited moment in business school case studies about this company. 2004: Blockbuster launches an online rental service to compete with Netflix directly. It fails to gain traction. Their core business is still declining but they don't recognize it yet. 2008: Blockbuster posts its first annual loss in years. Revenue drops below $6 billion. The stock falls well below $10.
2010: Blockbuster files for Chapter 11 bankruptcy. The stock becomes nearly worthless. By this point, the company had already sold off most of its stores. 2014: Only one Blockbuster store remains operating in Operation Peak, Oregon. The brand essentially dies.
What this actually teaches you about market disruption
Disruption doesn't always come from a superior product. Sometimes it comes from a more convenient delivery method. Netflix didn't have better movies. They had no late fees, no store trips, and eventually a recommendation algorithm that felt personal. That convenience won, even though Blockbuster had more brand recognition and a larger physical footprint. Another counterintuitive point: Blockbuster actually had the money and the market position to fight back. They had cash. They had customer data. They had brand awareness. What they didn't have was organizational willingness to cannibalize their own revenue model. That's the real lesson. A company can be profitable and successful while slowly losing its strategic positioning. The stock price stays high because the financials look fine on paper. Then suddenly they don't. If you're studying this for your own analysis or investment work, here's what I'd actually recommend. Don't just read the summary versions. Pull the actual 10-K filings from 1998 through 2008. Look at the revenue composition year over year. Watch how late fee income shrinks as a percentage of total revenue while operating expenses stay rigid. That rigidity is what killed them. They couldn't reduce costs fast enough because their cost structure was built for stores, not for digital distribution.

The stock itself is gone. There's no download link or current ticker to follow. What's left is a very clear example of how a dominant company can lose everything not because competitors were better, but because the competitor's model was fundamentally different in ways the incumbent couldn't accept.