The Mechanics Of A Widening Wealth Divide
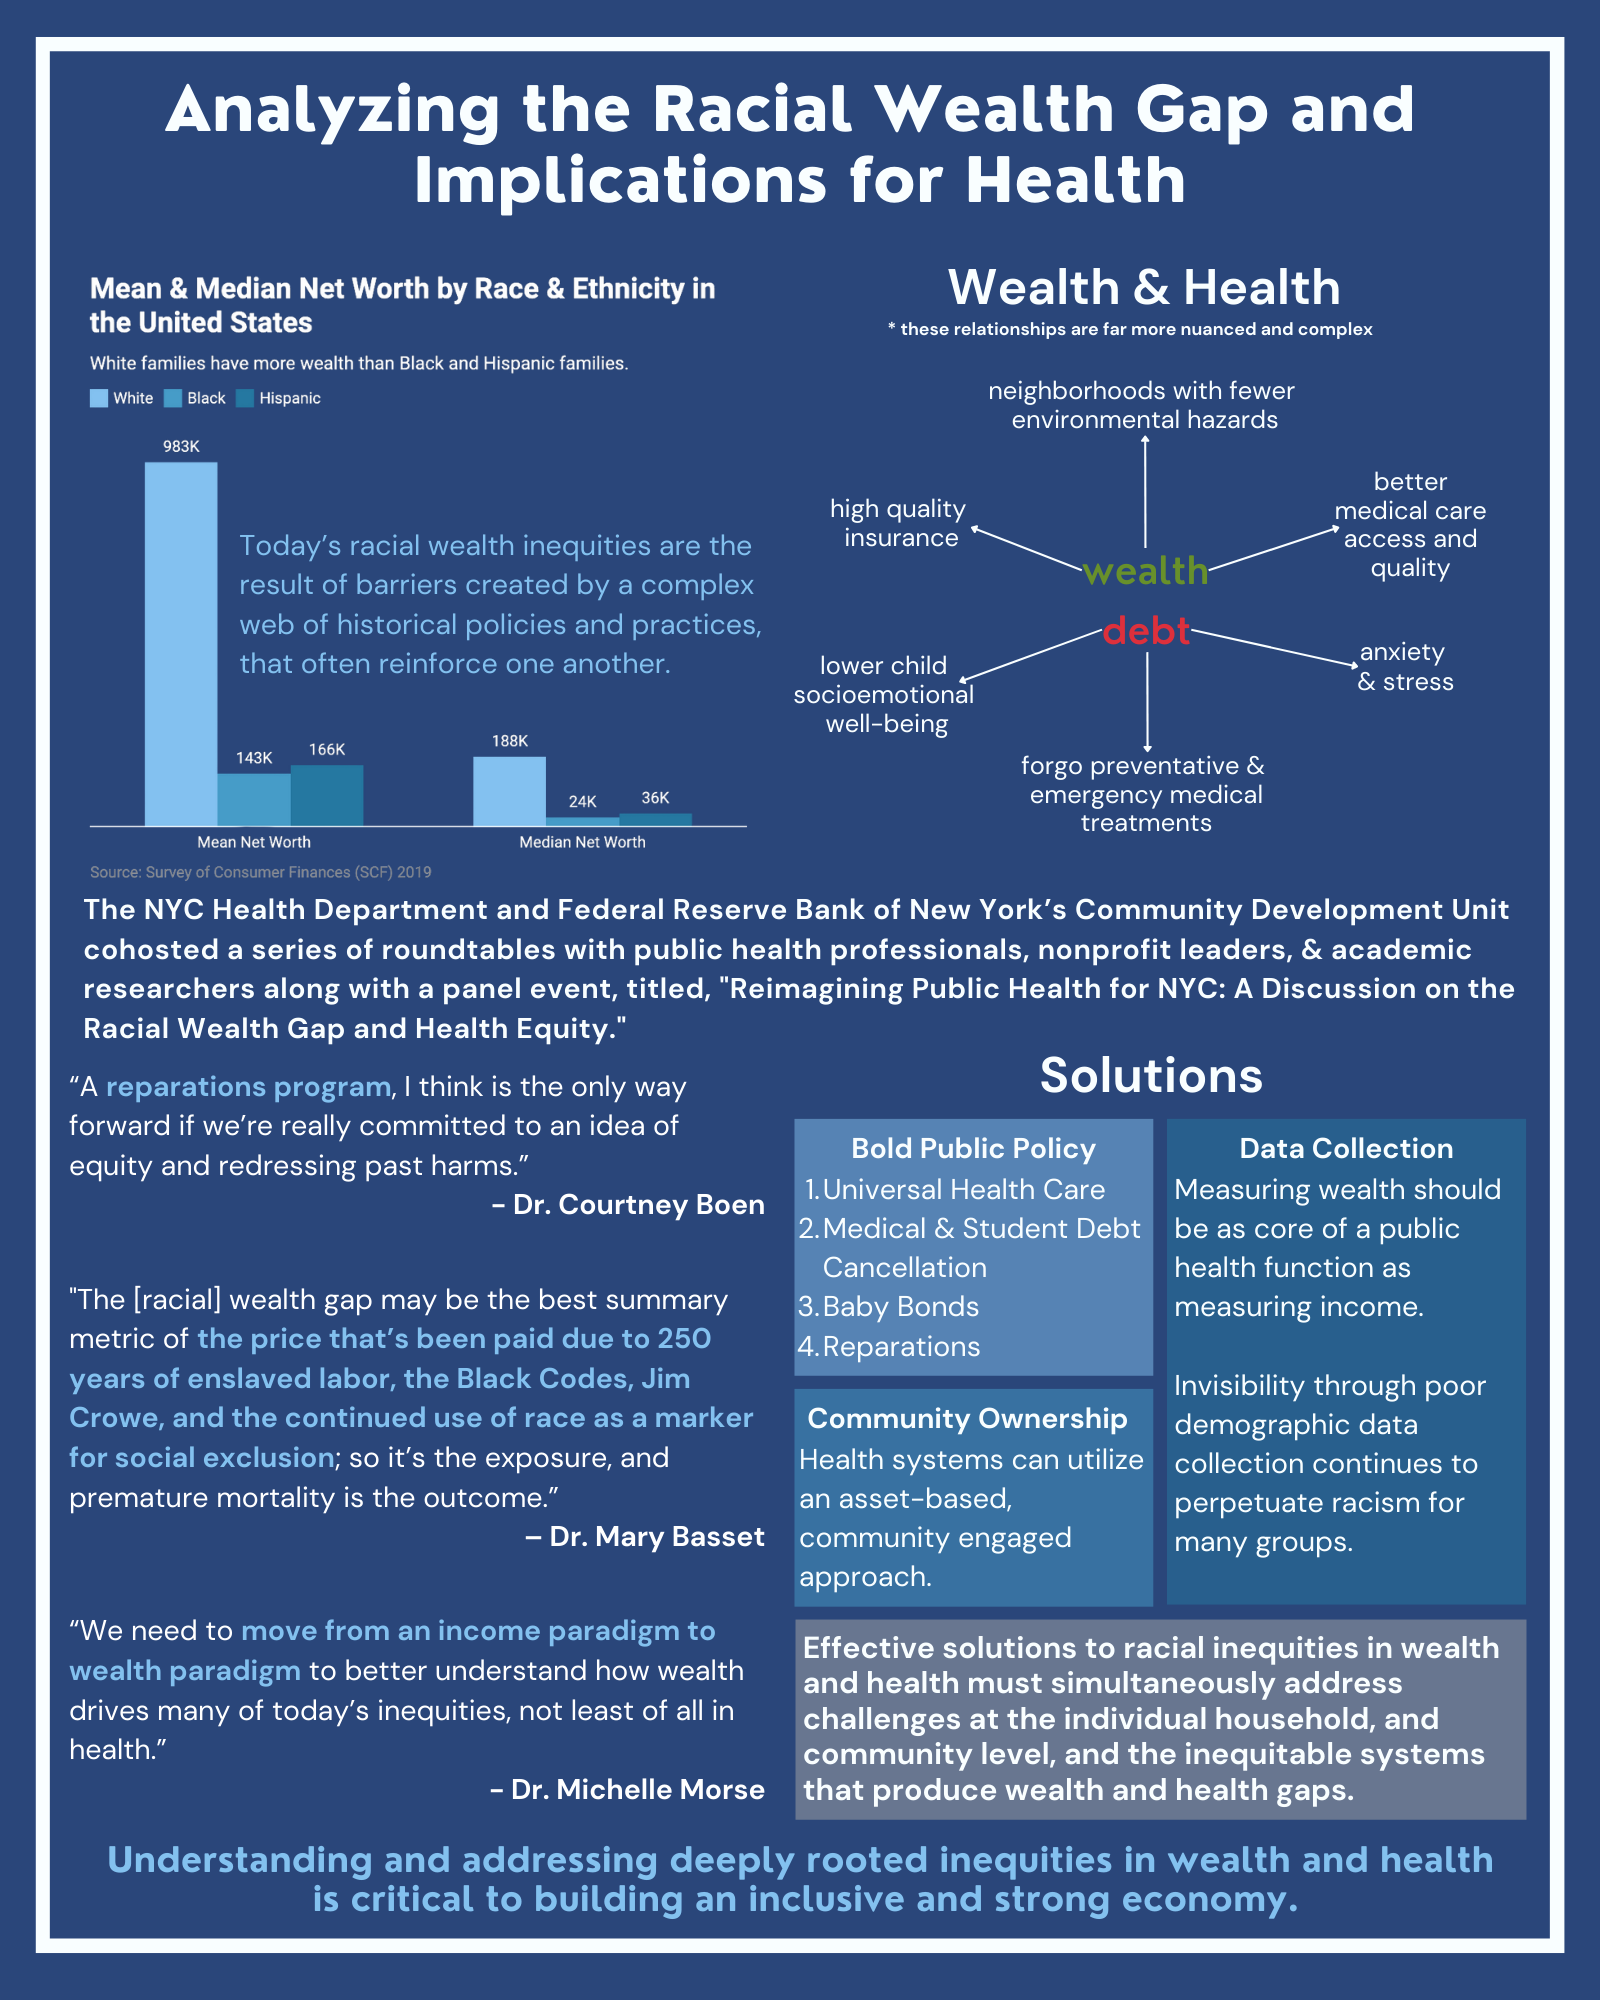
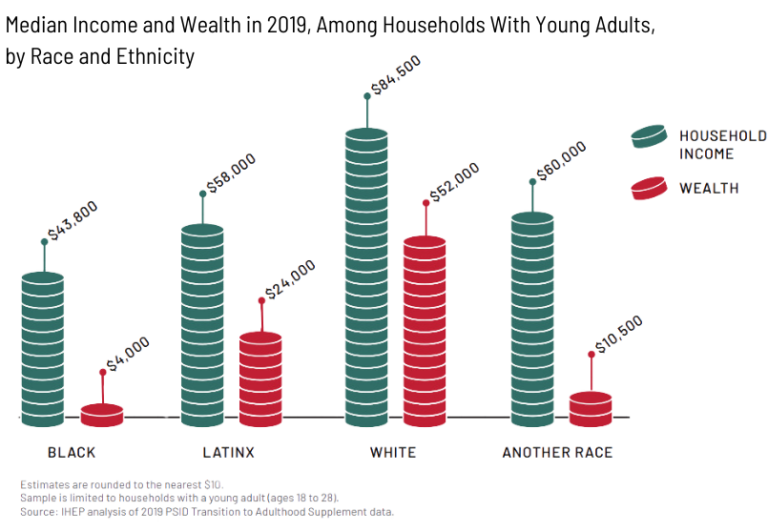
The racial wealth gap in America isn't just a statistic anymore. It's a structural problem that gets wider every year, and the data from the Federal Reserve and Census Bureau makes that clear. In 2019, the median white household held about $188,200 in wealth while the median Black household held roughly $24,100 and the median Hispanic household held around $36,100. By 2022 those gaps had essentially held steady or widened slightly depending on which survey you trust, because housing market forces and stock market gains disproportionately benefit households that already own assets. To actually understand how this works in practice, you need to stop looking at income alone. Income is flow. Wealth is stock. The difference matters enormously because it determines whether a job loss, a medical emergency, or a car repair throws you into crisis or just an inconvenience. I spent years working in community development finance, and one thing I learned quickly is that people who focus only on income data are missing the entire picture. A Black family earning $75,000 a year can be poorer in net worth than a white family earning $50,000 a year, because the first family likely has no home equity, no retirement accounts, and possibly student loan debt, while the second family might have a paid-off mortgage and a 401k they've been contributing to for fifteen years. The historical mechanisms are well documented. Redlining prevented Black families from accessing mortgage financing in most American cities from the 1930s through the 1960s. GI Bill benefits were administered locally, and Black veterans were systematically excluded from many of the homeownership and education programs that built white middle-class wealth after World War Two. These aren't ancient history. The homes that redlined families couldn't buy in 1950 are the same homes whose descendants appreciate into millions of dollars today. Wealth compounds, and when a whole group is locked out of the starting gate, the compound effect works against them for generations.
Another mechanism that doesn't get enough attention is inheritance patterns. Because of the historical exclusions I mentioned, fewer Black and Hispanic families have intergenerational wealth transfers to pass down. When a white family receives a $100,000 gift from parents toward a down payment, that's not just $100,000. That's a lever that generates decades of appreciation and equity building. Without that lever, you're climbing a steeper hill with no assistance. I ran into a specific problem a few years back while working with a nonprofit that was trying to map homeownership assistance eligibility across three counties. The standard census tracts didn't capture the full picture because many Black families who were historically redlined had since moved into newly integrated suburbs, but those suburbs didn't have the same historic lending data available at the tract level. The workaround was to layer Federal Housing Administration underwrite data from the 1930s through 1950s, cross-reference it with current property assessment records, and use a geographic information system to match old exclusion zones to present-day outcomes. It took about six weeks of manual data cleaning that a standard software package couldn't handle, but it revealed something the raw census data missed: the current Black homeownership rate in those suburban areas was still 12 to 18 percentage points below the white rate even after controlling for income, which pointed directly to the residual effect of historical exclusion rather than current discrimination alone. Here's a counter-intuitive point that people often miss. Raising income alone doesn't close the wealth gap at a meaningful rate. Studies from the Institute for Policy Studies and the Brookings Institution have shown that even if Black and Hispanic median incomes were brought to parity with white median incomes overnight, the wealth gap would persist at a substantial level because the foundation of asset ownership is so different. The median white family has roughly seven to eight times the wealth of the median Black family, and income equalization would close maybe a third of that gap at best, assuming all other conditions stayed the same. Wealth requires assets, not just paychecks.
Another nuance that gets overlooked is the role of debt structure. Black and Hispanic households carry a higher proportion of their debt in the form of student loans and high-interest consumer debt, while white households carry more mortgage debt, which is cheaper and builds equity. So two families with the same total debt burden have very different financial positions depending on what kind of debt it is. Mortgage debt is generally a good debt because it's secured against an appreciating asset. Credit card debt or private student loans are bad debt because they don't create an offsetting asset. The data sources you should be looking at are the Survey of Consumer Finances conducted by the Federal Reserve, which is the most comprehensive household wealth dataset in the country and runs every three years. The Census Bureau's Current Population Survey Annual Social and Economic Supplement also provides useful annual data. For historical context, the Economic Inequality Project at Duke and the Working Paper series from the Brookings Institution have solid analyses on the longitudinal trends. Be careful with any source that presents a single year's snapshot without acknowledging the compounding effects over decades, because that's a common way the gap gets minimized in polished reports. One downside to keep in mind with most wealth gap analysis is that self-reported data tends to undercount the actual gap. Households with lower wealth are less likely to respond to surveys, and those who do respond may underreport their debt or overreport modest assets. The Federal Reserve's data goes to great lengths to correct for non-response bias, but the adjustment assumptions can shift the numbers in either direction depending on the model used. I've seen the gap range anywhere from 5-to-1 to 10-to-1 depending on which adjustment methodology an analyst applies, so when you see a headline number, check what data source and what year it's pulling from before you treat it as definitive.
Get the Full Details

If you're looking to work with this data yourself, start with the Federal Reserve's public use files. They provide tract-level aggregated data that you can merge with demographic variables. The learning curve is steeper than just pulling a chart from Pew Research, but the granularity is worth it if you want to understand the mechanisms rather than just the headline numbers. The data won't tell you why the gap exists, but it will tell you where it's widest, how fast it's moving, and which policy levers might actually affect the trajectory.