How Milwaukee Property Taxes Actually Hit Your Wallet
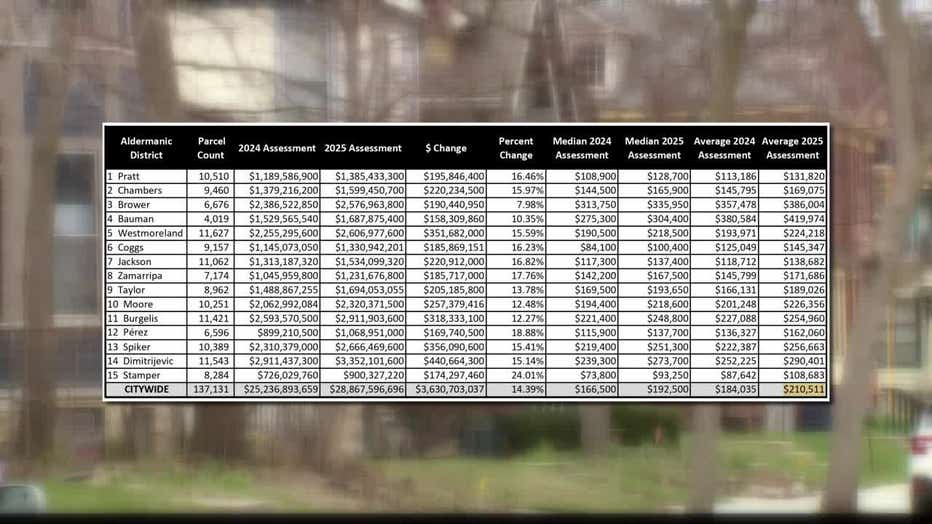
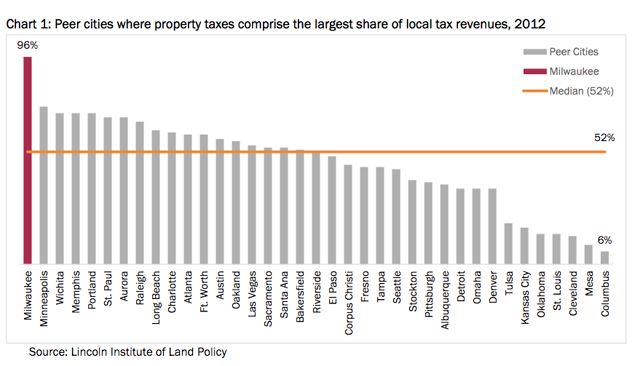
Property tax bills in Milwaukee don't follow the same rules as the suburbs around them. The City of Milwaukee sits in a spot where residential rates are higher than Wauwatosa or Brookfield, but the city also funds services those towns don't have to cover alone. Fire, police, streets, water mains - most of that falls on the city general fund, which means the tax rate carries more weight. You'll see that when you pull your bill and compare line items. The numbers themselves are straightforward enough. Milwaukee's effective property tax rate sits around 1.8 to 2.2 percent of assessed value depending on the year and which neighborhood. That's above the Wisconsin statewide median, which hovers near 1.4 percent. But effective rate doesn't tell the whole story. The assessed-to-market ratio in Milwaukee has fluctuated between 90 and 110 percent in recent years, and that gap is where the real confusion lives. Two houses on the same block can end up with different tax bills because one was reassessed after a sale and the other hasn't been looked at since 2019.
The Property Tax Milwaukee Paradox How The Citys Bills Compare And What Residents Can Do About Them
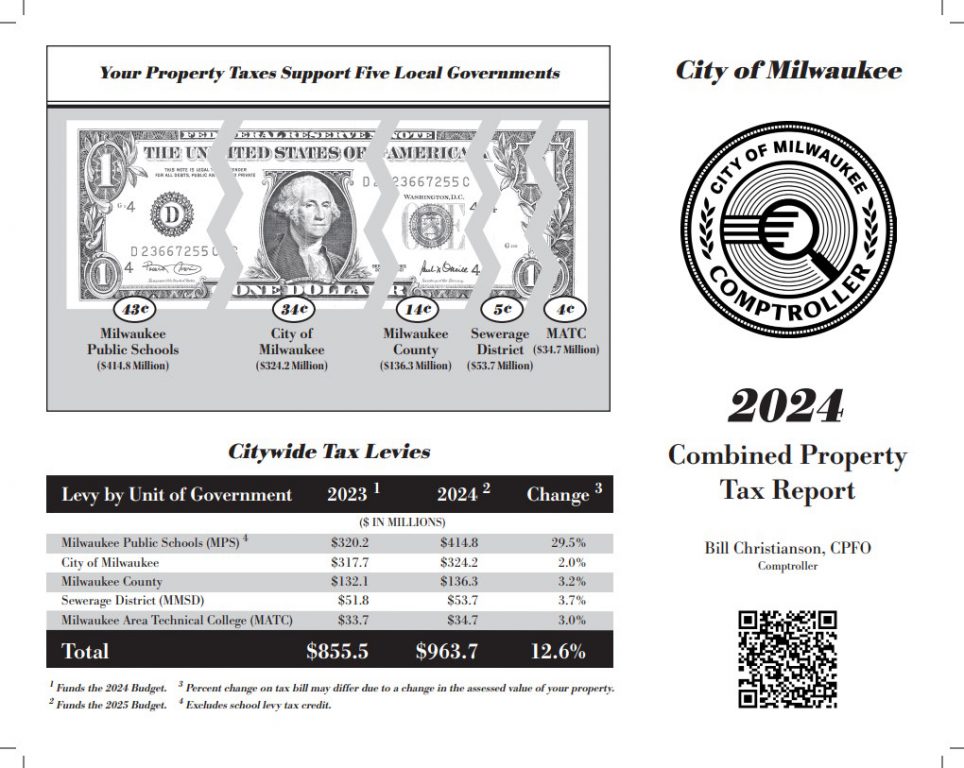
Here's what I found when I started digging into this for a client last fall. She owned a duplex near Brown Deer Road that she'd inherited from her father. The assessed value jumped 38 percent between 2022 and 2023. Her tax bill went with it. She thought the city had revalued the entire neighborhood. They hadn't. The jump came from a single sale - the upstairs unit sold to a new owner who renovated, and that triggered a reassessment under Wisconsin's transfer-based assessment rules. The downstairs unit, still occupied by a long-term tenant, stayed locked at its prior value. Same building. Same roof. Different tax base. This is the paradox. Milwaukee uses a uniform system on paper, but the execution creates pockets where adjacent properties diverge sharply. It's not malice. It's just how Wisconsin's formula works. Sales trigger recalculation. Non-sales don't. Over five years, those pockets become glaring. I walked through that duplex case line by line with the county assessor's office and pulled the assessment history myself. What I discovered was that the city's budget documents didn't even flag the discrepancy. The assessor reported the new value, the treasurer billed it, and nobody connected the dots until the owner showed up with a calculator and a grievance. If you're looking at bills across Milwaukee neighborhoods, you'll see something else. The city tax rate accounts for roughly 40 to 55 percent of a residential bill. The rest comes from the county, school district, and special districts. Milwaukee County holds its own rate, and it's been creeping up. School districts in the city share the Milwaukee Public Schools levy, which runs separate from the city but appears on the same statement. Special districts - sewer, water, streetlights - can add another 5 to 12 percent depending on whether your property is inside or outside the urban service boundary. That boundary isn't a hard line anymore. The city has expanded service zones in past decades, and some neighborhoods carry legacy charges that predate current infrastructure.
The comparison angle matters because residents often blame the city when the county or schools are driving the increase. I've sat in meeting rooms where people came in angry about their bill and the angry portion traced back to a county jail bond referendum that passed three years prior. The city tax rate had actually held steady or dropped slightly. The line item they were pointing at wasn't municipal at all. What residents can do starts with understanding which piece of the bill is which. Pull your statement from the Milwaukee County Treasurer's site. Look for the breakdown by taxing district. If the county portion jumped, that's not the city's move. If the city portion spiked, check whether your property changed hands recently. A sale triggers the reassessment mechanism. If the house next door hasn't sold in a decade, its assessed value stays anchored while yours resets.
Get the Full Details
The Assessment Appeal Process I Actually Went Through
Filing an appeal in Milwaukee County isn't the horror story people make it sound like, but it's not simple either. You have 90 days from the notice date to file a complaint with the Board of Review. That window is strict. Miss it and you wait another year. The process is administrative first, litigation second. You don't need a lawyer for the initial hearing. Bring your evidence. Comparable sales, photos, repair estimates - whatever supports your position. The board reviews it on paper and votes. Their decision is binding unless you appeal to circuit court, and that's where costs escalate quickly. I took a case to the Board of Review myself last spring. The property was a single-family home in the Bronzeville area. The assessed value came in at $215,000. Market evidence suggested closer to $185,000. The gap wasn't huge in absolute dollars, but on a tax bill it added roughly $700 annually, and the client felt the assessment ignored recent roof and foundation work that needed attention. I pulled three comparable sales from the last six months within a half-mile radius. Two showed the same renovation discounts. One didn't. The board asked about the third. I admitted it was a flip with cosmetic work that wouldn't hold value. They reduced the assessment by $18,000. The annual tax savings came to about $340. Not life-changing, but valid. The thing nobody tells you about appeals is timing. If you file in January, right after the notice arrives, the board has less time to research. If you wait until the August deadline, they've had months to dig into your case. I've seen appeals rejected not because the evidence was weak but because the filing date slipped past the statutory window. The website says 90 days. It's 90 days. Not 91. Not "approximately."
Exemptions That Actually Move the Needle
Wisconsin offers several property tax relief programs, and Milwaukee residents qualify for most of them if they meet the criteria. The Homestead Credit is the big one. It kicks in when your property tax bill exceeds a certain percentage of your income. For a household making $60,000 a year, that threshold is roughly $1,800 in annual taxes. Below that, you get a credit on your state return. Above that, you get a partial credit. The calculation uses your gross income and your actual tax bill, not an estimate. You need the official statement from the treasurer. Veterans get additional relief. Disabled veterans can qualify for a full exemption up to a property value cap, which has been around $200,000 in recent years. Active duty military stationed out of state still count as Wisconsin residents for tax purposes if their home remains in the state. I've seen National Guard members deployed to Arizona file for the exemption without realizing they were eligible. The paperwork is straightforward - DD-214, disability rating letter, deed or lease. The county handles it. No need to involve the city. Senior citizen circuit breaker relief is another angle. If you're 65 or older and your income stays below the threshold, the program refunds a portion of your taxes. The income limits adjust annually. For 2024, a single person making under about $45,000 could qualify. A couple filing jointly needs to stay under roughly $60,000. These numbers shift. Check the DOR website each spring before you file.
There's also a Star-like program for Wisconsin, called the Homestead Exemption for disabled veterans or survivors. It's not federal. It's state-level. The benefit caps at around $50,000 in assessed value reduction. If your home is worth $300,000, that $50,000 cut matters. At Milwaukee's rate, it shaves off roughly $900 to $1,100 annually depending on the exact levy mix.

What the City Budget Documents Actually Say
Public records are available. The City of Milwaukee publishes its annual budget and tax rate resolutions. You can find them on the municipal website or at the clerk's office. The 2024 budget set the city tax rate at approximately $1.42 per $100 of assessed value. That's down slightly from 2023, which ran $1.48. The decrease came from pension contributions stabilizing and a shift toward enterprise fund recovery for certain services. Water and sewer now charge users directly instead of pulling from the general fund at the same ratio. That move lowered the residential levy requirement, but not by as much as the headline number suggests. The county rate tells a different story. Milwaukee County's rate climbed to about $2.35 per $100 in 2024. That's up from $2.18 the year before. The increase traced back to healthcare subsidies for the county system and debt service on capital projects. Those costs don't appear on city statements. They sit on the same bill but in separate lines. Residents who only look at the city portion miss the county movement entirely. School district levies are separate again. Milwaukee Public Schools operates under its own board and budget cycle. The Levy Limit Law caps how much revenue they can raise each year, but exceptions exist for state-funded programs and bond measures. The 2024-25 levy came to roughly $0.89 per $100. That's modest compared to the city and county, but it adds up when you're looking at a $250,000 assessed property.
Special districts are the wildcard. Some neighborhoods carry stormwater fees, sidewalk assessment charges, or lighting district fees that run for decades. I found a case in the Third Ward where a property owner was paying a streetlight fee from 1987 that the city had technically abolished in 2003 but never removed from the billing system. The fee was small - $12 annually - but it represented a systemic gap. The assessor's database didn't sync with the treasurer's ledger. I reported it to the city auditor's office and got a confirmation that the charge would be removed. Took four months. No apology, just action.
How to Pull Your Own Data
The Milwaukee County Property Assessment Portal is the starting point. Enter your address or parcel number. You'll see the assessed value, market value estimate, and historical assessments for the past decade. Download the PDF if you need it for an appeal. The City of Milwaukee Tax Rate page posts the current millage along with historical comparisons. Cross-reference both. If the city rate dropped but your bill rose, something else is driving the increase. Check the county line items and the school district levy. Run the math. The breakdown will tell you where the pressure is coming from. I keep a spreadsheet for myself. Address, assessed value, city rate, county rate, school rate, special district charges, total bill. Update it annually. Over three years, the pattern becomes obvious. Some years the city moves. Some years the county dominates. A few years both climb together. When both move, it's usually budget-driven. When only one shifts, it's usually policy-driven. The distinction matters if you're thinking about appeals or relocation.

The Limitations I Hit Personally
Appeals don't guarantee relief. The board has discretion. Sometimes they reduce the assessment. Sometimes they leave it alone. I've seen cases where owners brought solid comparable sales and the board denied the complaint anyway, citing market conditions that didn't appear in the record. The review standard is substantial evidence, not de novo review. You're asking them to reconsider their own work, which creates a bias toward maintenance. Circuit court appeals fix that only if you can show arbitrariness, and the bar is high. Judges defer to administrative findings unless they're clearly unreasonable. Exemptions help but they don't solve structural problems. The circuit breaker credit refunds a portion of taxes paid. It doesn't lower the bill. If your income qualifies, you get money back on your state return. If it doesn't, you pay the full amount. The homestead exemption for veterans helps those who served and were disabled. It doesn't help the young professional buying a fixer-upper who can't afford the assessment jump. The programs are narrow. They address specific hardships. They don't flatten the overall tax trajectory. The assessment system itself has limits. Milwaukee County reassesses annually, but the triggers are uneven. Sales create fresh valuations. Inactivity locks in old ones. That's by design in Wisconsin law, but it creates the disparity I described. Two neighboring houses can diverge by 20 to 30 percent in assessed value simply because one sold and the other didn't. The effect compounds over time. Each sale ripples through the nearby pool of comparables. The ripple slows down for non-selling properties. The gap widens.
There's also the question of whether higher taxes correlate with better services. Milwaukee spends more per capita on public safety than many suburban counterparts. The city fire departments, police units, and EMS cover a denser, more complex urban environment. The cost is visible on the bill. The benefit is harder to quantify. Residents in high-service neighborhoods notice potholes filled faster, trash pickup on schedule, streetlights working. Residents in underserved areas see the gap between rate and result. That tension shows up in elections, budget hearings, and the occasional lawsuit over equal protection. It doesn't resolve easily.
What I'd Tell Someone Standing at Their Mailbox With a Bill
Read the statement. Don't glance at the total. Look at each taxing district. Identify which line moved. Check whether your property sold recently. If it did, the reassessment is likely legal even if it feels unfair. If it didn't, and the value jumped anyway, that's appeal-worthy. Pull comparable sales. Get repair estimates if renovations hurt your case. File within 90 days. Show up to the Board of Review hearing with printed copies. Ask questions. Don't argue emotion. Argue numbers. If you're on a fixed income, explore the circuit breaker and senior exemptions. Run the income test first. The thresholds are modest. If you clear them, the relief is automatic once you file the application. Don't wait for the bill to arrive. File in February or March along with your state return. The county will reconcile the credit against your tax obligation. If you're considering selling, check the assessment history. A recent jump might indicate the new owner will inherit a higher base. That affects pricing strategy. A stagnant assessment might signal the house hasn't been updated, which could lower buyer interest. The tax story is part of the property story. It doesn't dominate it. It informs it.
I've spent enough years tracking these bills to know that the system is functional but uneven. It rewards people who understand the process. It penalizes those who don't. The paradox isn't that Milwaukee taxes are uniquely high. The paradox is that they're predictable once you know which piece to look at, and most residents never learn to read the breakdown. The tools exist. The transparency exists. The effort to use them is the variable.