Understanding Discount Rates and Future Cash Flow Valuation
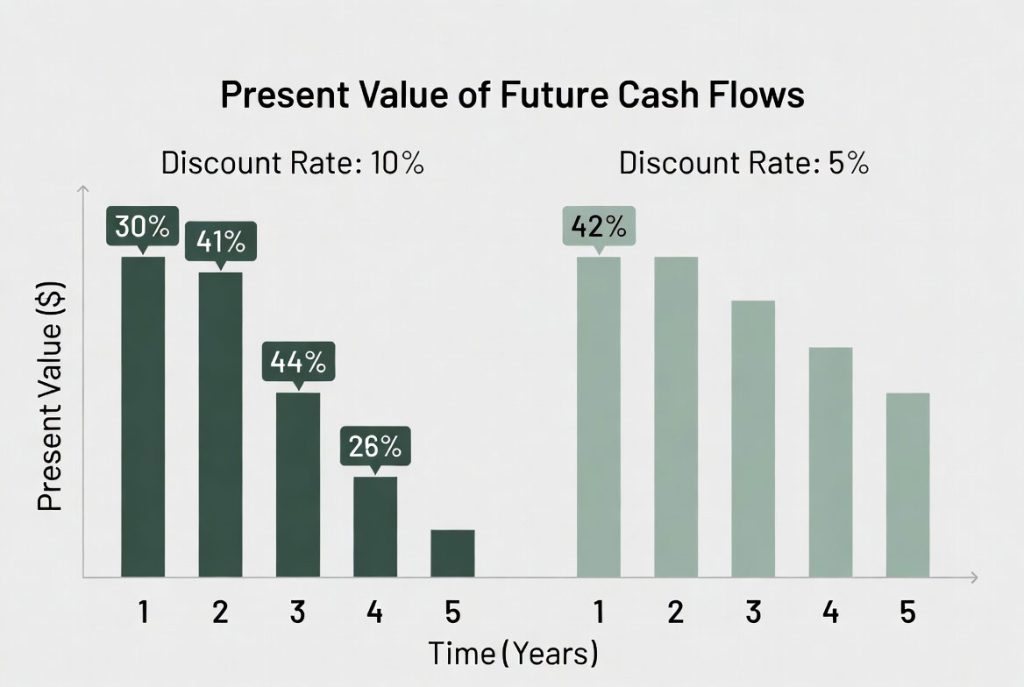
Most people treat the discount rate like a checkbox on a spreadsheet. You plug in 8 percent or 10 percent, hit calculate, and get a number. The problem is that the number you get back only matters if you actually understand what the discount rate is doing to your cash flow projections underneath it. Here is how it works in practice and where things go wrong. A discount rate is simply the inverse of time value of money. Every dollar you expect to receive two years from now is worth less than a dollar in your hand today, and the discount rate is the mathematical expression of that gap. The basic formula for present value is straightforward: you take a future cash flow and divide it by one plus the discount rate raised to the power of the period. A $100,000 cash flow expected in year five at a 10 percent discount rate gives you a present value of about $62,092. That is not a suggestion. That is the math. What most beginners miss is that the discount rate is not just a single variable you pick once and leave alone. It compresses three separate things into one number: the time value of money itself, the risk premium for uncertainty, and the opportunity cost of capital. When you change the discount rate from 8 percent to 12 percent, you are not just adjusting a risk assumption. You are implicitly saying the investment is more dangerous, the alternative uses of capital are better, or both. The present value of that same $100,000 in year five drops from $62,092 to $56,743. The difference is $5,349. That is not rounding error. That is the difference between approving a project and killing it.
I ran into this exact problem when valuing a manufacturing facility expansion for a mid-market company. The CFO wanted a 12 percent discount rate applied to all projected cash flows because the company's weighted average cost of capital sat around that level. The projected cash flows looked solid on paper. At 12 percent, the net present value was barely positive. I dug into the cash flow schedule and found that 70 percent of the projected inflows were concentrated in years four through seven. That is deep enough in the future that even a small shift in the discount rate completely flips the outcome. I rebuilt the model using a two-rate approach where the risk-free rate and a spread component were separated out. The risk-free portion was anchored to the five-year Treasury yield, which was around 4.5 percent at the time, and the spread was applied only to the cash flows that carried genuine execution risk. The revised present value came in roughly 18 percent higher than the original model. The CFO was not wrong about the risk. The original model was just collapsing too much uncertainty into a single blunt rate. There is a specific edge case that people rarely talk about. When you are dealing with negative cash flows in early periods followed by positive cash flows later, a higher discount rate can actually increase the present value of the project. This happens because the early negative cash flows get discounted more heavily, reducing the present value of the losses more than it reduces the value of the later gains. It feels backwards. It is not. This is why discount rate selection matters even more for capital-intensive projects with long payback periods. I once saw a venture fund reject a software infrastructure play because they applied a 25 percent hurdle rate uniformly across all years. The cash flow pattern had a heavy upfront build cost and revenue ramping in year three and beyond. At 25 percent, the NPV was deeply negative. At 14 percent, which was closer to their actual blended cost of capital, the project broke even. They walked away from a deal that was viable. They also walked away because they did not account for the fact that early-stage infrastructure investments carry a different risk profile than the operating cash flows they produce later. Another thing nobody emphasizes enough is the interaction between discount rate and inflation assumptions. If your cash flow projections include embedded inflation but your discount rate does not, you are double-counting or undercounting depending on which way you mess it up. The rule of thumb is simple: nominal cash flows paired with a nominal discount rate, and real cash flows paired with a real discount rate. Mixing them produces numbers that look precise but are internally inconsistent. I have seen analysts use a 9 percent nominal discount rate against cash flows that were explicitly stated in real terms, assuming 2 percent annual inflation. The resulting present value understated the true value of the project by roughly 15 to 20 percent over a ten-year horizon. It is a quiet error. It compounds.
Here is how you should actually approach this when you are building a valuation from scratch. First, define the cash flow type. Are these free cash flows to the firm, free cash flows to equity, or something else? The discount rate must match the cash flow definition. Free cash flows to the firm use the weighted average cost of capital. Free cash flows to equity use the cost of equity. Using the wrong rate for the wrong cash flow is the single most common mistake I see in professional settings. Second, build the discount rate from the ground up instead of borrowing someone else's number. Start with the risk-free rate. Add the equity risk premium scaled by the appropriate beta. Adjust for size premium if applicable. Layer in country risk if the cash flows are outside your home market. Each of these components is debatable. That is fine. The point is that you are making each assumption visible instead of hiding it inside a single opaque percentage. Third, run sensitivity analysis. A single discount rate gives you a single present value. That is a false sense of precision. Vary the rate across a reasonable range. Ten percent to twelve percent. Twelve percent to fourteen percent. Watch how the NPV moves. If the result is highly sensitive to the discount rate, you need to spend more time defending that rate than you would if the valuation were relatively stable across a wide range. A stable valuation across a five percentage point swing in the discount rate is actually a strong signal that the project has robust economics. A volatile valuation is a signal to either improve the underlying cash flows or walk away before you commit capital. The discount rate also interacts with terminal value calculations in a way that tends to break beginner models. In most DCF models, the terminal value accounts for 60 to 80 percent of the total present value. When you raise the discount rate, the terminal value shrinks disproportionately because it is far out in the future. I worked on a healthcare services valuation where the analyst used a 11 percent discount rate and a 2.5 percent terminal growth rate. The terminal value was $340 million out of a total enterprise value of $410 million. When we adjusted the discount rate down to 9.5 percent based on updated credit spreads, the terminal value jumped to $420 million and the total enterprise value shifted by nearly 25 percent. The operating cash flows themselves changed very little. The entire movement came from the discount rate interacting with the terminal period. This is why terminal value assumptions deserve more scrutiny than they usually get.
Get the Full Details

There are also scenarios where the discount rate approach breaks down entirely. Startups with no near-term cash flows, assets in decline industries where the cash flow pattern is non-monotonic, and situations involving strategic optionality where the value comes from flexibility rather than predictable cash flows. For startups, a traditional DCF with a high discount rate will almost always produce a misleadingly low valuation because the model cannot capture the option value of pivoting or scaling. For declining assets, the discount rate masks the real issue, which is that the cash flows themselves are structurally shrinking. In those cases, relative valuation methods or scenario-based approaches tend to be more honest about what you are actually measuring. If you want a practical way to make this faster, I build my initial models in a spreadsheet with the discount rate in a single top-level cell. Every present value calculation references that cell. When I need to stress-test, I use data tables to generate a grid of discount rate versus growth rate combinations and watch the NPV output shift. This cuts the time I spend on sensitivity analysis from several hours down to maybe twenty minutes. The model does the work. You focus on interpreting the results instead of recalculating each scenario by hand. The bottom line is that the discount rate is not just a number you insert into a formula. It is a statement of belief about risk, alternative returns, and the economic environment. Get it wrong and your valuation is garbage regardless of how polished the spreadsheet looks. Get it right and you have a decision tool that actually works. The difference between those two outcomes comes down to understanding what the rate represents and being willing to defend each component instead of treating it as an afterthought.