Understanding East Asia as a Region
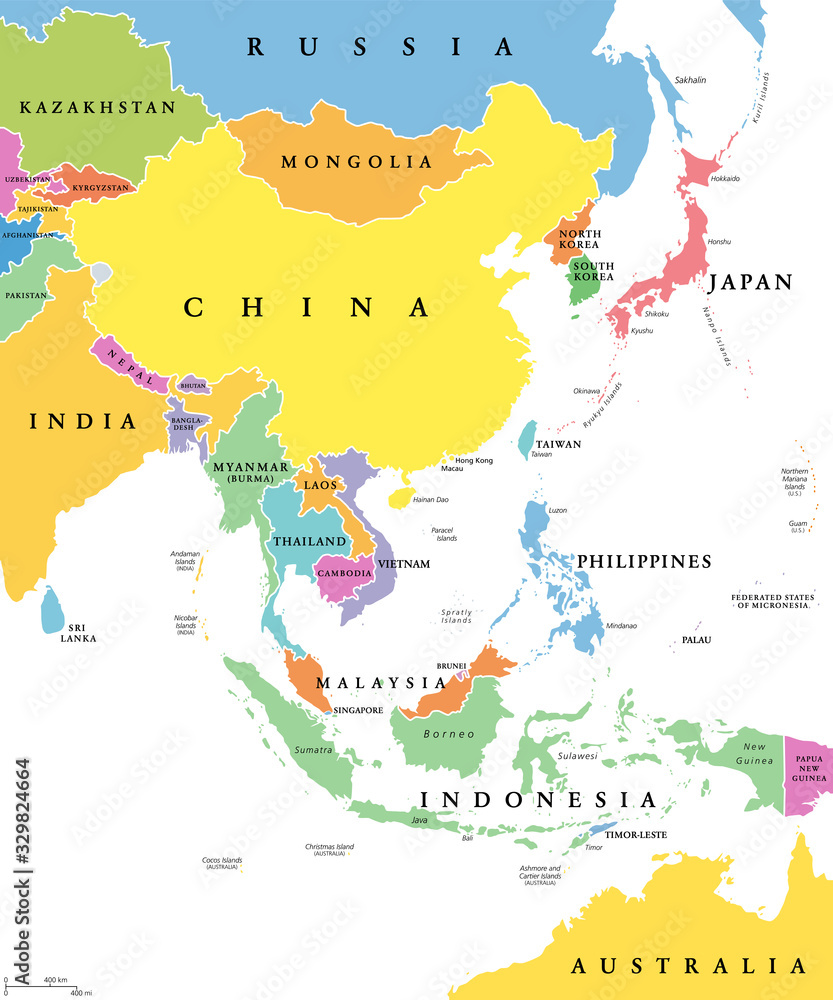
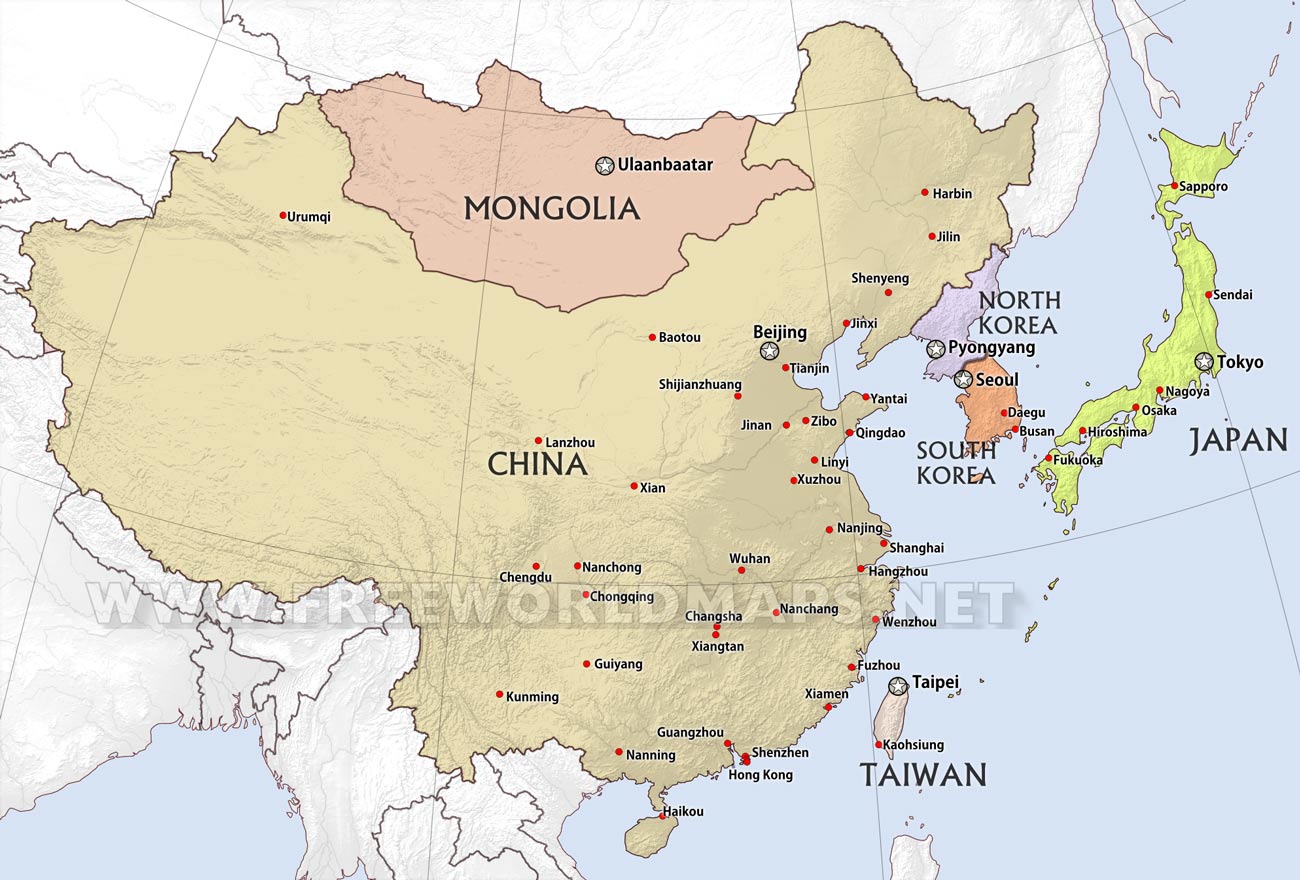
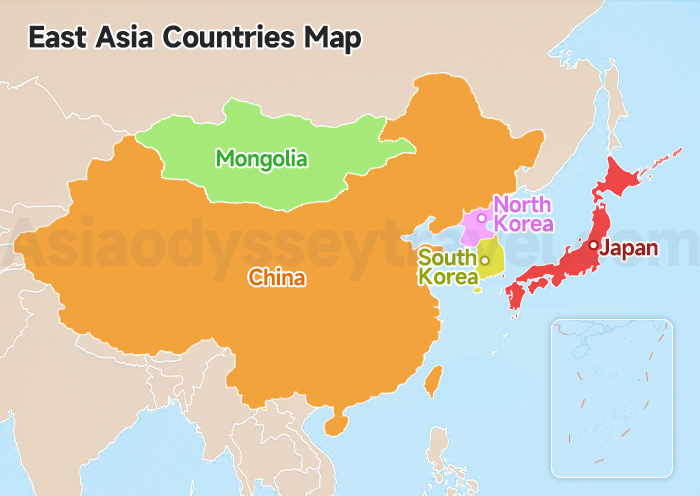
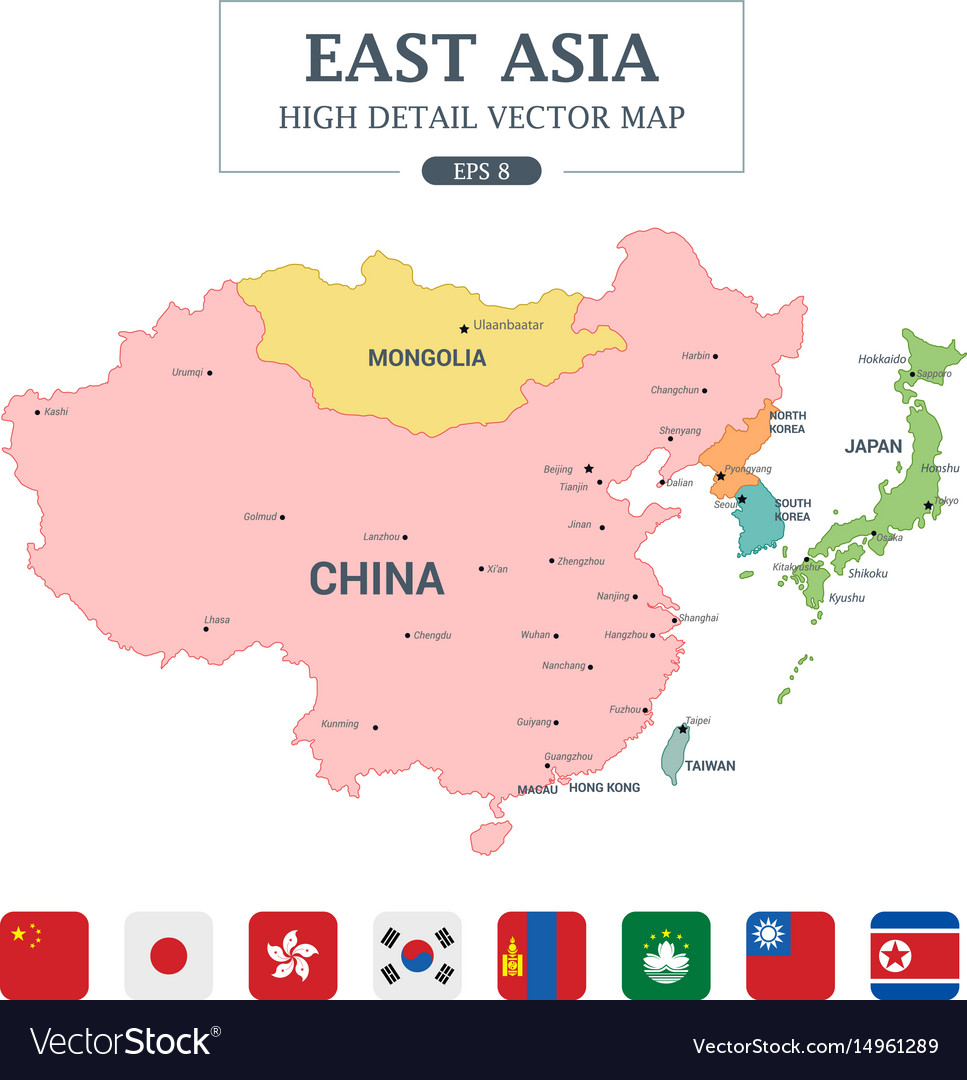
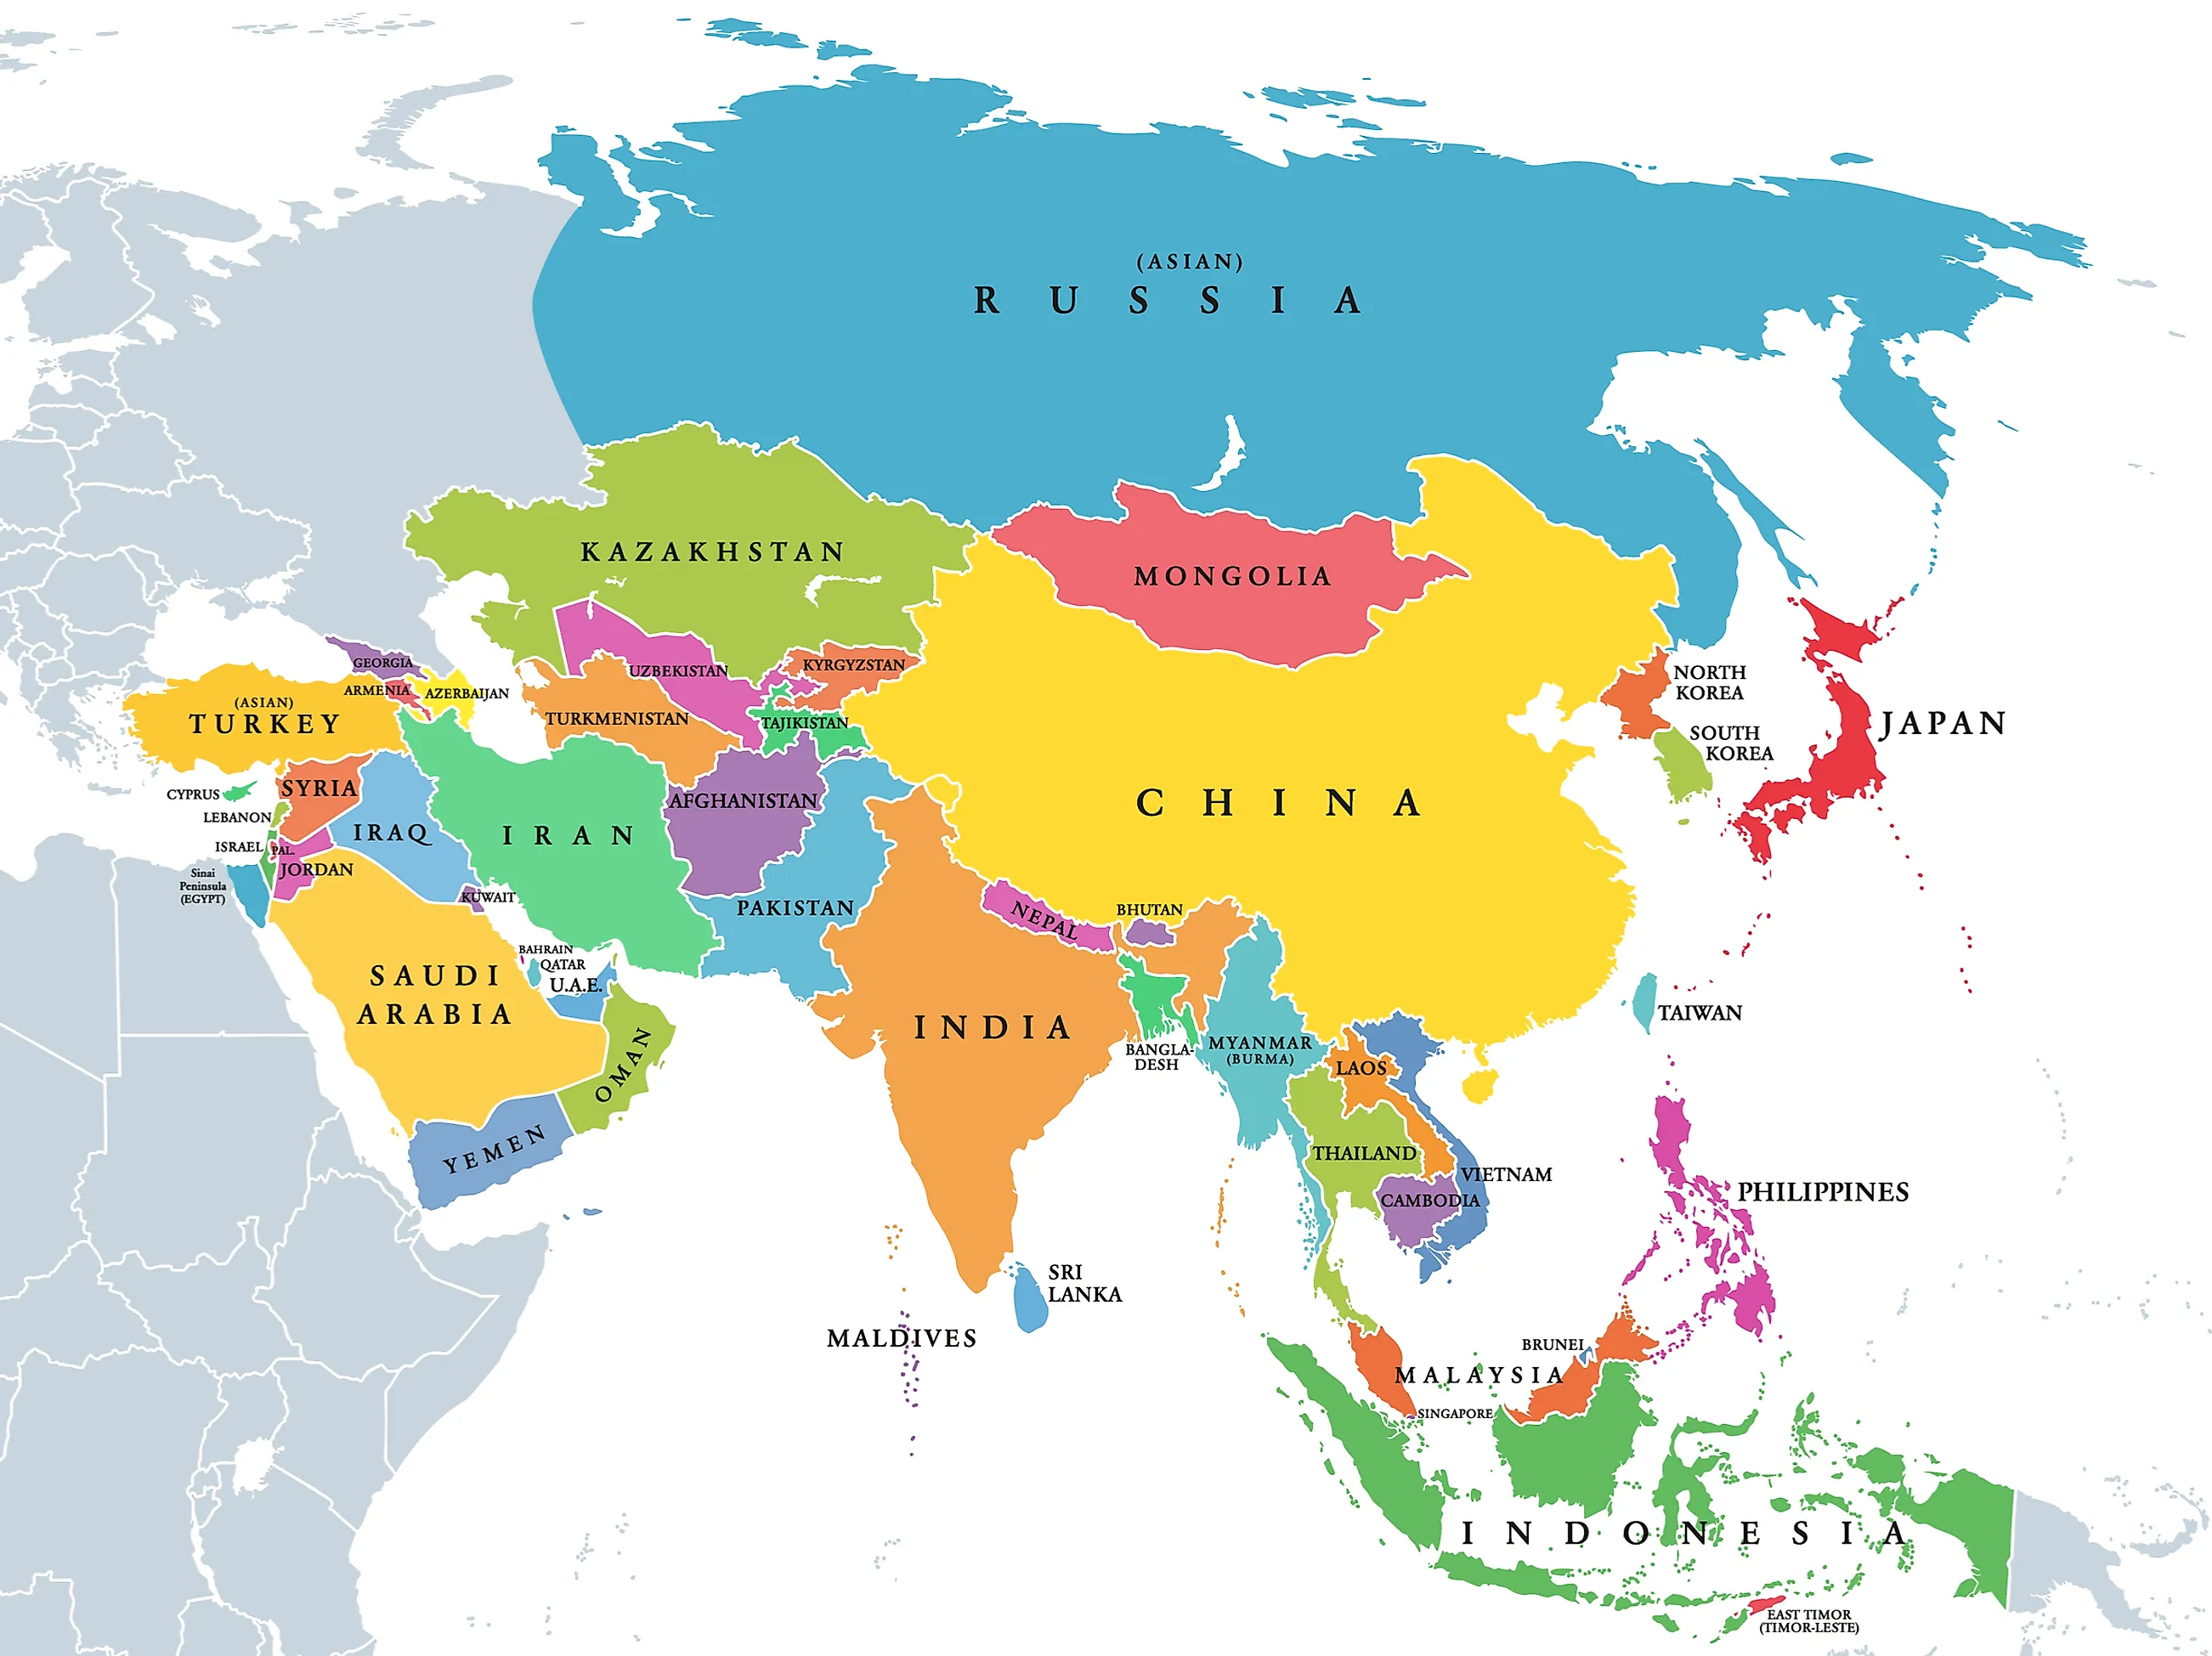
East Asia is a region that people often try to describe in broad strokes, calling it a cultural sphere or an economic powerhouse without actually doing the work. The region encompasses China, Japan, South Korea, North Korea, and Mongolia, with Taiwan and Hong Kong as distinct sub-regional entities. These places share historical patterns of statecraft, script-based writing traditions in some cases, and deep interconnection through trade routes that go back over a thousand years. But treating them as a single block misses the actual mechanics of how power and development operate there. East Asia's economic power doesn't come from any single factor. It comes from a stacking sequence that took decades to build. Japan industrialized first during the Meiji Restoration, moving from a feudal economy to a manufacturing base by the late 1800s. South Korea and Taiwan followed the export-led growth model in the 1960s through 1980s, using state-directed credit, protective tariffs, and export discipline. China picked up the mantle starting in 1978 with Deng Xiaoping's reforms, eventually becoming the factory of the world by the early 2000s. Each wave displaced the previous one in labor-intensive manufacturing while pushing up the value chain. The result is a supply chain ecosystem that is extraordinarily difficult to replicate elsewhere. When I worked on cross-border logistics optimization for a regional distribution network, I learned that moving assembly operations out of the Pearl River Delta didn't just shift cost structure. It meant losing access to a density of component suppliers, mold makers, and contract engineers that exists nowhere else on Earth. We tried setting up a parallel facility in Vietnam as a hedge. It took fourteen months and roughly triple the projected budget just to reach the same throughput levels the Shenzhen cluster hit in week two. The infrastructure was there. The institutional knowledge wasn't.
The Power And Promise Of East Asia A Comprehensive Look At The Regions Countries
That promise is real but conditional. China still accounts for roughly 60 percent of East Asia's GDP. Japan's economy has stagnated in real terms for over two decades, yet it remains the third-largest national economy globally with a per capita income that South Korea has now surpassed. South Korea's semiconductor industry dominates global memory chip production. Japan still leads in precision machinery and advanced materials. North Korea exists as a closed economy with no reliable data, though satellite imagery and defector testimony suggest its military-industrial complex receives disproportionate resource allocation relative to civilian needs. The innovation story in East Asia is not a simple upgrade path from copying to creating. South Korean firms like Samsung and LG invested billions in R&D before they had any domestic market advantage. They were buying patents and licensing technology while simultaneously training engineers to improve upon imported designs. That dual strategy of acquisition and iteration is what actually moved them up the value chain. Chinese firms followed a similar arc but on a larger scale, using domestic market size to subsidize learning curves that would be unsustainable in smaller economies. The gap between rhetoric and reality becomes clear when you look at patent filing data. China files more patents than any country in the world, but utility model patents account for roughly 60 percent of those filings. Utility models require no substantive examination in China, which means a massive volume of low-quality filings inflate the raw numbers. Japan and South Korea file fewer patents but with significantly higher citation rates and commercialization ratios. That's the metric that matters for actual innovation output.
Demographic Realities
Demographics are the single biggest constraint on East Asia's future trajectory, and most discussions about the region gloss over the severity. Japan's population is declining at about 0.5 percent annually with a median age of 48. South Korea's fertility rate dropped to 0.72 in 2023, the lowest in the world by a wide margin. China's working-age population began shrinking around 2012, and the total population decline accelerated after 2022. These aren't projections. They're current data. Automation is the standard answer to labor shortages, and it works up to a point. I ran automation assessments for a manufacturing client trying to replace 200 assembly line workers in their Dongguan facility. The engineering firm quoted a fully automated line at about 18 million yuan, with a payback period of nine years assuming stable demand. Then demand dropped 30 percent the following quarter due to trade tensions. The automation became a stranded asset. China's robotics installations grew from under 10,000 units annually in 2015 to over 290,000 in 2022, but the utilization rate on that equipment varies wildly by sector and region. Simple assembly tasks that robots handle well have been automated quickly. Complex tasks requiring dexterity and judgment remain expensive to automate even in East Asia.
Get the Full Details
Geopolitical Risk Assessment
Moving beyond the general framing of China as a strategic competitor requires understanding the specific risk vectors that actually affect business and policy decisions. Taiwan remains the most dangerous flashpoint. A blockade or conflict involving Taiwan would disrupt at least 60 percent of global semiconductor advanced node production through TSMC's operations in the island. That is not speculative. TSMC produces roughly 90 percent of the world's most advanced chips, and the vast majority of that capacity sits on Taiwan. Japan-South Korea relations complicate the picture further. These two countries share intelligence and face the same security threats from North Korea, yet historical disputes over wartime labor and comfort women periodically rupture cooperation. When those disputes escalate, as they did in 2019 and again in 2022-2023, export control coordination between Tokyo and Seoul degrades. Japan's 2019 restriction on semiconductor materials exports to South Korea was a direct escalation that disrupted supply chains across the region. It was resolved diplomatically but revealed how thin the institutional framework for economic cooperation is beneath the surface.
Infrastructure And Connectivity
China's Belt and Road Initiative extends eastward through maritime routes connecting Chinese ports to Southeast Asian and South Asian markets. But the domestic infrastructure within East Asia is equally significant. The Shanghai-Singapore high-speed rail corridor, Japan's Shinkansen network spanning over 3,000 kilometers, and South Korea's extensive highway and rail system create a continuous logistics spine. China's high-speed rail network alone exceeds 45,000 kilometers, which is more than the rest of the world combined outside of China. The port infrastructure tells a similar story. Shanghai, Singapore (though not East Asian, it functions as the regional hub), Busan, and Ningbo-Zhoushan form a chain of megaports handling over 200 million TEUs annually between them. When the Suez Canal blocked in 2021, these ports adjusted scheduling and rerouting within days. The resilience comes from redundancy built into the system over decades of incremental investment.
Education And Human Capital
East Asian education systems consistently rank at the top of PISA assessments in mathematics, science, and reading. That correlation with economic performance is real but often overstated. South Korea and Japan invest roughly 5 to 6 percent of GDP in education, comparable to or exceeding OECD averages. China's investment has risen from about 2.5 percent in the early 2000s to over 4 percent recently. The output in engineering and STEM graduates is substantial. China awards roughly 1.5 million engineering bachelor's degrees annually, compared to about 50,000 in the United States. The problem emerges when graduate quality doesn't match quantity. Regional universities in western China produce engineering graduates at scale, but placement rates in innovative industries remain low. The mismatch between graduate skills and employer needs is a persistent issue that admissions data alone doesn't capture. I reviewed recruitment outcomes for a staffing firm placing technical talent across Chinese provinces, and the data showed a consistent pattern: top employers in coastal cities could fill advanced positions from local talent pools, while inland factories struggled to find candidates who met basic specification requirements despite high graduation numbers.
Environmental Constraints
East Asia faces severe environmental headwinds that constrain long-term development. Air pollution in major Chinese cities has improved dramatically since 2013 due to aggressive coal consumption controls, but ground-level ozone and fine particulate matter remain problematic. Water scarcity affects northern China seriously, with the North China Plain drawing heavily from depleting aquifers. Japan deals with aging infrastructure in seismically active zones, requiring constant capital expenditure just to maintain service levels. South Korea's water import dependency is another underrated factor. The country imports approximately 60 percent of its caloric needs, making food security a strategic vulnerability that receives insufficient public attention. Agricultural land per capita has fallen below 0.1 hectares in several Korean provinces, and rural depopulation accelerates the trend yearly.
Where The Model Breaks Down
The export-led growth model that powered East Asia's rise has diminishing returns at every level. China's debt-to-GDP ratio exceeds 300 percent when shadow banking is included. Local government financing vehicles hold trillions in obligations with unclear repayment mechanisms. Japan's public debt stands at over 250 percent of GDP, sustained only because most of it is held domestically by the Bank of Japan and domestic institutions. South Korea's household debt-to-GDP ratio is among the highest in the world, exceeding 100 percent in recent years. These imbalances don't break the system immediately. They create fragility that compounds over time. A currency crisis, a banking sector shock, or a prolonged demand collapse in key export markets could trigger cascading failures. The 1997 Asian Financial Crisis showed how quickly regional contagion works. The damage from that crisis took South Korea and several other affected countries nearly a decade to fully recover from, and the political consequences reshaped governance structures across the region.
What Comes Next
East Asia's next growth phase depends on productivity gains rather than factor accumulation. Labor forces are shrinking. Capital returns are declining. The remaining upside comes from technological advancement, institutional reform, and deeper regional integration. The Regional Comprehensive Economic Partnership (RCEP) creates the world's largest free trade bloc by GDP, covering roughly 30 percent of global output. But tariff reductions alone won't solve structural problems. Services liberalization, intellectual property enforcement, and regulatory harmonization matter more for productivity growth than additional tariff cuts on manufactured goods. The region's promise is real but bounded by demographic decline, environmental stress, and geopolitical risk. The power is current and concentrated but not permanent. Countries that adapt institutional frameworks to support innovation and consumption rather than continuing to rely on export and investment-driven growth will maintain advantage. Those that don't will find their economic weight translating into less influence over time. The data supports that trajectory. The question is whether policy will follow.