Why Palm Oil Prices In India Make No Sense At First Glance
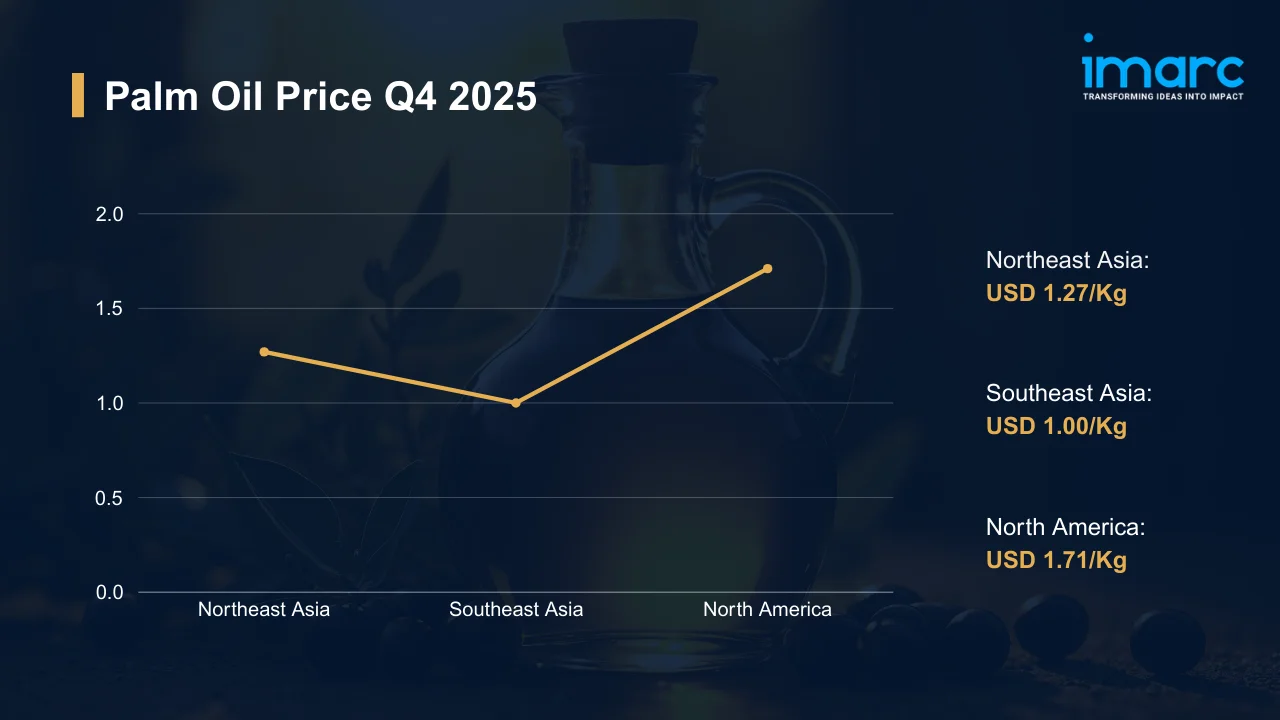
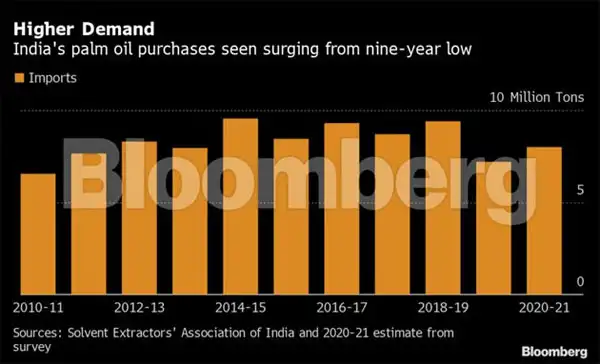
I spent about four years tracking edible oil procurement for a mid-sized distributor in Mumbai and Gujarat. One of the first things that confused me was the pricing disconnect. You would see Malaysian crude palm oil drop 8% in a single week, check the Indian market the next day, and wholesale refined palm oil had actually gone up. That contradiction is not a glitch. It is the core of what traders call The Palm Oil Price Paradox Unraveling The Story Of Palm Oil Prices In India, and understanding it matters if you are buying, selling, or just trying to predict what your grocery bill will look like. India imports roughly 60 to 65 percent of its total edible oil consumption, and palm oil is the single largest component of that basket. You would logically assume Indian palm oil prices move in lockstep with the Malaysia and Indonesia benchmarks, but they do not. The paradox exists because three separate pricing mechanisms collide every time a shipment lands. The first is the international FOB price, usually quoted in US dollars per metric ton on the Malaysian exchange. The second is the rupee exchange rate, which can swing independently of commodity trends. The third is the domestic tax and duty structure, which changes more often than anyone outside the customs brokerage world seems to track. Here is a concrete example from my experience. In early 2022, CPO futures fell from above USD 3,800 per ton to roughly USD 3,200 over six weeks. That should have meant cheaper palm oil in India. Instead, landed costs in Kandla and Mumbai rose by about 6 to 9 percent. The rupee weakened against the dollar during that window, and India's basic customs duty on crude palm oil was hiked as part of a broader fiscal move to protect domestic oilseed farmers. The duty increase alone added roughly USD 120 to USD 150 per ton to the landed cost, wiping out most of the CPO decline and then some. Buyers who were only watching Kuala Lumpur got caught flat-footed.
The Real Cost Formula Nobody Admits To
There is a simplified equation that most traders actually use in their heads, even if they would never write it down in a client email. The landed cost in India equals the FOB price plus freight, minus any export tax from the producing country, converted to rupees, plus the basic customs duty, plus the social welfare surcharge, plus GST at the applicable rate, minus any refunds from the Drawback or MEMS schemes, plus port handling and demurrage. It sounds straightforward until you realize each variable moves on a different timeline. Freight rates for VLCC and Aframax tankers can change weekly based on Suez Canal disruptions or seasonal demand spikes. Customs duties are announced by the finance ministry and can take effect within days. GST rates are more stable but still subject to council revisions. The rupee fluctuates against the dollar throughout the trading day. So by the time you calculate your actual landed cost, the CPO price you quoted two weeks ago might be completely irrelevant. I learned this the hard way when a contract I signed at USD 3,400 FOB ended up costing me 11 percent more than my margins assumed because the rupee depreciated by 4 percent and freight doubled during transit. The buyer did not complain because he understood the mechanics. The supplier did, too, which is why some of them build in sharper escalation clauses now.
Why The Paradox Feels Worse Than It Is
Most people reading about palm oil prices in India only see the retail pack price or the wholesale rate in Azadpur mandi. They do not see the inventory layers sitting between the port and the shelf. Refined oil passes through at least three stages: importers hold crude, solvent extraction plants refine it into RBD palm olein and RBD palm stearin, and distributors stock further before selling to FMCG brands or food service operators. Each stage adds a margin and each stage holds risk. When demand is uncertain, that risk premium shows up as price rigidity. Prices drop slower than they should because refiners and distributors do not want to mark down inventory they already bought at higher costs. Prices rise faster than they should because everyone knows a supply squeeze is coming and starts building buffers. The paradox also feels larger because India does not produce significant quantities of palm oil domestically. The total domestic output from Kerala and small northeastern plantations is negligible at the national scale. That means every single metric ton is imported, which makes the currency element far more consequential than it would be for a country with mixed domestic and imported supply. When the rupee weakens, there is no domestic cushion. When it strengthens, the benefit gets eaten by port charges and intermediary margins before it reaches the consumer.
Get the Full Details

What Retail Buyers Actually Feel
If you are a manufacturer buying refined palm olein for snacks, biscuits, or packaged foods, the price you negotiate is not the CPO futures price. It is usually quoted as a premium over a benchmark, typically the Singapore Platts or the Indian spot average published by trade portals. That premium reflects refining costs, packaging, credit terms, and delivery logistics. During normal periods the premium sits in a fairly tight band. During volatile periods it widens dramatically because refiners cannot hedge effectively when import duty changes happen without warning. I once had to source 400 metric tons of RBD palm olein during a period when the government announced an unexpected duty cut on crude. The spot market reacted instantly. Importers who held physical stock under the old duty structure refused to sell at the old agreed price and demanded renegotiation. The refiner I was dealing with told me his margins were squeezed because he had already committed crude purchases at the higher duty regime. We ended up splitting the difference and I paid about 4 percent more than the quoted benchmark would have suggested. It was not fair in a pure sense, but it was how the market worked that week. People who tell you prices are transparent in this sector have not been paying attention to the spot trades.
Pitfalls That Catch Everyone Off Guard
The biggest mistake I see buyers make is assuming the parity calculation is static. It is not. A correct parity check requires you to model the full import cost stack at current rates, then compare it against the domestic spot price. If the domestic price is significantly above parity, it usually means either freight is elevated, inventory is tight, or importers are pricing in an anticipated duty change. If domestic price is below parity, it usually means there is excess stock or someone is desperate to move product before a seasonal demand drop. Neither situation lasts long, but both create pricing confusion that makes the paradox seem permanent. Another pitfall is ignoring the product split. Crude palm oil, RBD palm olein, and RBD palm stearin do not move in perfect sync. Olein is the cooking and processed food grade. Stearin goes into margarine, shortening, and sometimes biodiesel. When olein demand surges but stearin demand falls, the refined price gap widens. You can see CPO stable while olein premiums jump. I once missed a hedging opportunity because I was watching the crude benchmark and not the olein spread. By the time I noticed the premium had expanded by USD 80 per ton, the window was gone.
A Practical Way To Track What Is Actually Happening
If you need a working method instead of a textbook definition, here is what I used. You pull the daily CPO closing price from Bursa Malaysia. You convert it to rupees using the forward rate for the shipment date, not the spot rate, because imports usually settle on forward contracts. You add the prevailing freight rate for an Indonesia to India route, which you can find from Baltic Exchange summaries or shipping broker quotes. You add the current basic customs duty and surcharge. You add port and clearing costs, which average roughly USD 25 to USD 40 per ton depending on the terminal. You get your landed parity cost. Then you compare it to the actual spot price for RBD palm olein in western India, adjusted for the olein premium over crude, which typically ranges from USD 60 to USD 120 per ton depending on refining capacity utilization. This process takes about 20 minutes once you know where to look. It cuts through the noise of headline CPO moves and tells you whether Indian prices are cheap or expensive relative to what they should be. When the spread between your calculated parity and the actual spot price exceeds USD 100 per ton in either direction, something unusual is happening. Usually it is a duty announcement, a monsoon-related freight disruption, or a sudden shift in government stock release policy. Pinpointing which one it is will save you from making decisions based on incomplete information.

When The Paradox Breaks Completely
There are moments when the normal relationship between international benchmarks and Indian prices stops making sense altogether. The most notable recent episode came when India imposed anti-dumping duties on certain imported edible oils alongside routine duty changes. For a few months, the parity model gave you numbers that looked absurdly high compared to what traders were actually paying in the spot market. The reason was not a flaw in the formula. It was informal trading channels, mismatched customs valuations, and temporary government exemptions that existed outside the published duty schedule. I encountered this when a supplier offered me cargo at a price that implied an effective duty far lower than the legal rate. I declined because the paperwork did not add up and the risk of container detention at port was real. The buyer who took that cargo learned why compliance matters in this market. Another scenario where the paradox fractures is during extreme weather events in producing countries. When Indonesia closes ports for several days due to flooding or enforces sudden export restrictions, the CPO price reacts instantly. Indian buyers locked into existing contracts do not feel the immediate impact, but the next round of purchases prices in the disruption with a lag that varies by contract length and inventory depth. The result is a temporary decoupling where Indian domestic prices appear stable while the international market is moving violently. That stability is illusory and usually ends within two to four weeks once contracts roll over.
What This Means For Decisions You Make
If you are a buyer, do not anchor your pricing to the CPO headline number alone. Track the rupee forward curve, watch duty notifications from the board of trade, and maintain a rolling parity calculation. The tools exist. You do not need expensive software. A spreadsheet with daily updates and a few reliable data sources will serve you better than instinct. If you are selling, understand that your price ceiling is not just your cost plus margin. It is also what the market believes parity should be at that moment. When parity is weak, buyers will push harder on premiums and demand longer credit terms. When parity is strong, they accept tighter terms because the alternative is paying more later. The paradox is not a puzzle to be solved. It is a feature of a market that sits at the intersection of currency risk, policy volatility, and global commodity supply. The people who profit from it are not the ones who predict perfectly. They are the ones who build models that are wrong in a controlled way, keep their execution flexible, and move fast when the variables realign.