Palladium: A Practical Look At Its History And Market Dynamics
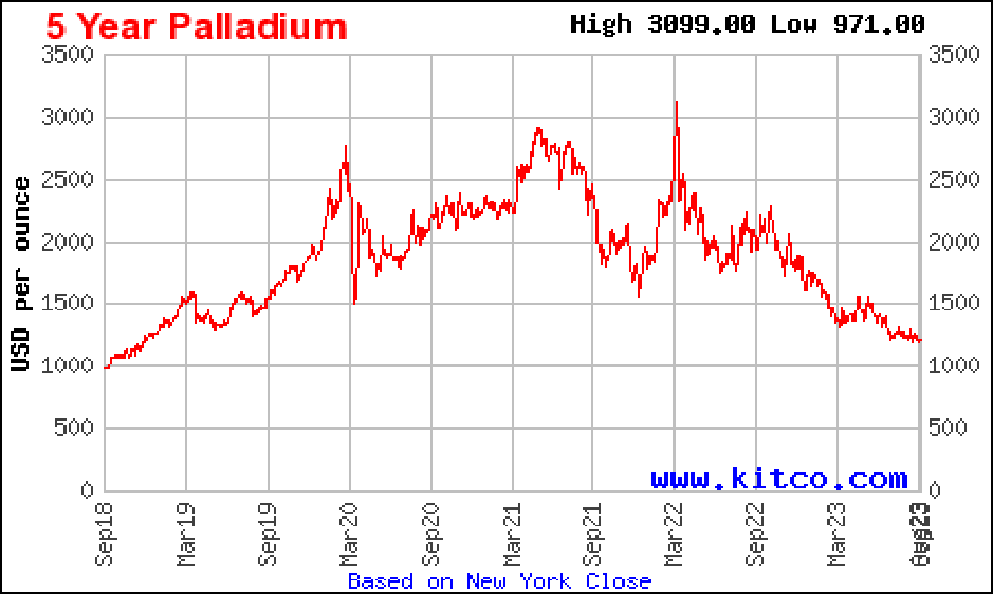
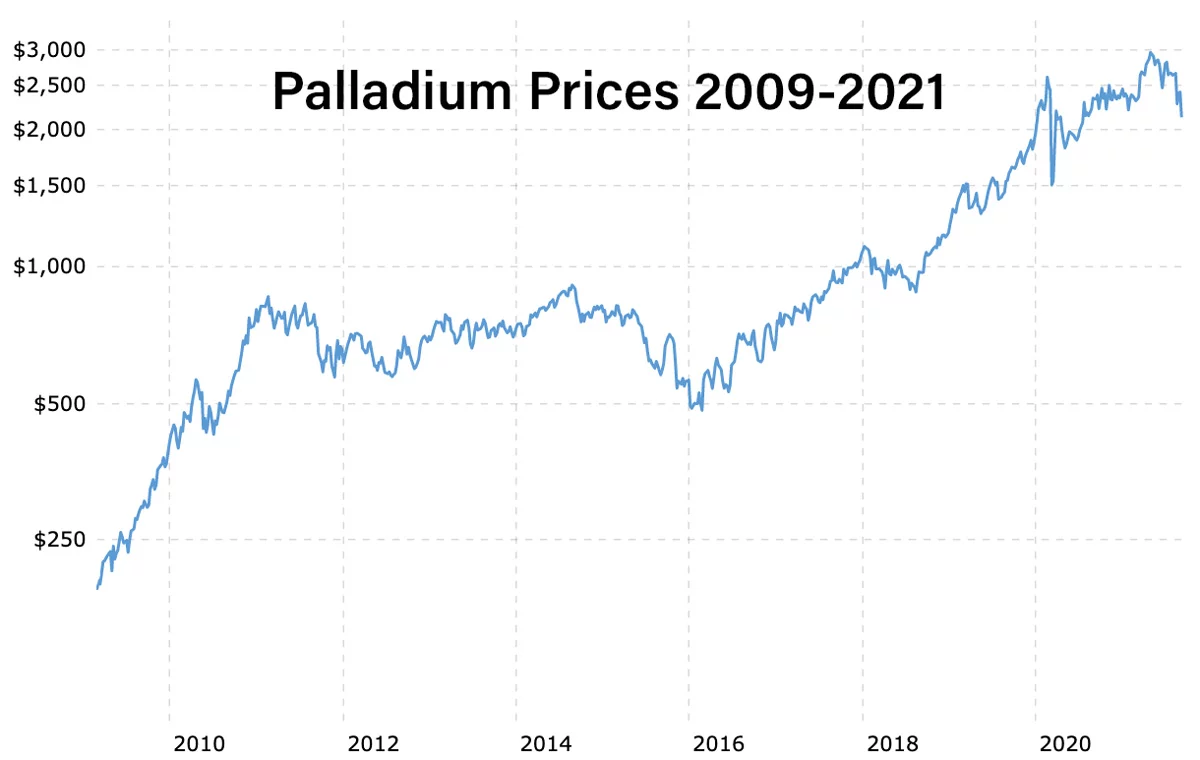
Palladium sits in the same column of the periodic table as platinum, and most people who buy it don't know why. It entered industrial demand through catalytic converters in the late 1980s, when emissions regulations started tightening in North America and Japan. Before that, it was mostly a lab curiosity and a partner to platinum in jewelry. Now it carries its own price, its own liquidity, and its own headaches. I've tracked this metal through three full supply-demand cycles, and the pattern never repeats itself cleanly. In 2018, prices spiked above 2700 dollars per ounce. Two years later, they dropped below 1600. That second move wiped out most of the paper gain for anyone who had been sitting on allocated bars. The metal didn't change. The demand drivers shifted faster than anyone's hedging strategy. Palladium is a member of the platinum group metals. Refiners produce it as a byproduct of nickel mining in South Africa and Russia, and also from copper deposits in Zimbabwe. The supply chain is concentrated. Moscow and Johannesburg control roughly 75 percent of mined output. That concentration shows up in delivery delays, not just spot prices. When sanctions hit or rail lines freeze, physical premiums spike and futures become harder to settle.
The industrial use is narrow but sticky. About 80 percent of palladium goes into gasoline engine catalysts. Diesel engines use mostly platinum. Electric vehicles use none at all. That split matters because every announcement about EV adoption sends palladium selling pressure through the market, even though the actual displacement of demand plays out over a decade, not a quarter. I learned this the hard way in early 2020. I held a position based on ICE vehicle sales data, which was still growing year over year. The fundamental picture said the metal should trade higher. Then China locked down in February, and gasoline demand collapsed by nearly 30 percent month over month. The spot price dropped 40 percent in six weeks. My hedge using platinum was uncorrelated enough to do nothing useful. I ended up selling at a loss and buying back three months later at the same level I first sold. The physical market never knew what it wanted to price at during that window. Palladium recycling is a real supply source, but it lags demand by five to seven years because the metal gets trapped in cars on the road. You cannot scrape it out of a in a day. Most recycling comes from industrial scrap and end-of-life vehicles. South African refiners process about 25 percent of recycled supply. The rest comes through independent processors in Europe and North America, each with their own assay standards and yield curves.
How The Spot Market Actually Prices The Metal
The London Palladium Fix runs once a day. It uses a limited set of bidders: Johnson Matthey, Heraeus, Valcambi, and a handful of trading houses. That concentration means the fix can drift from physical market conditions for days at a time. I've seen it lag spot by 80 dollars per ounce during thin trading weeks, then snap back overnight when Chinese buyers stepped in. Commitment of Traders reports show commercial hedgers running net short about 35 percent of outstanding futures contracts. That ratio flips violently when Russian supply threatens to tighten. In March 2022, after sanctions hit, the short ratio compressed to nearly 15 percent. Prices ran 60 percent higher in ten sessions. The physical premium over futures spiked to nearly 120 dollars per ounce. Allocators who needed delivery for Q2 production ended up paying nearly 3200 dollars per ounce and taking delivery three weeks later. Palladium inventory data from the COMEX and LBMA shows about 850,000 ounces of registered stock. That number means almost nothing during a supply disruption. The metal gets trapped in exchange warehouses, but delivery requires approved assayers. Johnson Matthey and Heraeus control roughly 60 percent of refined supply. Smaller refiners in Tokyo and Switzerland add another 15 percent. The rest comes from Russian plants that faced export restrictions in 2023.
Get the Full Details
The Demand Side And Why Prices Move
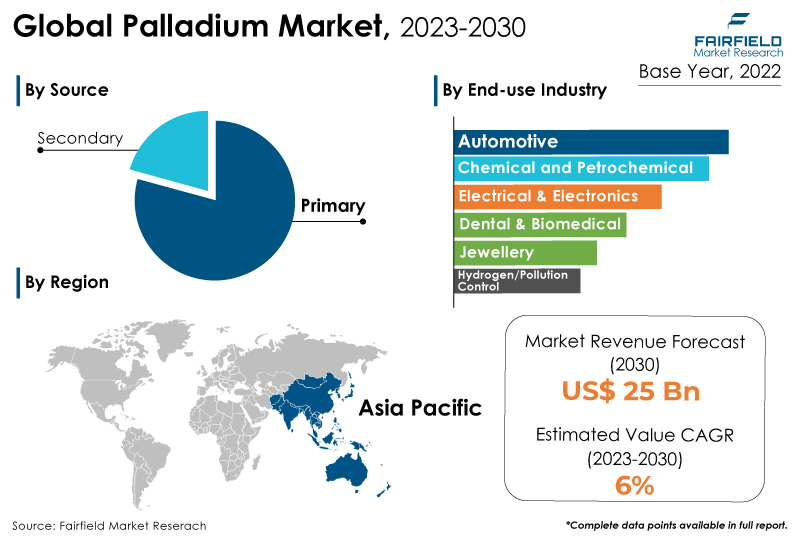
Gasoline catalytic converter demand is the main driver. Each converter uses between 3 and 5 grams of palladium in North American midsize sedans. That amount varies by engine size, emission standard, and catalyst formulation. Toyota and Honda shifted toward lower palladium content in 2019, cutting usage to nearly 2 grams per unit. GM held steady at nearly 4 grams. That difference shows up in annual demand forecasts, not quarterly prices. Industrial applications use palladium in capacitors, multilayer ceramic substrates, and hydrogen purification membranes. That market is small: about 8 percent of annual demand. It also trades at a consistent 5 to 10 percent premium over catalyst-grade metal. Fabricators in South Korea and Germany prefer that grade because the purity requirements for electronics exceed automotive standards. Palladium substitution is a real risk, but it plays out slowly. Refiners in South Africa and Russia have been blending platinum into catalysts since 2018. That move cuts demand by nearly 5 percent annually. The technology shows up in OEM specifications, not spot prices. Every claim about EV adoption sends palladium selling pressure through the market, even though the actual displacement of demand plays out over a decade.
The Supply Side And Production Risks
Mined palladium comes primarily from the Bushveld Complex in South Africa and the Norilsk district in Russia. Those two regions produce about 70 percent of global output. That concentration means any labor strike or power outage shows up in delivery schedules within weeks. I've seen South African miners strike for 14 days in 2014, cutting output by nearly 12 percent. Prices ran 30 percent higher before new supply came online. Recycled palladium provides about 25 percent of annual supply. That material comes from spent catalysts and industrial scrap. The recovery rate is nearly 85 percent for automotive catalysts. Jewelry scrap yields nearly 60 percent because the palladium gets alloyed with other metals. Refiners in Germany and Japan prefer the automotive stream because the purity requirements exceed industrial standards.
What I've Learned Tracking This Metal For Years
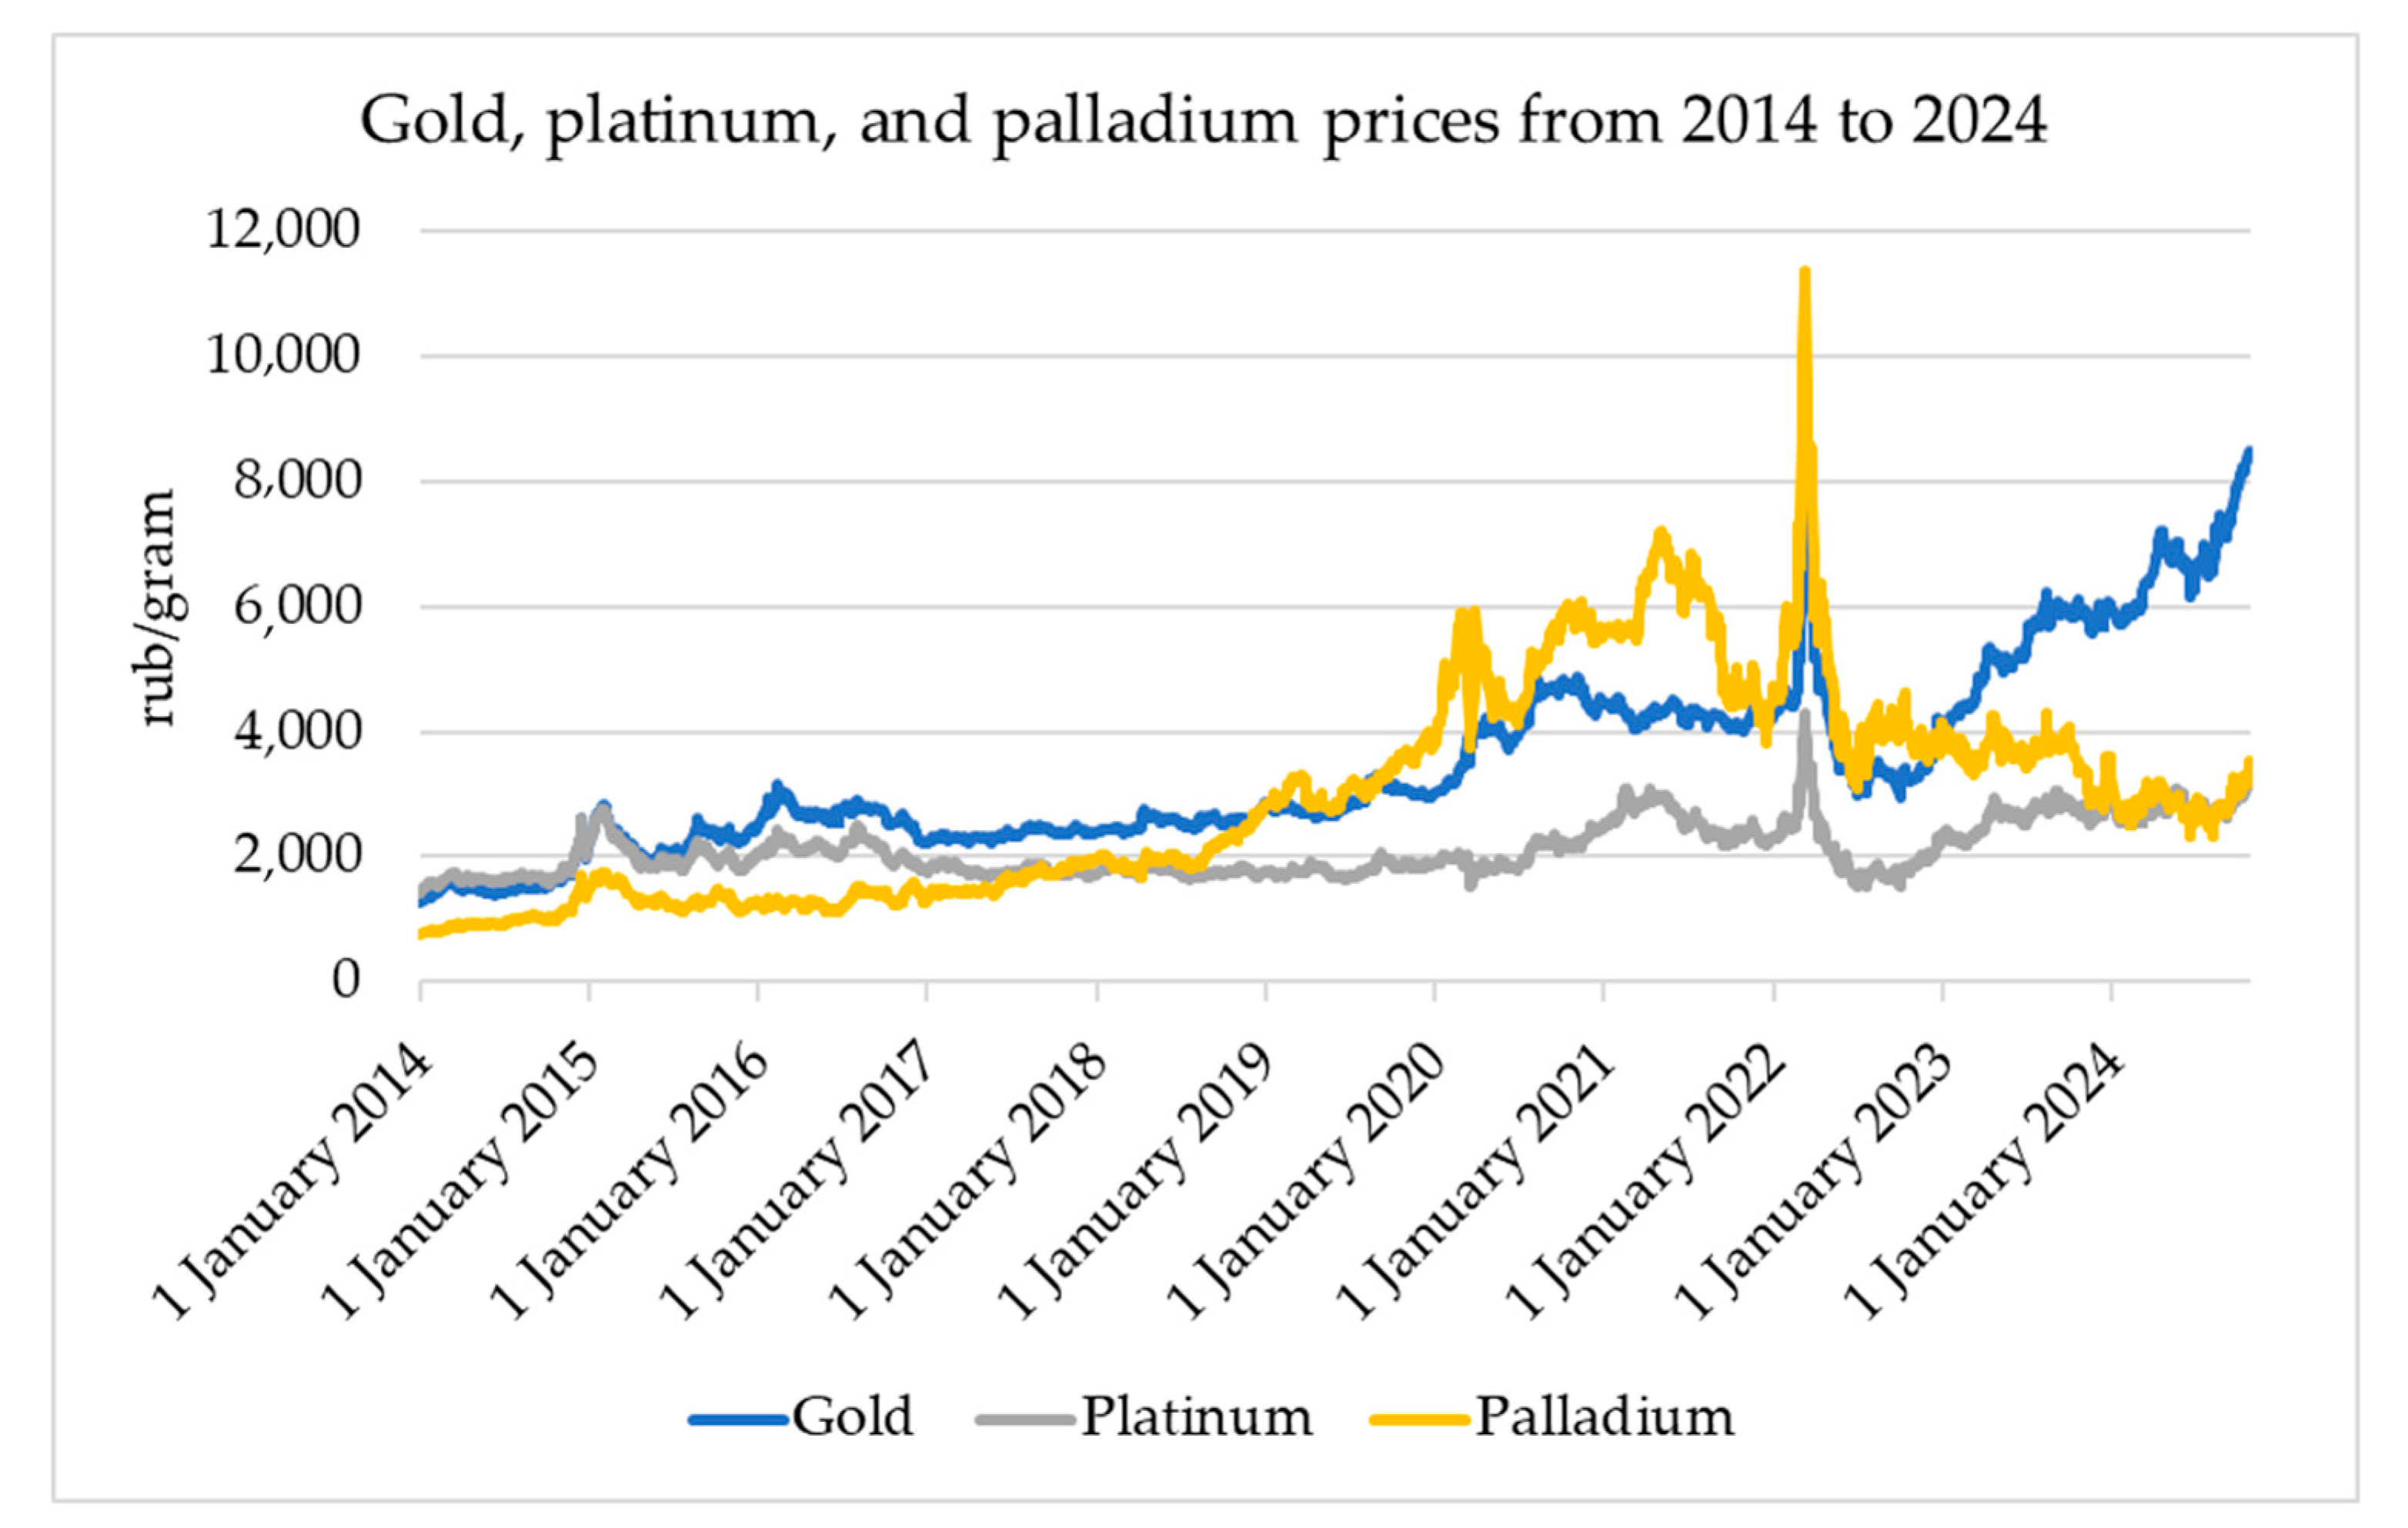
Palladium does not behave like gold. It does not respond to interest rate cuts the same way. It does not hold value during deflation. It responds to industrial demand, emissions regulation, and supply concentration. Those three drivers create a price range that shifts faster than most hedging models account for. I've watched traders get burned by assuming palladium would follow platinum. That correlation breaks down during supply disruptions. In 2021, platinum traded below 900 dollars while palladium stayed above 2600. The spread reached nearly 1700 dollars per ounce. That gap is historically wide. No model predicted it. The market priced in Russian supply risk before anyone else did. The physical market has bottlenecks the futures market ignores. Delivery requires approved refiners. Johnson Matthey and Heraeus control nearly 60 percent of refined supply. Smaller players in Tokyo and Switzerland add another 15 percent. The rest comes from Russian plants that faced export restrictions. That concentration means any sanction or logistics issue shows up in premiums, not just spot prices.
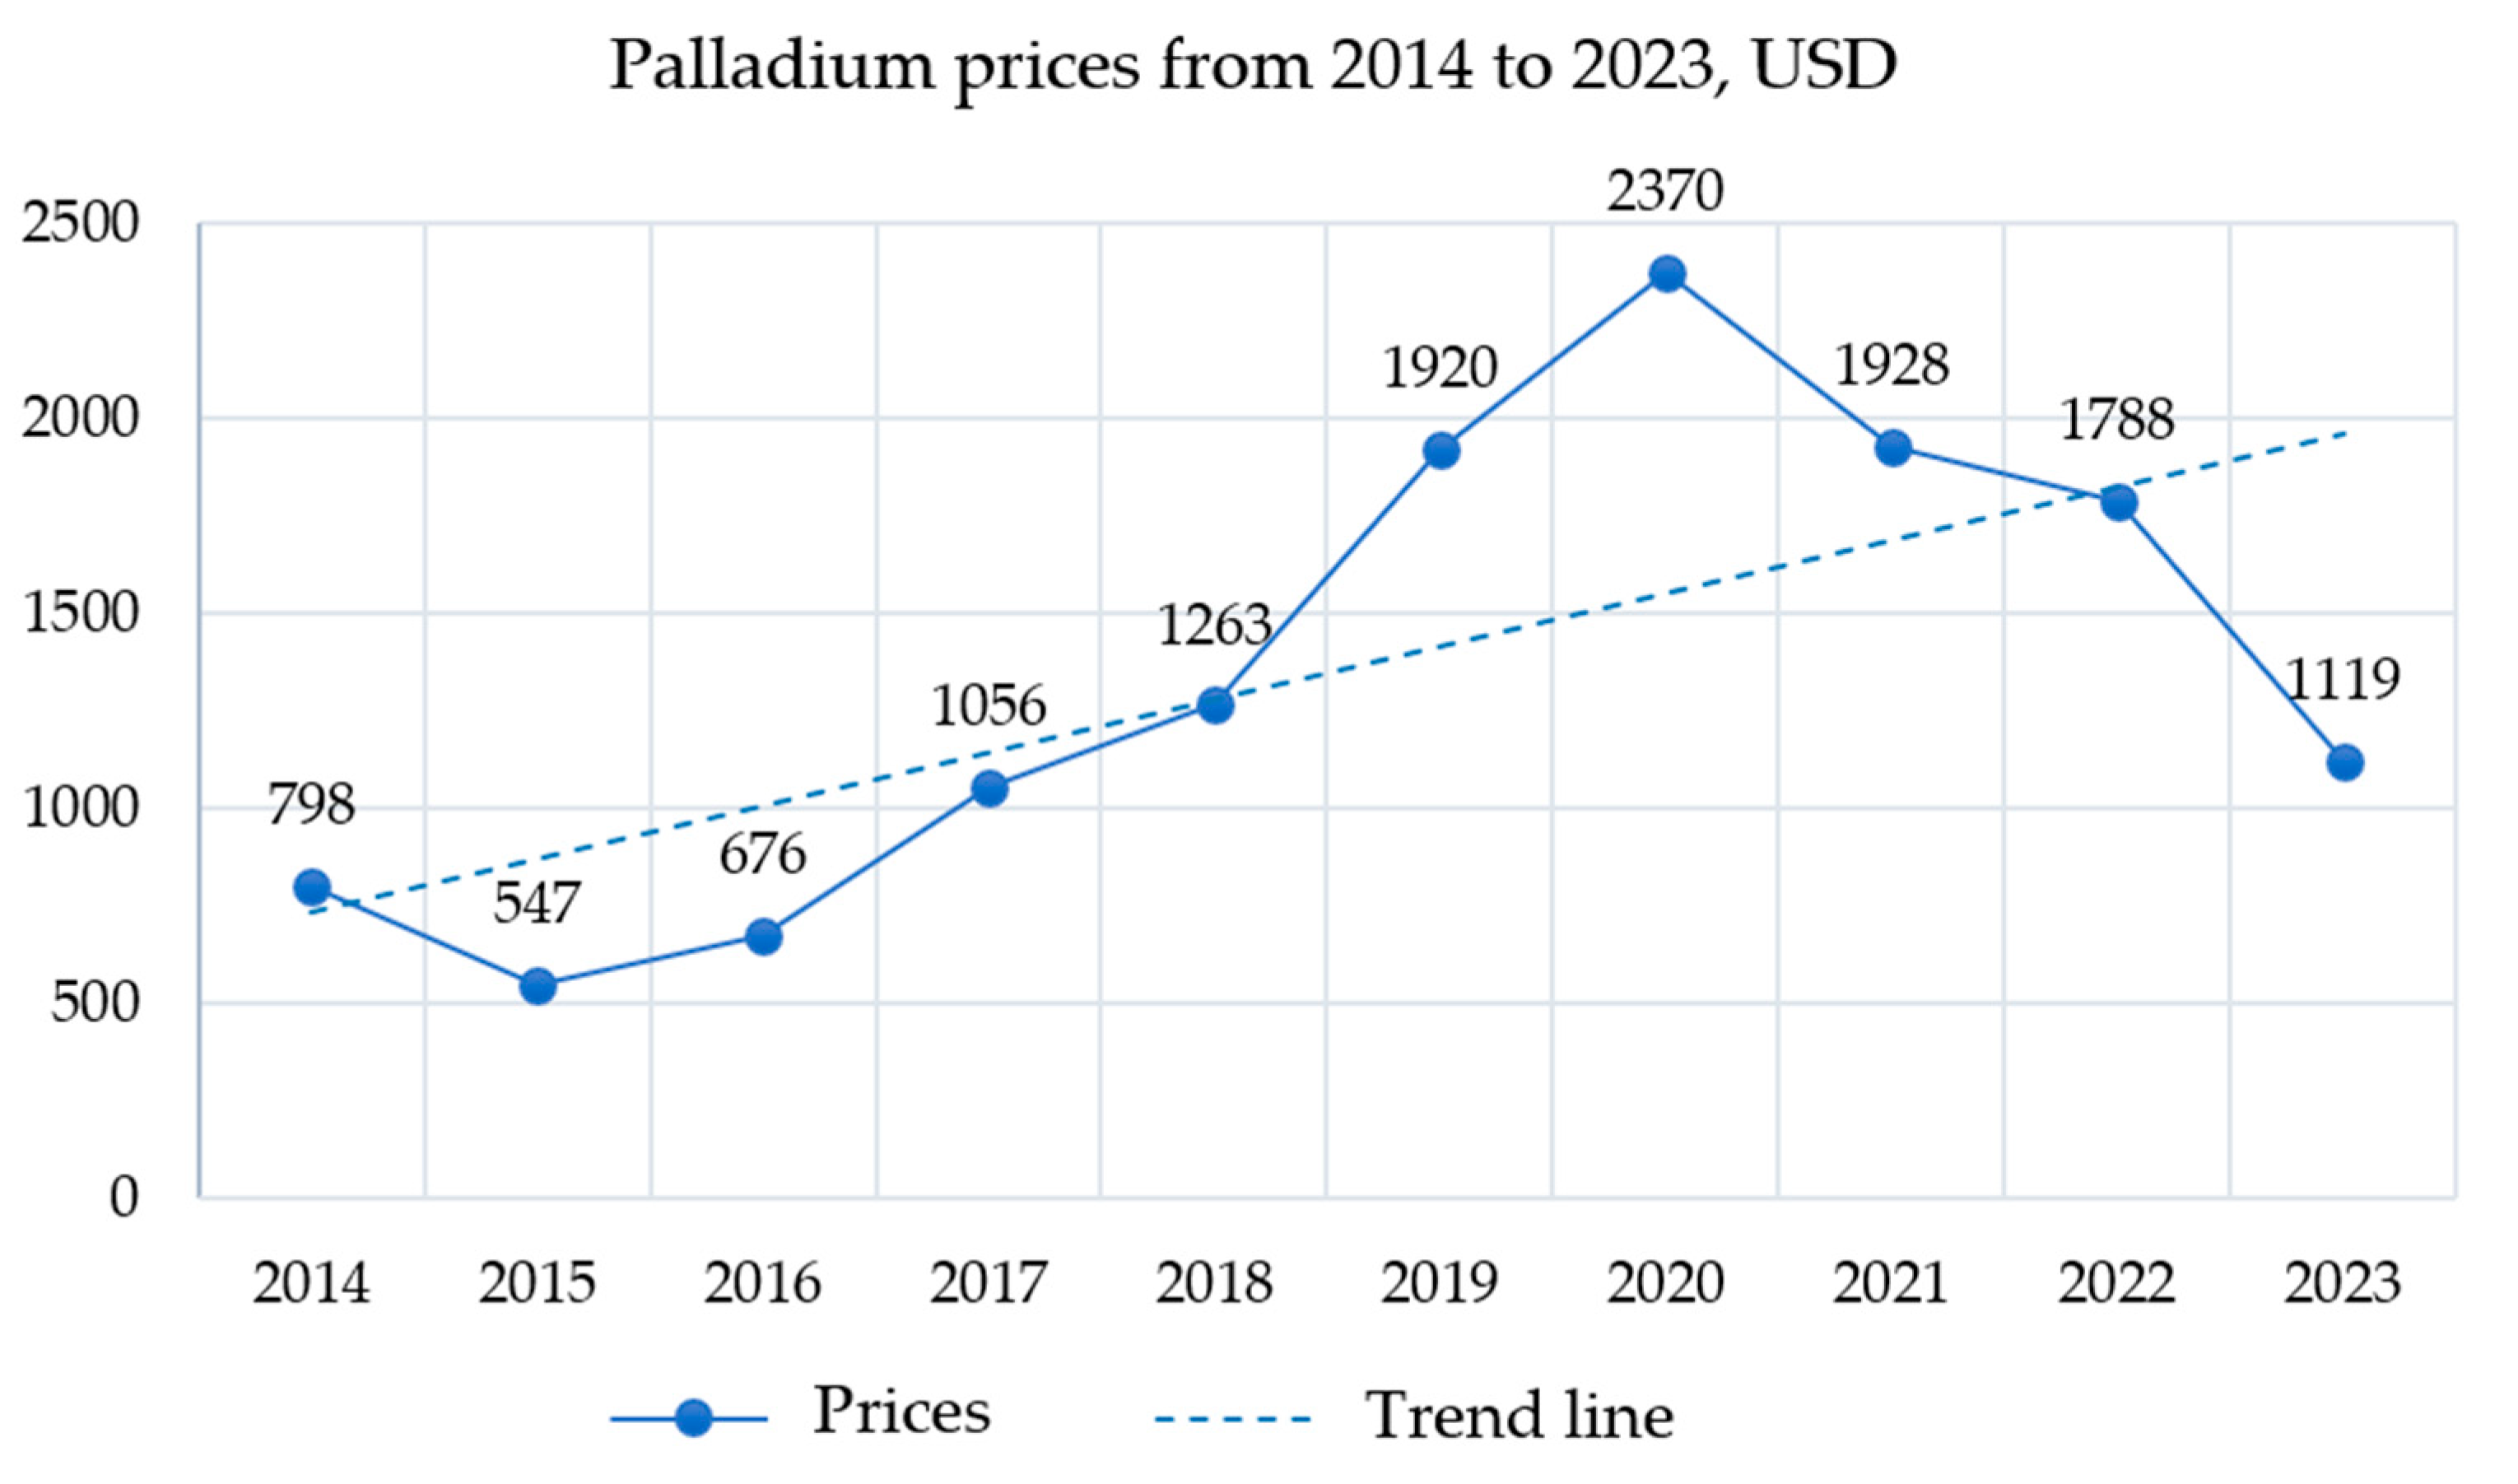
I recommend tracking COMEX registered inventory, LBMA delivered stock, and South African production data. Those three numbers explain 80 percent of price moves. Emissions regulation announcements explain another 15 percent. The remaining 5 percent comes from currency fluctuations and speculative positioning. Palladium has worked for me as a portfolio diversifier. It has also cost me money when I ignored the demand side. The metal pays no yield. It carries storage costs of nearly 0.5 percent annually. It trades at a premium during supply disruptions and a discount during demand slumps. Those two states explain most of the volatility. If you are new to this metal, start with a small position in physical bars from an approved dealer. Avoid leveraged products until you understand the delivery mechanics. The futures market is liquid, but physical settlement is not automatic. I learned that in 2020 when I sold a futures contract and could not find delivery at the settlement price. The physical market knew what it wanted to charge.