Getting Started With Palladium As An Investment Vehicle
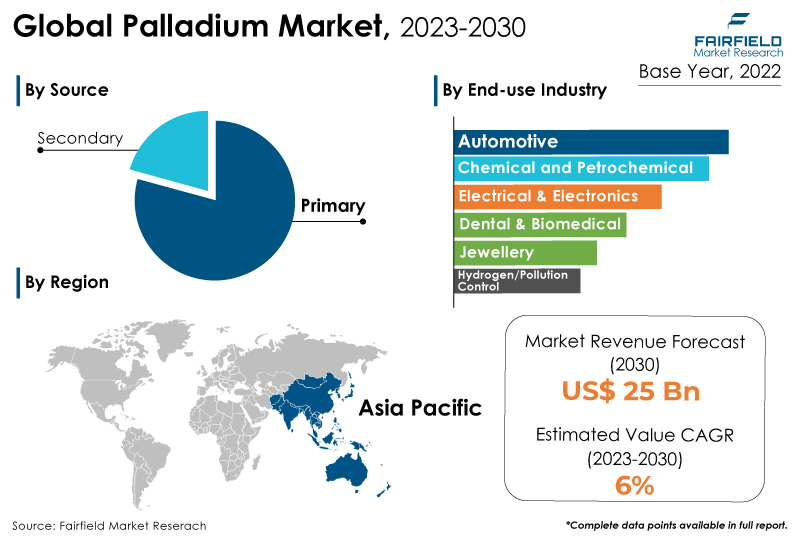
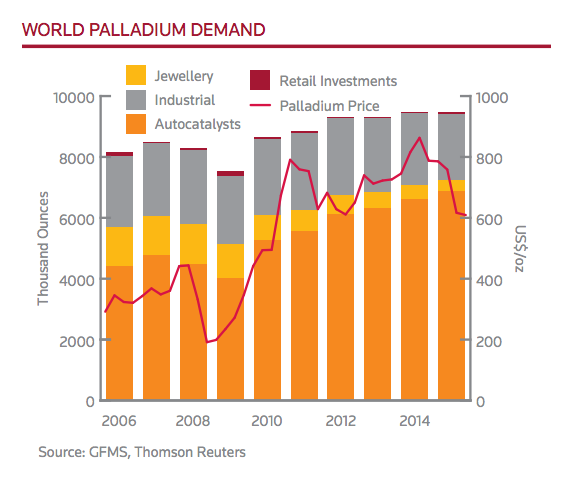
Palladium sits in an awkward position in the commodity markets. It is one of the rarer precious metals, with global mine supply hovering around 210 to 220 tonnes annually, while the bulk of that comes from just two countries: South Africa and Russia. That geographic concentration matters more than most people realise when they look at price charts. I spent several years tracking base and precious metals for a mid-sized commodity desk, and palladium was always the one that kept people up at night. Not because it is complicated, but because its demand profile is dangerously narrow. Roughly 80 to 85 percent of palladium demand goes into catalytic converters for gasoline-powered vehicles. When automotive production shifts, palladium feels it immediately.
The Palladium Item Shaping Value Industry And Investment In The Modern World
The modern palladium market operates on thin physical margins. Stock levels outside of China have been in a structural deficit for most of the last decade. The London Bullion Market Association and Metal Focus report consistent annual deficits through 2024 and into 2025, and yet the price did not simply go straight up. That is because palladium trades on expectations about engine technology transitions as much as it trades on current supply and demand. If you are looking to gain exposure, there are several routes. Physical bars and coins are available through reputable dealers, though the premium over spot can be steep, often running 4 to 8 percent above the underlying price depending on the form factor. Palladium ETFs such as the Invesco Physical Palladium ETP offer a simpler entry point with lower transaction costs, though you are exposed to counterparty risk with the custodian structure. Futures contracts on the COMEX provide the most liquidity and the tightest spreads, but they require a margin account and a tolerance for roll costs if you hold positions long-term. Mining equities give leveraged exposure to palladium prices without the direct commodity risk, though company-specific problems can detach your return from the metal's performance entirely. One thing most beginners miss is that palladium and platinum often move in opposite directions over certain timeframes because of their substitution relationship in catalytic converters. When palladium spikes, automakers switch to platinum where possible. This happened noticeably in 2019 and again in 2022. If you are only watching the palladium chart in isolation, you will not see that hedge playing out in real time. I learned this the hard way during the early part of the 2021 rally. I had gone long on physical palladium bars at roughly $2,700 an ounce, convinced the deficit would keep pushing prices higher. What I did not account for was the pace at which OEMs would accelerate platinum substitution in their newer engine designs. By the time palladium corrected sharply back below $2,000, I had already taken a meaningful loss on the physical position. I learned to monitor the palladium-platinum spread alongside the spot price rather than treating them as separate markets.
The hydrogen economy adds another variable that is easy to underestimate. Palladium has legitimate applications in fuel cell technology, particularly in proton exchange membrane systems. Production volumes today are small compared to automotive demand, but major automakers and industrial gas companies are funding pilot programs at scale. If hydrogen fuel cells gain meaningful adoption in heavy transport, palladium demand could receive a structural boost that current models do not fully capture. On the flip side, if solid oxide fuel cells or other catalyst-free designs win out, that potential demand disappears entirely. The uncertainty here is not something you can hedge with a simple long position. Supply risk is another area where the data looks different depending on which report you read. South Africa's platinum group metal mines are deep-level operations with serious energy and labour issues. Power outages from Eskom have caused intermittent production disruptions that cut into quarterly supply estimates. Russian mining and refining faces geopolitical risk that is impossible to price into a standard model. Sanctions regimes, export restrictions, and logistics complications mean that actual delivered quantities from Russian producers can diverge significantly from reported production figures. I worked through a period where a major palladium supplier faced unexpected export delays that lasted several months. The spot market barely moved because of existing stockpile buffers, but the forward curve shifted noticeably, and anyone with physical delivery contracts found themselves in a difficult position negotiating alternatives. For practical purposes, if you want to build a position, start by deciding what kind of exposure you actually want. Direct physical ownership gives you tangibility but carries storage and authentication costs. ETFs and futures give you liquidity but introduce structural risks that do not exist with metal in your hand. Mining stocks give you leverage but expose you to operational and governance risks that have nothing to do with palladium prices. A balanced approach used by several institutional portfolios I have seen involves a core position in a palladium ETP supplemented by selective futures rolls and a small allocation to primary PGM producers with significant palladium by-product exposure.
Get the Full Details
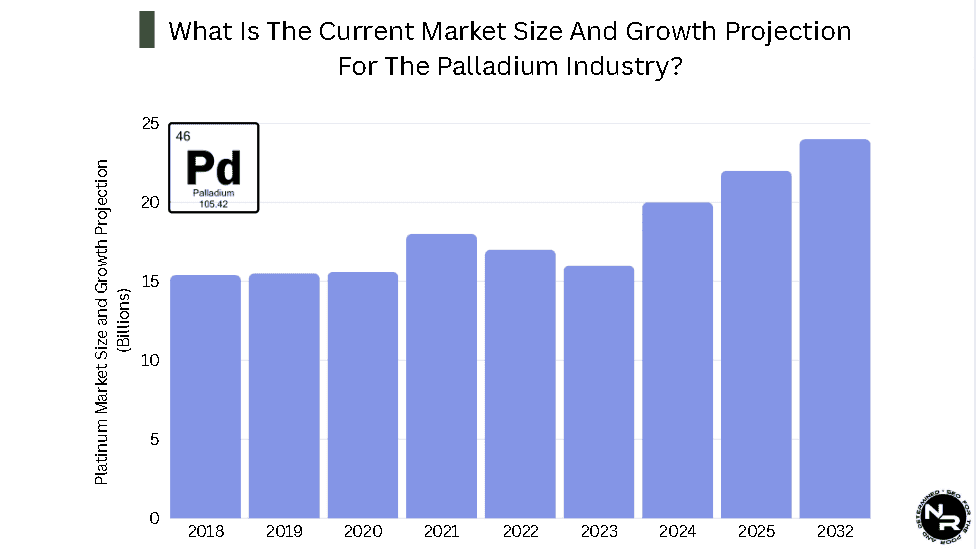
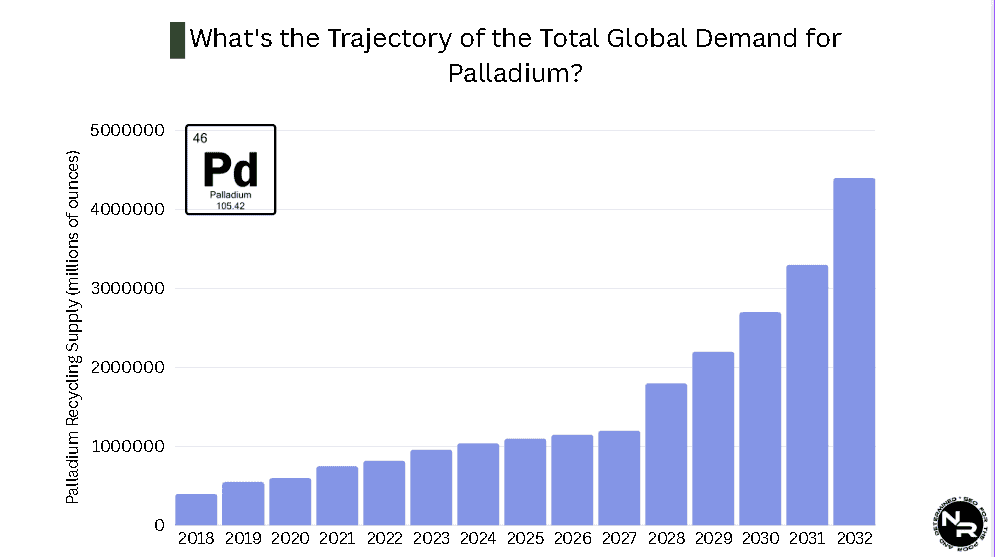
The key thing to watch going forward is not just the deficit numbers but the rate of change in those numbers. China's automotive sector remains the single largest demand driver, and any sustained shift toward electric vehicles there will compress palladium demand faster than new supply sources can develop. Recycling from spent catalytic converters currently offsets a meaningful portion of mine supply, but that stream is also tied to vehicle fleet age and turnover rates. If the average age of cars on the road increases, recycling volumes drop and the deficit widens. If new car sales slow, both demand and recycling slow, and the picture becomes muddier. Downloadable resources from the London Platinum and Palladium Market and the USGS Mineral Commodity Summaries provide the raw data you need to run your own models. The industry reports are free and updated quarterly. The data is not always perfectly harmonised between sources, so I recommend cross-referencing at least two reports before making a positioning decision based on supply figures.