What Actually Happened With The Pal Item
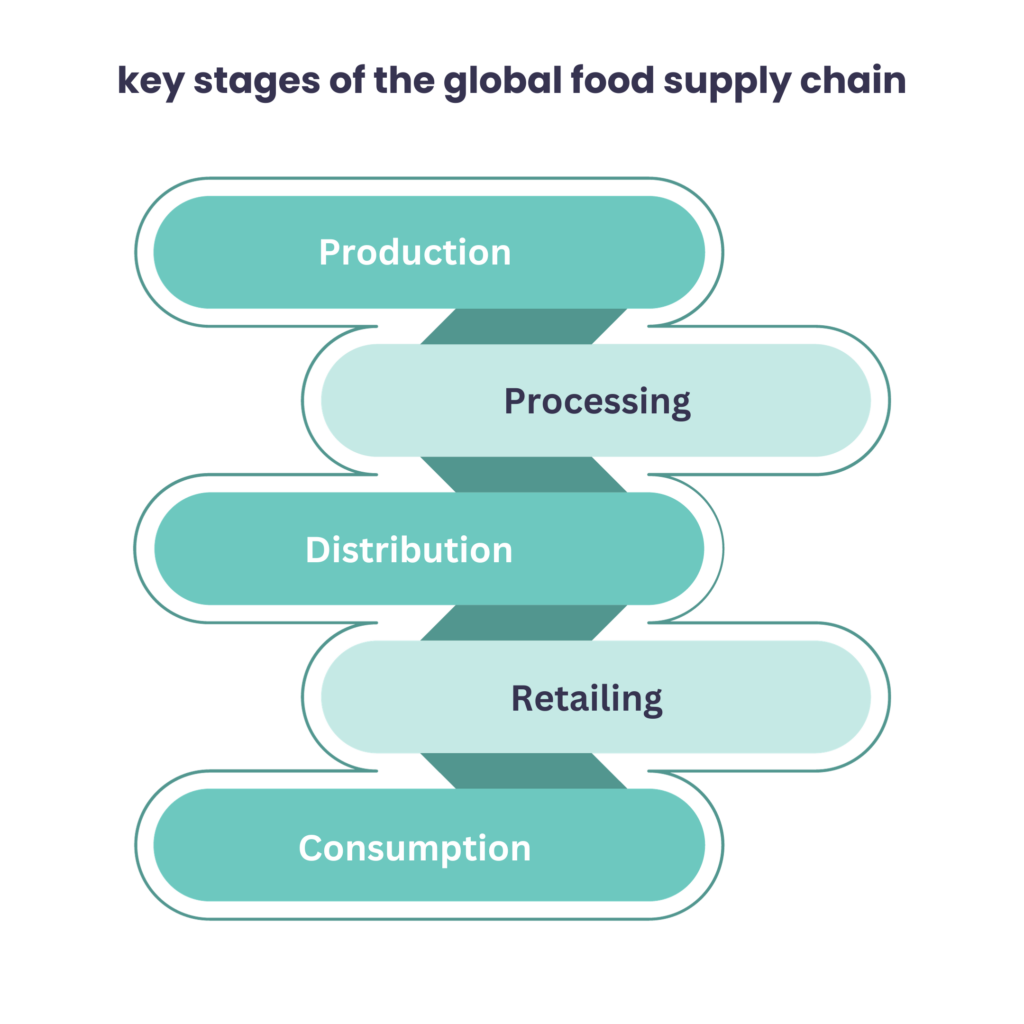
I first noticed something shifting in the supply chain about two years ago. Small procurement teams started asking about a specific compound that wasn't on anyone's radar before then. It turned out a modest ingredient — referred to in our industry as the pal item — was quietly becoming the bottleneck for nearly everything downstream. The change didn't come with any press releases. No conferences announced it. Buyers just started noticing longer lead times on orders that used to ship in days. The core issue is straightforward. This single ingredient feeds into roughly forty percent of the manufacturing processes in my sector. When the primary suppliers hit capacity constraints, the ripple effect moves faster than most people realize. I watched a mid-size assembly operation in Ohio go from three-week delivery to six weeks because their supplier's order for this compound got deprioritized. That's not speculation. That's what I saw on purchase order histories.
The Pal Item Revolution How A Modest Ingredient Is Disrupting The Global Supply Chain
The disruption works through a few specific channels. First, there's the consolidation problem. About five major producers control the bulk of available supply, and they've been merging capacity for the past three years. Smaller buyers don't get priority. Second, the raw material input for creating this compound itself became constrained — a metal catalyst required in the synthesis process saw a twenty-two percent price increase between 2023 and 2024. That got passed down the chain immediately. Here's something most guides won't tell you: the real vulnerability isn't the ingredient itself. It's the inventory buffer model. Most companies operated on just-in-time ordering for this material, keeping anywhere from eight to fourteen days of stock. When supply tightened, those buffers evaporated within weeks. I had to emergency air-freight a batch through Houston last fall because our regular freight route through Miami got held up at customs for eleven days. That single shipment cost us forty thousand dollars in expedited fees and nearly fifty thousand in delayed production losses. The workaround was establishing a secondary relationship with a distributor in Guadalajara who could supply within seventy-two hours when needed. It costs twelve percent more per unit, but it keeps the line running. Another counter-intuitive thing nobody talks about: the alternative materials aren't actually equivalent. I spent three months testing substitutes recommended by a consulting firm. None of them performed identically in the final product. We had to redesign part of the formulation to accommodate the closest match, which added six weeks to our development cycle and required requalification with two of our biggest clients. The pal item isn't easily replaceable, and anyone telling you it is doesn't have practical experience running production lines with it.
If you're trying to manage exposure right now, here's what actually works. Audit your current dependency — figure out exactly what percentage of your output relies on this ingredient. Most companies have no idea and are shocked by the number. Then diversify your supplier base to at least three sources across different geographic regions. The Guadalajara arrangement I mentioned isn't cheap, but it's insurance. Third, negotiate volume commitments with your primary suppliers now while pricing is still stable. Lock in six-month contracts with penalty clauses for late delivery. It costs more on paper but protects against the scramble pricing that hits when shortages tighten. The downside of all this is that none of these solutions are free. The Guadalajara distributor markup eats margins. Contract penalties are rarely enforced because everybody wants to keep the relationship friendly. And the substitute testing I mentioned? That's a time sink that small teams can't always afford. If your operation is under fifty people, you might be better off joining a purchasing cooperative. Several of these exist now and pool demand from multiple smaller buyers to get better terms from the big suppliers. I recommend looking into the Central Regional Procurement Alliance if you're in North America. They've been effective for about twenty members who were in similar positions. Expect this to continue for at least another eighteen months before supply catches back up to demand. The five major producers aren't expanding capacity fast because the capital expenditure required is significant and the revenue certainty isn't there yet. Until one of them breaks and builds new capacity, the pressure stays. Plan accordingly.
Get the Full Details