OTC Markets Explained For People Who Actually Trade Them
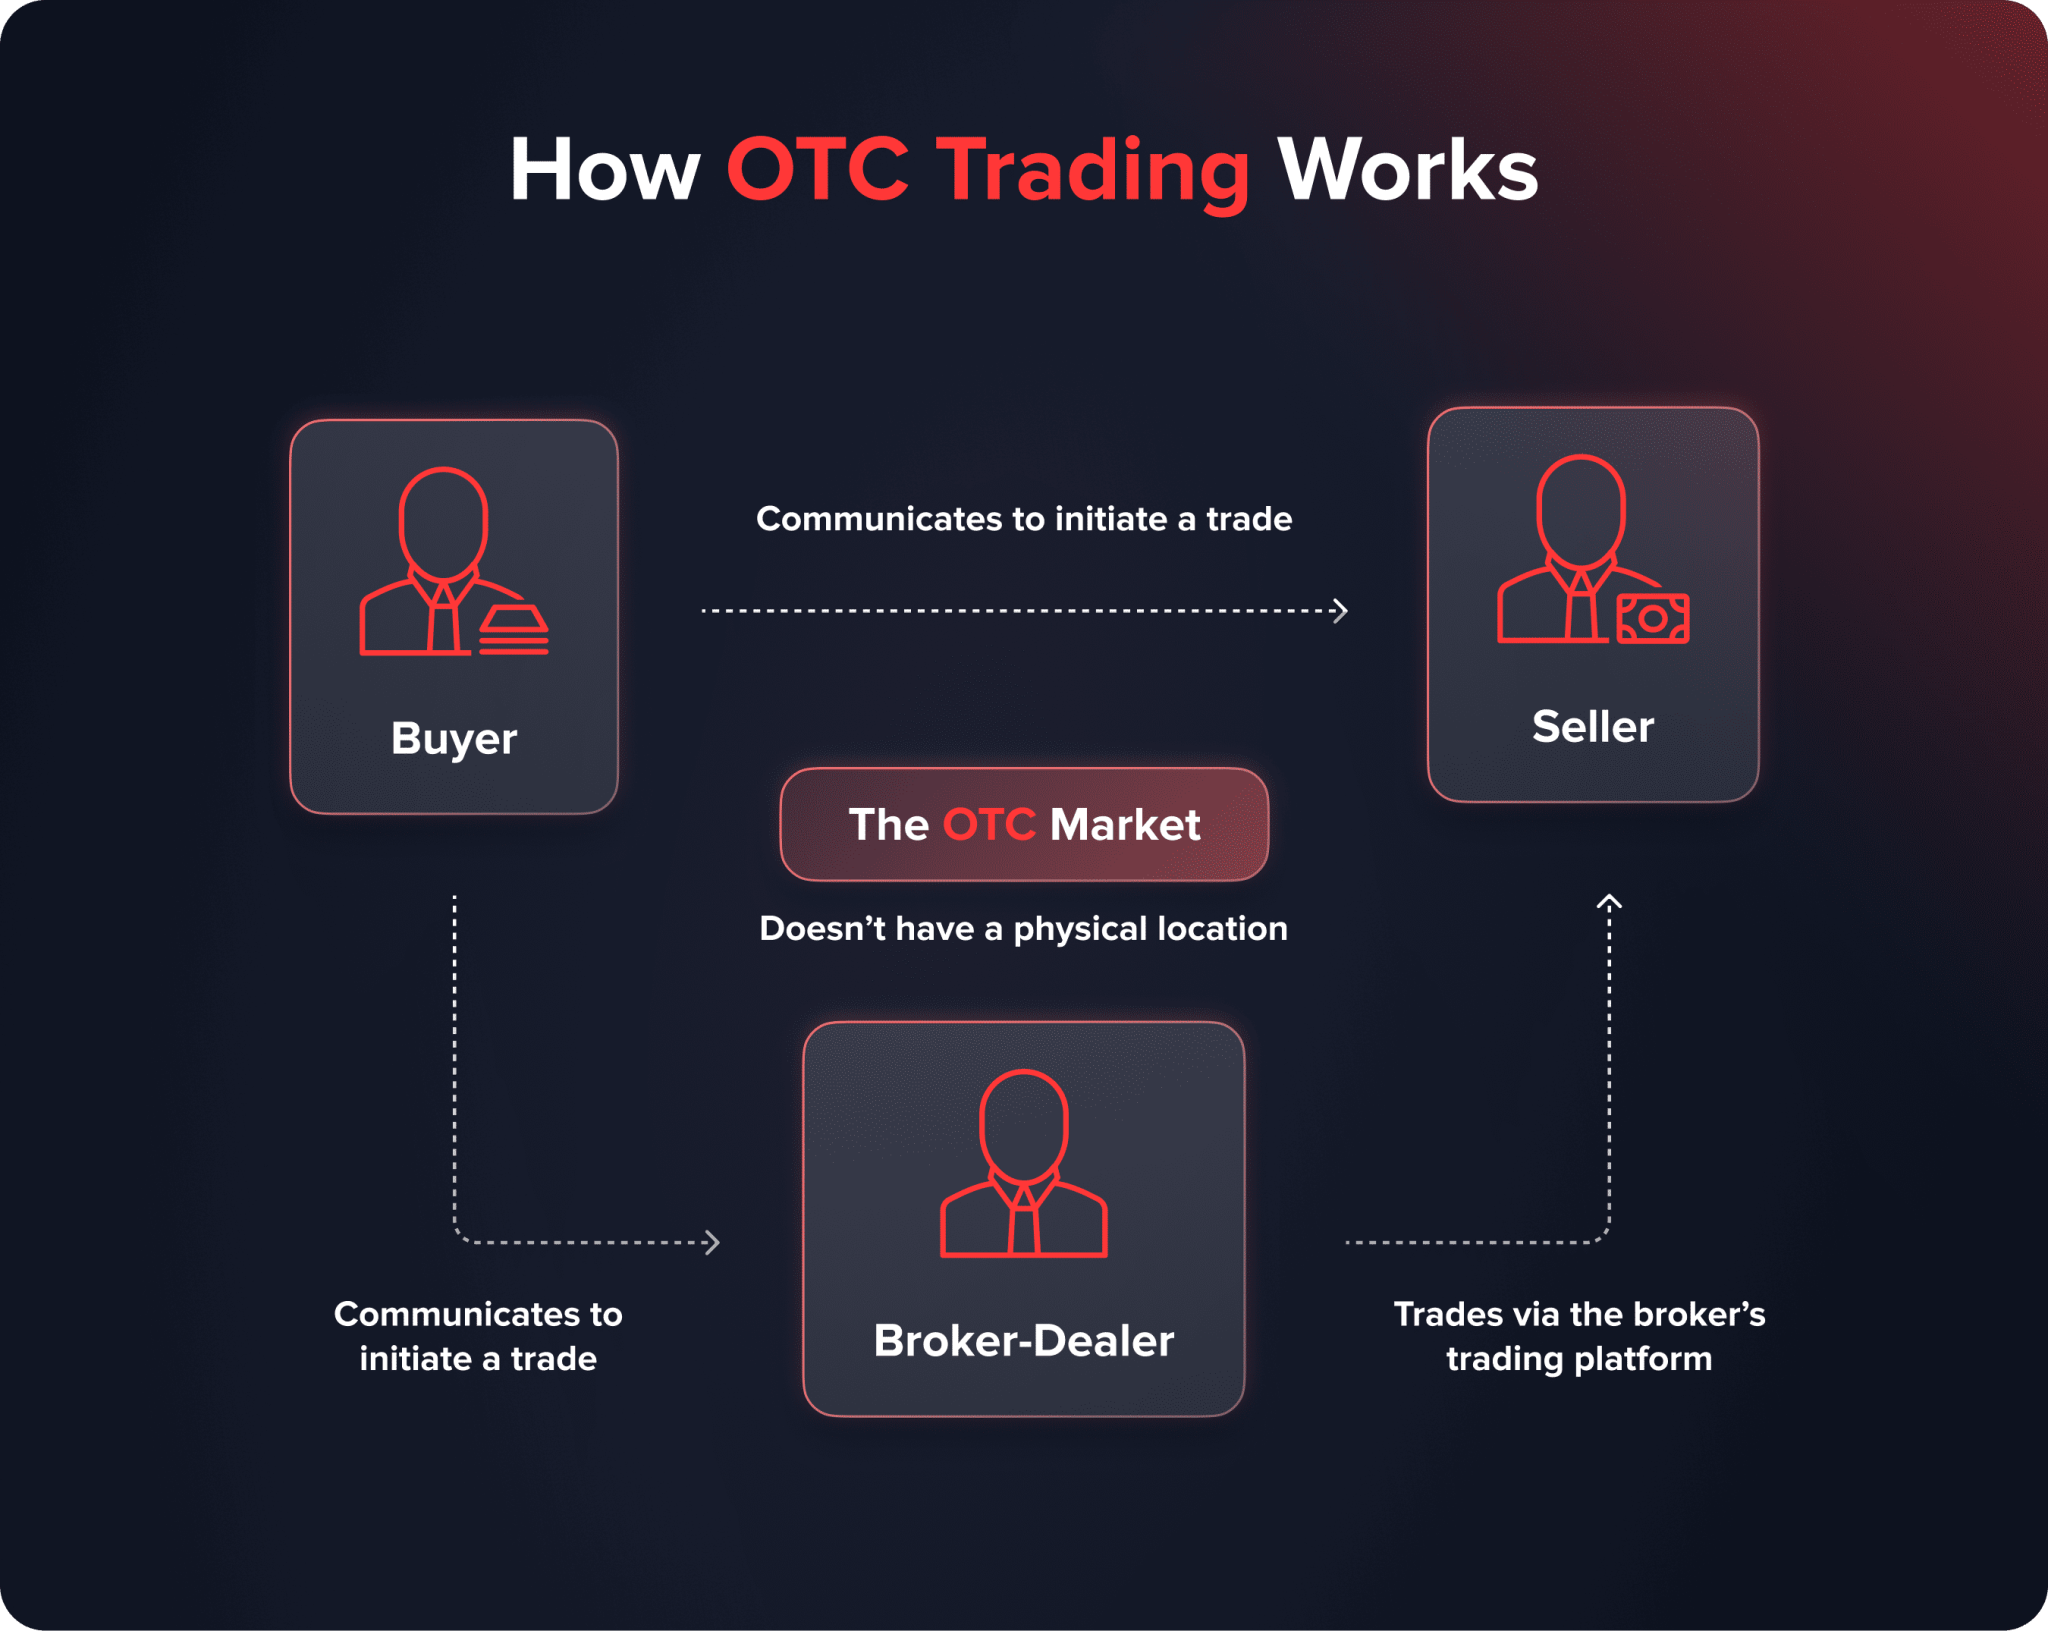
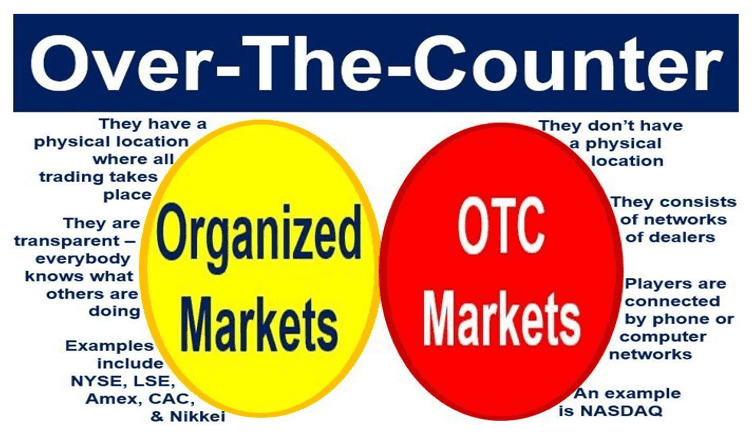
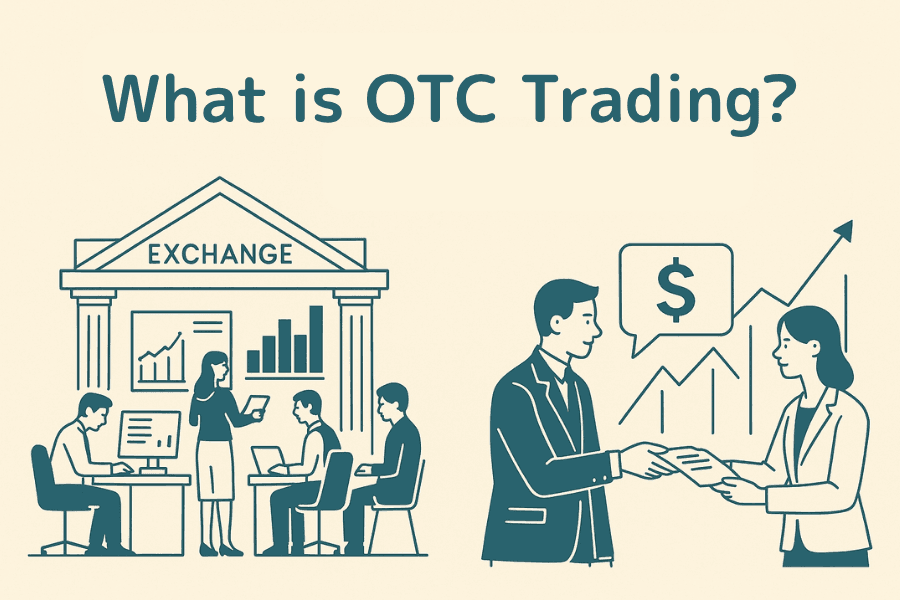
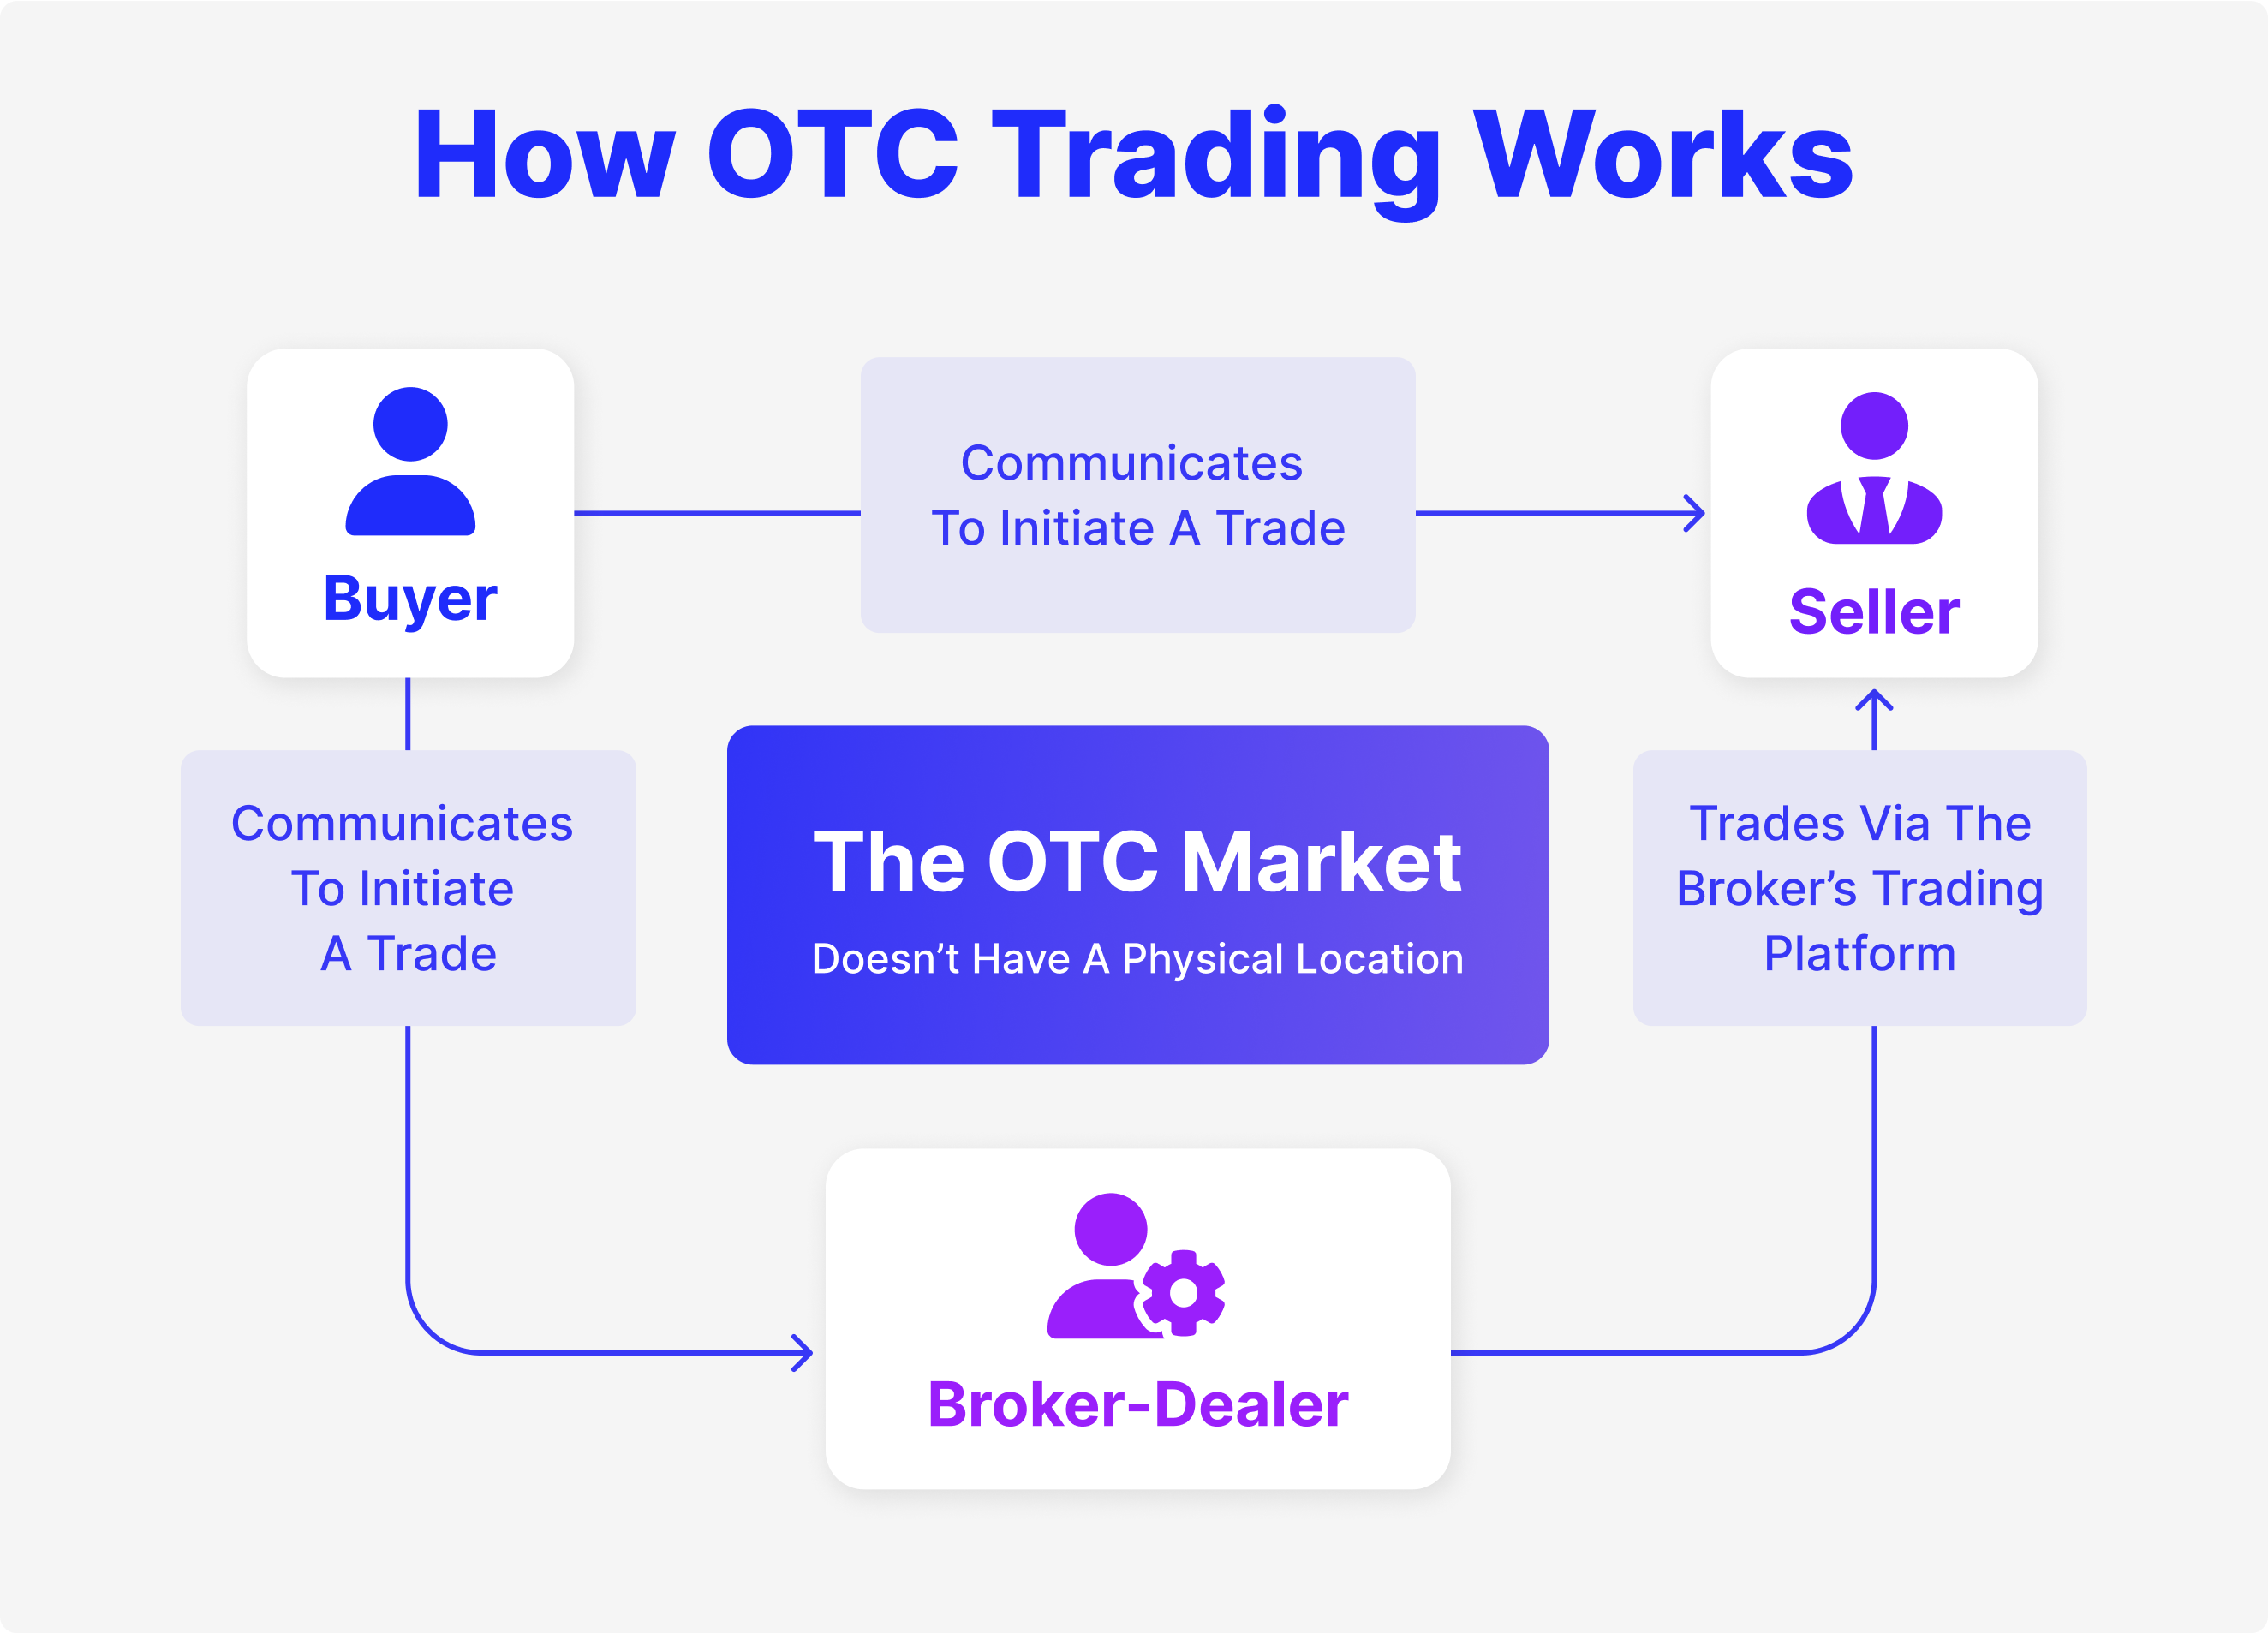
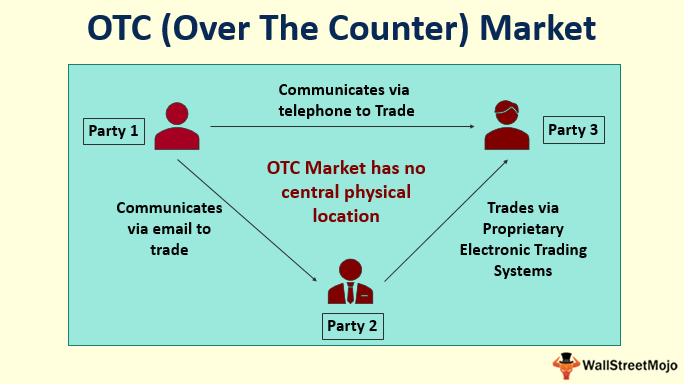
OTC stands for over-the-counter, and it refers to securities that trade outside of formal exchanges like the NYSE or Nasdaq. The mechanics are simpler than most people assume, which is partly why the sector has accumulated so many dubious reputations over the years. When a stock is listed on the OTC Markets Group, it operates through a dealer network rather than an auction-based exchange. Market makers post bids and offers, and trades execute between those quotes. That structure creates different liquidity dynamics than you would see on a major exchange. Spread can be wide, especially on lower-tier symbols. Volume can evaporate quickly during volatile periods. These are not theoretical problems — I have watched positions get stuck in names trading under a thousand shares per day without much warning. The classification system matters more than most retail traders realize. OTC Markets operates three main tiers: OTCQX, OTCQB, and the Pink Sheets. Each tier has different disclosure and financial requirements. Companies on OTCQX typically meet the highest standards and may include well-known international firms. OTCQB is aimed at development-stage companies that still provide some level of financial reporting. Pink Sheets cover everything else, including companies with minimal or no disclosures.
I ran into a specific edge-case a few years back that illustrates how messy this space can get. A company I was tracking filed annual reports but had no independent auditor review, and their financials showed revenue but essentially zero cash on hand. The stock was quoted on the Pink tier with a daily volume of roughly eight hundred shares. The bid-ask spread sat at twelve percent. I needed to exit a small position quickly, and my usual limit-order approach would have taken days to fill at a reasonable price. The workaround was to split the order into three smaller chunks spaced across different sessions, targeting the ask side with market orders only when the spread tightened below eight percent. It added about forty-five minutes to the process but saved roughly seven percent in slippage compared to dumping the whole position at once. That kind of tactical patience is often what separates a manageable loss from an unnecessary one in thin OTC names. One counter-intuitive point that most guides miss is that higher listing tier does not automatically mean better liquidity or tighter spreads. I have seen OTCQX names with spreads wider than certain Pink tier stocks simply because the holder base was too concentrated. The tier tells you about disclosure quality, not trading activity. You need to verify daily volume, bid-ask spread, and market maker participation independently before assuming a listing tier guarantees reasonable execution. Another nuance that people overlook involves the role of the transfer agent and the symbol designation. A trailing W on an OTC symbol usually means the company is undergoing a reorganization or has pending corporate actions. A trailing PO denotes a penny offer. These designations change rapidly and can shift your risk profile overnight. I once traded a name with a standard symbol into a W-suffix stock after an unexpected restructuring announcement. The liquidity vanished within two trading sessions while the headline was still circulating. Checking the symbol suffixes and any recent corporate action notices should be a standard step, not an optional one.
The regulatory environment around OTC securities deserves a direct mention. These markets do not carry the same investor protection mechanisms as exchange-listed equities. There is no central limit order book, no circuit breakers, and no uniform reporting cadence for every participant. Fraud and manipulation cases do occur here, though the overall incidence rate is roughly proportional to the number of participants and the lack of oversight. If you are evaluating a name with no recent filings, limited coverage, and a micro-cap float, treat it as a higher-risk allocation regardless of any positive narrative. For practical trading, I recommend starting with names on OTCQX or established OTCQB listings that show consistent daily volume above ten thousand shares and spreads under five percent. Avoid chasing low-volume Pink tier names with aggressive headline-driven momentum. The execution quality will bite you. Use limit orders unless you need immediate fills, and even then, split your orders rather than risking a wide-spread hit on a single market order. If your goal is exposure to early-stage companies without the operational friction of thin OTC names, consider alternatives like micro-cap ETFs or exchange-listed small-cap vehicles. They carry different risks, but the liquidity and disclosure environments are materially better for most retail traders. OTC markets can work if you respect the structure and adjust your tactics accordingly, but they are not a shortcut around due diligence.
Get the Full Details