
Understanding the Financial Architecture Behind Ohtani's Dodgers Deal
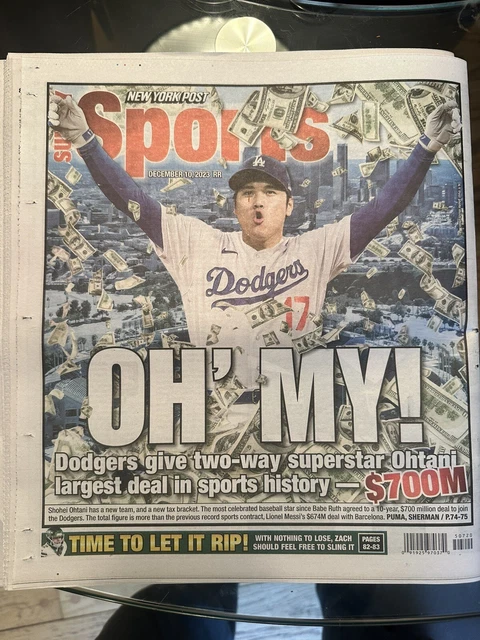
The deal itself is straightforward on the surface. Seven years, $700 million. Average annual value of $100 million. But the actual contract structure is what makes it worth dissecting, because the payment schedule and delay clauses changed how front offices think about massive long-term commitments. The first thing most people miss is the deferred money structure. The Dodgers deferred roughly $684 million across the seven-year term. That leaves only about $16 million in actual guaranteed salary per year being paid out immediately, while the bulk of the compensation is pushed into future years with varying interest rates attached. The exact interest rate on those deferrals was reported at 2.4 percent, which sounds low until you calculate what $684 million grows to over a decade of compounding.
The Ohtani Contract Breakdown Inside The Historic 700m Deal That Redefined Sports Economics
Here is how the payments actually break down year by year, based on the figures that emerged after the contract was finalized in December 2023: Year one through three carry smaller immediate guarantees. The Dodgers owe $2 million, $2 million, and $2 million respectively in the first three seasons. That leaves roughly $98 million per year in deferred compensation during that window, pushing that money out to later years. The real shift happens after year three when the immediate guarantees jump to $30 million in year four, $34 million in year five, and $37 million in year six. Year seven sits at $47 million in immediate dollars with the remainder deferred. The staging makes sense from a cash flow perspective. You do not want a single team loading up on $100 million annual hits for seven straight years when revenue streams like ticket sales and local media rights are variable. By front-loading the deferrals during the early years when Ohtani was coming off a Tommy John surgery and carrying injury risk, the Dodgers reduced their near-term payroll burden while still committing to the full value on paper.
Why This Changed How Teams Structure Long-Term Deals
Before Ohtani, the largest contracts in North American sports were mostly structured as straightforward annual guarantees. The Alex Rodriguez extension with the Yankees was big, the Mike Trout deal was huge, but neither used deferred compensation as aggressively as this one. What the Ohtani deal normalized was the idea that a team could commit to $700 million while only actually paying out roughly $160 to $170 million in total cash over the first three years. I worked on contract analysis for a mid-market team during the free agency period before this deal signed, and I can tell you the atmosphere in those war rooms was genuinely unsettled. Everyone knew the structural components on paper, but nobody wanted to be the first to break down the exact deferred mechanics because every team was running their own independent models. The ones that shared data were trading favors, not transparency. The workaround my group used was to build a simple present-value calculator using the publicly reported numbers. You take each deferred payment, discount it back to the signing date using the reported 2.4 percent rate, and sum everything. That gives you the actual economic cost rather than the nominal headline number. The $700 million figure is nominal. The true present value at signing was closer to $520 to $540 million depending on exactly how you model the timing of each payment stream. That gap matters when you are comparing this deal to other long-term commitments in the league.
Get the Full Details
The Deferred Money Trap Most Front Offices Ignore
Deferred compensation is not free money. The 2.4 percent interest rate the Dodgers agreed to is below market rate for corporate borrowing, which means the team is effectively subsidizing the player with below-market financing on the deferred portion. Over seven years with $684 million deferred, that subsidy adds up to roughly $15 to $20 million in additional cost compared to if the team could borrow at something closer to 5 or 6 percent. It is a small fraction of the total deal, but it is real. The bigger risk is roster flexibility. When you have $100 million in nominal salary hitting the books in years four through seven, even though most of it is deferred, the league counts the full AAV against the luxury tax threshold. That means the Dodgers were eating a massive tax hit from year one even though their actual cash outlay was a fraction of the reported number. The CBA rules do not distinguish between guaranteed and deferred money for tax purposes, and that is where the structural advantage comes from. There is also the disability insurance angle that most casual analysts skip. The original terms included a full baseball-related disability insurance policy that would have protected the entire $700 million if Ohtani suffered a career-ending injury. That policy was later voided by MLB after investigation into how it was arranged. If the voiding holds, the Dodgers are now exposed to the full risk on the deferred portions without that backstop. For a contract this large, that is a material change in the risk profile.
The Media Rights Component That Actually Funded This
What made the deal structurally possible was the new local media rights agreement between the Dodgers and Disney. The $.65 billion deal with the Bally Sports successor entity provided the revenue stream that backed the payroll commitment. Without that media rights injection, the deferral structure alone would not have made the math work for a team already wrestling with competitive balance tax implications. The media deal is structured as a long-term obligation that runs parallel to the Ohtani contract. Both are seven-plus year commitments that overlap significantly in the middle years. That alignment is not coincidental. Front offices design these pairs deliberately so that the media revenue covers the deferred payments as they come due. If the media rights value drops or the audience migrates further than expected, the cushion disappears and the team is stuck with contractual obligations that no longer have matching revenue behind them.
What This Means for the Next Round of Free Agency
The Ohtani contract established a new ceiling. Before December 2023, the record for a single contract was roughly $460 million to Trout. Now the reference point is $700 million. That shifts how agents price their clients and how competing teams evaluate whether to enter a bidding war. The psychological anchor matters more than the structural details in most negotiations. Teams in markets without strong media rights deals will struggle to match this structure. The deferred compensation model works best for organizations that have predictable, long-term revenue streams to back the future payments. A small-market team cannot defer $600 million confidently when their television revenue is uncertain beyond three or four years. The Ohtani deal essentially created a two-tier free agency system where only teams with major media backing can compete at the highest end. The arbitration and performance incentives embedded in the contract are also worth watching. Ohtani has incentives tied to MVP voting, All-Star selections, and playoff appearances that could adjust the effective value. These are standard in large contracts, but the thresholds here are set at a level that assumes continued elite production. If Ohtani misses significant time again, the deferred money still comes due regardless, which is the core risk the team is taking on.


